The Structural Dynamics of the Rupee and Global Market Pressures
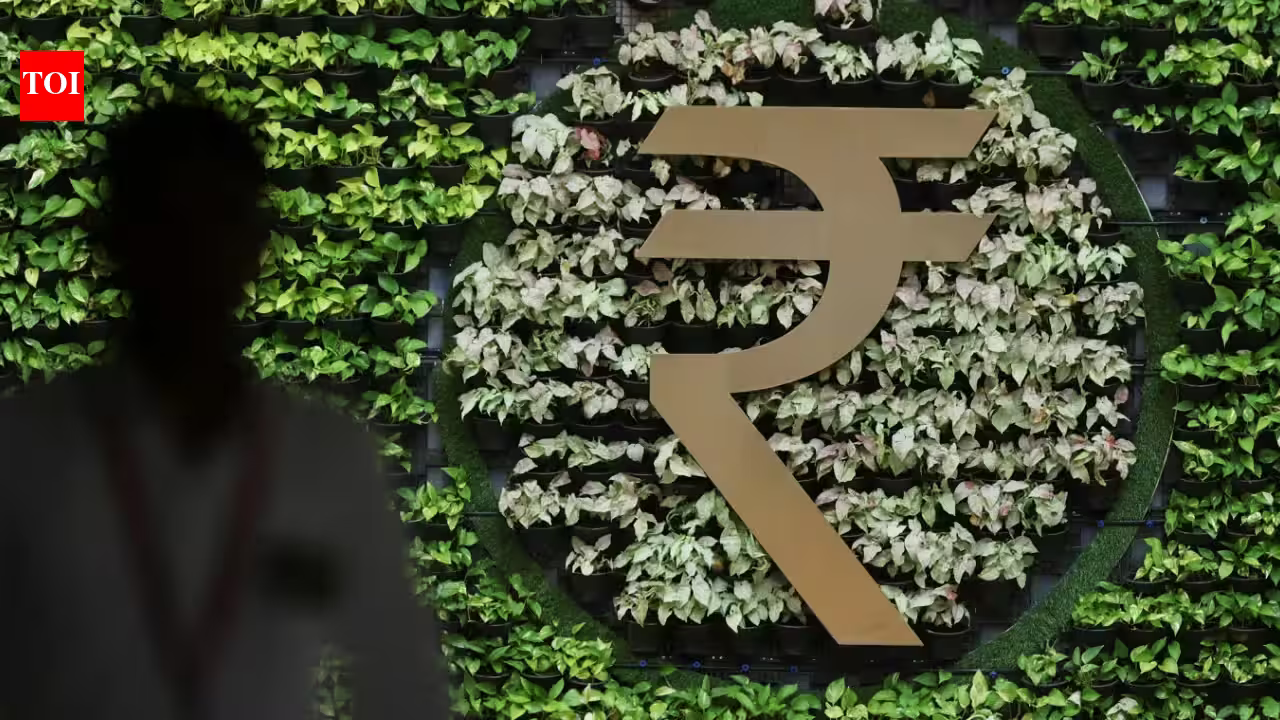
The movement of the Indian rupee against the US dollar is a complex interplay of macroeconomic indicators, central bank policy, and global commodity cycles. As the currency approaches the critical threshold of 96 per dollar, market participants remain hyper-focused on the Reserve Bank of India’s (RBI) tactical interventions. The recent fluctuation, characterized by a slight appreciation despite the persistent strength of the US dollar index, highlights a market in a state of delicate equilibrium. For investors and corporate treasuries operating within the Indian landscape, this period serves as a case study in managing volatility while balancing import costs against capital inflows.
The current currency environment is defined by competing forces. On one side, the domestic equity market shows resilience, often buoyed by favorable earnings growth and structural reforms, which attracts foreign portfolio investment. On the other side, the external sector remains vulnerable to fluctuations in crude oil prices. As India remains a net importer of oil, any upward movement in Brent crude directly impacts the current account deficit, creating fundamental pressure on the rupee. The recent decline in forex reserves—while significant—must be viewed in the context of the RBI’s strategic deployment of its war chest to maintain orderly market conditions rather than adhering to a strict peg.
The Role of Central Bank Intervention in Currency Stabilization
The Reserve Bank of India plays a pivotal role in acting as the ultimate backstop for the rupee. By intervening in the interbank foreign exchange market, the central bank prevents excessive volatility that could disrupt business planning and inflationary expectations. The market’s fixation on the 96-per-dollar level is not coincidental; it reflects a psychological and tactical barrier where the RBI has historically demonstrated a willingness to provide liquidity or absorb excess demand.
For domestic businesses, this interventionist posture provides a predictable, albeit artificial, range for currency movement. It allows firms with significant foreign currency exposure to hedge their positions with greater confidence. However, reliance on central bank intervention is a double-edged sword. While it shields the economy from sudden shocks, it also consumes valuable foreign exchange reserves. The recent drop in reserves to 780.782 billion dollars serves as a reminder that the cost of defending a currency is high. Strategists must evaluate whether the current reserves are sufficient to sustain long-term defense if global interest rate differentials remain unfavorable for emerging market currencies.
Impact of Global Commodity Cycles on India’s Import Bill
India’s import bill is disproportionately sensitive to the global pricing of energy commodities. When oil prices trade above the 100-dollar-per-barrel mark, the demand for greenbacks from domestic oil marketing companies creates persistent structural selling pressure on the rupee. This phenomenon is a primary driver of the currency’s depreciation bias. Even when domestic equities are performing well, the underlying demand for foreign currency to settle energy payments often offsets the positive sentiment brought in by foreign institutional investors.
Business leaders must recognize that energy-induced currency depreciation is a systemic risk that transcends short-term market movements. A high import bill does more than just weaken the rupee; it feeds into domestic inflation by raising the landed cost of fuel and intermediate goods. For sectors such as manufacturing, transportation, and logistics, these costs are difficult to pass on fully to the end consumer, often leading to margin compression. Consequently, the correlation between Brent crude futures and the rupee-dollar pair remains one of the most critical metrics for corporate financial planning in India.
Equity Market Performance as a Counterbalance to Forex Risk
The Indian equity market, represented by indices such as the Sensex and Nifty, frequently acts as a buffer against currency decline. When FIIs perceive the domestic economic narrative as robust, the inflow of capital into stocks can provide enough demand for the rupee to strengthen, or at least stabilize, despite broader global weakness. The net buying by FIIs in recent sessions illustrates a recurring pattern where foreign capital seeks returns in India’s growth story, effectively countering the outflows driven by a stronger dollar index.
However, the link between equity performance and currency stability is not absolute. If the US dollar index continues its upward trend due to aggressive monetary policies in developed markets, the “carry trade” may become less attractive, leading to portfolio outflows regardless of domestic growth prospects. Therefore, domestic business stakeholders should monitor the divergence between FII activity and the dollar index. A situation where FIIs begin to retreat while the dollar index rises is the scenario that poses the greatest risk to currency stability, potentially forcing the RBI to allow a more significant adjustment in the rupee’s value to maintain competitiveness.
Strategic Outlook for Currency Risk Management
Moving forward, the rupee is likely to remain tethered to a range determined by the RBI’s threshold and the prevailing price of crude oil. For companies that are heavily integrated into global supply chains, the imperative is to shift from reactive hedging to proactive financial risk management. Relying on the central bank to manage the 96-per-dollar barrier is an insufficient strategy for long-term operational health. Businesses must integrate currency volatility into their pricing models and utilize various derivative instruments to mitigate the impact of sudden swings.
Additionally, the broader economic context suggests that India’s forex reserves, while lower than previous peaks, remain formidable by international standards. This provides a safety net that many other emerging economies lack. As the global economy navigates the uncertainty of interest rate trajectories and geopolitical tensions, the rupee’s ability to find support near critical psychological levels will continue to depend on the synergy between robust domestic demand, prudent fiscal management, and the tactical interventions of the RBI. Maintaining a realistic perspective on these factors is essential for any professional navigating the complexities of the Indian financial market today. The current period of stability is not a permanent state but a carefully managed interval that demands diligent oversight and disciplined financial strategy.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News