Understanding the Merchant Discount Rate in the UPI Ecosystem
The rapid adoption of the Unified Payments Interface (UPI) has fundamentally altered the Indian financial landscape. By enabling instantaneous, frictionless transfers, UPI has become the backbone of the country’s digital economy. Recently, however, discussions surrounding the Merchant Discount Rate (MDR) have triggered significant public and industry scrutiny. Clarifying the mechanics of these charges is essential to maintaining trust in a system that now processes over 30 lakh crore rupees in transaction value.
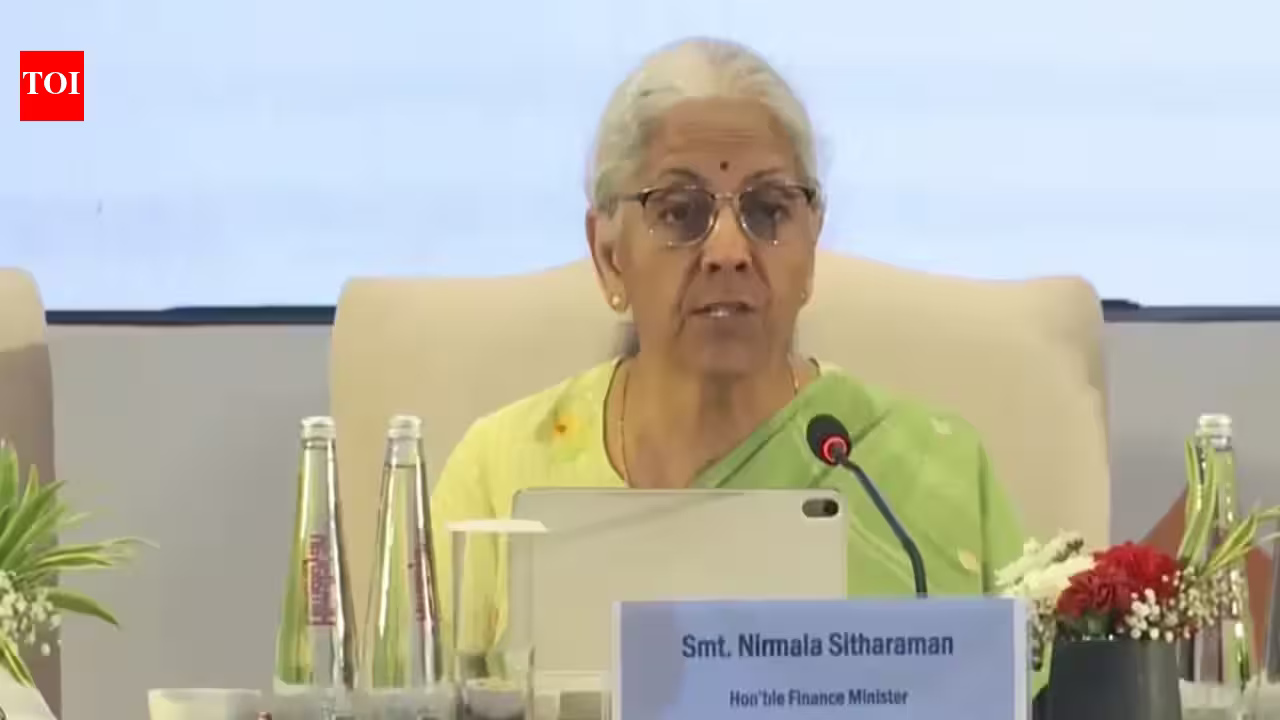
Finance Minister Nirmala Sitharaman has explicitly stated that MDR is not a government levy. It is not a tax, a cess, or a surcharge, and it does not contribute to the Consolidated Fund of India. Instead, MDR represents the cost of service provision by various stakeholders in the payment value chain, including the National Payments Corporation of India (NPCI), payment aggregators, merchant banks, and providers of point-of-sale (POS) infrastructure. By decoupling these charges from government revenue, policymakers aim to reassure the public that the cost structure is purely a commercial arrangement between private service providers and the merchants who utilize their infrastructure.
The Mechanism of MDR Charges
At its core, MDR is a fee paid by a merchant to their bank and other processing entities to cover the costs associated with facilitating digital transactions. The debate currently centers on transactions exceeding 2,000 rupees. For transactions below this threshold, the policy framework remains unchanged, exempting merchants from these costs. This distinction is crucial, as it ensures that small-ticket daily transactions—which constitute the vast majority of UPI usage—remain entirely cost-free for both the consumer and the small business owner.
The finance minister’s clarification reinforces the principle that these costs are to be absorbed by the merchant, effectively categorizing them as an operational expense similar to rent or inventory costs. Crucially, the directive emphasizes that these costs should not be passed on to the end consumer. When a business accepts a digital payment, it benefits from increased security, better record-keeping, and the convenience of rapid fund settlement. These systemic advantages are intended to justify the merchant’s expenditure, rather than shifting the burden onto the buyer at the checkout counter.
Market Impact and Merchant Segmentation
A critical concern regarding MDR is the potential for inflationary pressure if merchants choose to surcharge their customers. However, data provided by the NPCI suggests that the actual risk of consumer-facing charges is confined to a relatively small segment of the market. According to Dilip Asbe, the managing director and CEO of NPCI, approximately 75 percent of UPI transaction value currently falls outside the scope of the MDR charging framework. Because the vast majority of UPI-enabled merchants are smaller entities that primarily handle smaller transaction sizes, they remain untouched by these specific policies.
Furthermore, the MDR collections are highly concentrated. About 80 percent of the total revenue generated through these fees comes from large enterprises with an annual Gross Merchandise Value (GMV) exceeding 1,000 crore rupees. These large-scale players are already accustomed to paying significant fees for credit card processing and are integrated into sophisticated financial ecosystems. It is highly improbable that such organizations would deviate from their established operational models by passing nominal UPI charges onto individual customers, as doing so could negatively impact customer loyalty and overall transaction velocity.
An additional 10 percent of MDR revenue is generated from businesses with a turnover of at least 1 crore rupees. Similar to the larger entities, these businesses generally view digital payment acceptance as a cost of doing business. The remaining 10 percent represents the only area of potential friction, where smaller businesses might be tempted to pass the charge to customers. The banking industry, in coordination with the NPCI, is currently focusing its efforts on this segment to ensure transparency and compliance, aiming to prevent the proliferation of unauthorized surcharging practices.
Financial Sustainability and Infrastructure Growth
The long-term success of the UPI framework necessitates a sustainable revenue model. During its nascent stages, the infrastructure was heavily subsidized by banks and fintech participants to encourage rapid market penetration. This period of intense investment lasted for over half a decade, resulting in the robust system that India enjoys today. However, for the ecosystem to innovate further—moving beyond basic payments to include credit, insurance, and investment products—there must be a clear pathway for stakeholders to recoup their capital investments.
The reduced pace of growth in UPI volumes, relative to the initial explosive phase, can be partially attributed to the tapering of these heavy investments. As participants in the ecosystem seek a more balanced financial model, the industry is transitioning from a growth-at-all-costs phase to a maturity phase defined by operational sustainability. By formalizing the MDR framework for high-value transactions, the industry is attempting to create a self-sustaining cycle where service providers can continue to invest in security, scalability, and new financial products without requiring excessive public subsidies.
Future Outlook and Strategic Implications
As India continues to push toward a target of one billion users, the infrastructure must be capable of handling an unprecedented volume of complex transactions. The integration of credit into UPI, for instance, requires a sophisticated assessment of risk and settlement logic, which naturally carries costs. The current MDR policy is a logical evolution toward creating an institutionalized financial service rather than a purely experimental payment mechanism.
The primary challenge moving forward lies in the education of merchants and the protection of consumers. While the regulatory stance is clear—that MDR is not a consumer cost—enforcement and transparency will be the ultimate determinants of success. Merchants must be educated on the long-term benefits of digital payments, such as access to credit facilities that are increasingly being tied to digital turnover data. By shifting the focus from the cost of the transaction to the value derived from the digital audit trail, the government and the banking sector aim to foster an environment where digital adoption continues to grow at double-digit rates.
Ultimately, the goal is to balance the needs of the payment ecosystem participants with the interest of the retail consumer. As UPI evolves from a simple transfer mechanism into an all-encompassing financial super-app, the underlying economics must remain transparent. By isolating high-value, high-volume transactions for MDR, the framework protects the common citizen while ensuring that the infrastructure remains resilient, secure, and capable of supporting the next wave of digital innovation in India. The current policy, while generating discourse, serves as a necessary step in hardening the most vital piece of digital public infrastructure in the modern Indian economy.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News