Expanding the Horizon for Foreign Portfolio Investors in Commodity Markets
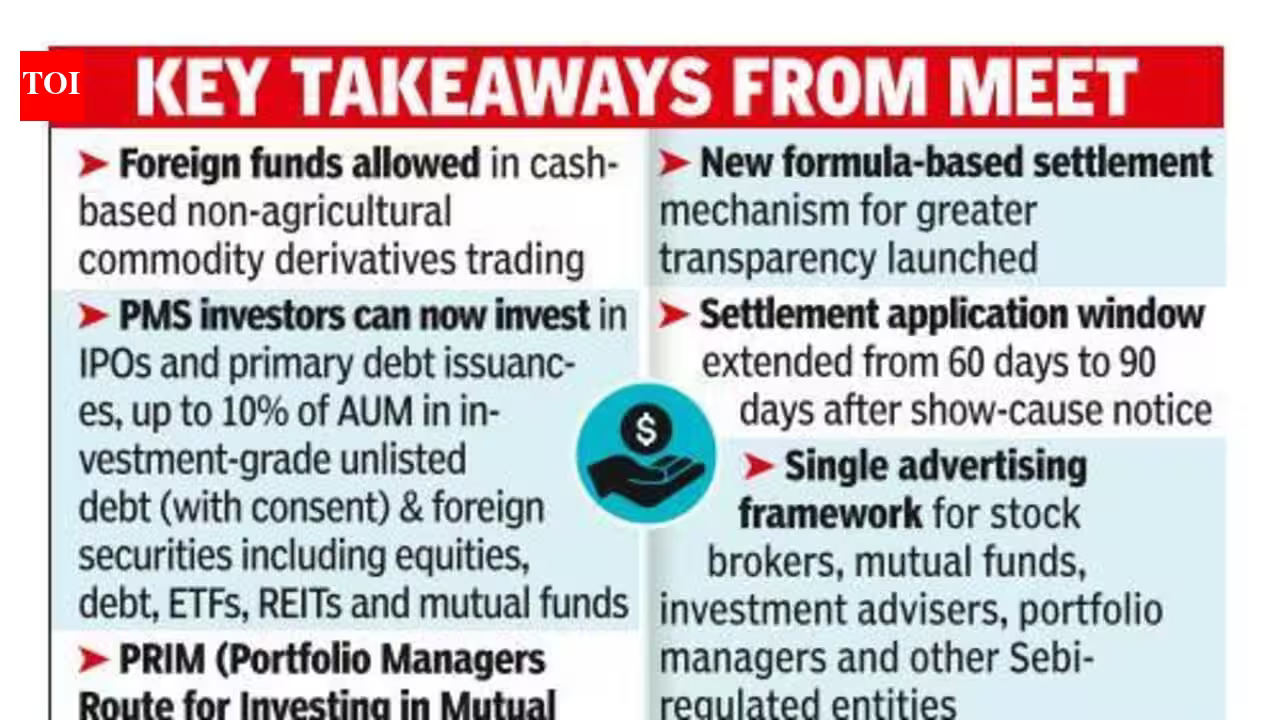
The Securities and Exchange Board of India (Sebi) has embarked on a strategic policy shift designed to deepen the capital markets and enhance the maturity of the domestic commodity ecosystem. By permitting Foreign Portfolio Investors (FPIs) to participate in non-agricultural commodity derivatives, the regulator is addressing a long-standing request from global fund managers and local market participants. This move is fundamentally aimed at injecting higher liquidity into non-agri segments, such as precious metals, base metals, and energy derivatives, which have historically been dominated by domestic retail and institutional players.
From a market mechanics standpoint, the inclusion of institutional foreign capital is expected to bridge the gap between physical market prices and derivative valuations. In many commodity segments, liquidity constraints often lead to high volatility and information asymmetry. By allowing FPIs to enter this arena—specifically through index-based derivatives and non-cash-settled non-agricultural contracts—Sebi is fostering a more robust price discovery mechanism. This alignment is critical for Indian businesses that rely on these markets for hedging their raw material costs. As global entities bring their risk management expertise and capital to the Indian bourses, the convergence between physical spot prices and futures prices is likely to become more efficient, providing a stable environment for industrial hedging.
Modernizing the Portfolio Management Services Landscape
In a parallel move to modernize wealth management, Sebi has signaled a major expansion for Portfolio Managers. The decision to permit these entities to invest in foreign equities, debt instruments, exchange-traded funds (ETFs), Real Estate Investment Trusts (REITs), and mutual funds marks a significant step toward the globalization of domestic investment portfolios. For high-net-worth individuals and institutional clients in India, this diversification is crucial for mitigating country-specific risks and capturing value in international markets.
Furthermore, allowing portfolio managers to invest up to 1.25 times their clients’ assets in exchange-traded derivatives provides a sophisticated tool for leverage and risk management. This adjustment acknowledges that as the Indian market integrates further with the global economy, domestic fund managers require a broader toolkit to compete on a global scale. By enabling investment in unlisted debt securities, the regulator is also effectively expanding the investment universe, allowing for a more nuanced approach to credit allocation that was previously restricted to specific asset classes. This transition reflects a regulatory trust in the professionalization of Indian portfolio management, moving toward a more flexible framework that prioritizes investor outcome over rigid, product-specific mandates.
Overhauling the Enforcement and Settlement Framework
A core component of Sebi’s recent policy announcement is the comprehensive overhaul of its settlement mechanism for rule violations. The regulator is moving toward a more formulaic and transparent approach to calculating settlement amounts, which will be anchored in a base amount linked to the minimum statutory penalties prescribed under securities laws. This shift away from ad-hoc calculations toward a standardized, rules-based system provides much-needed clarity for regulated entities.
The structure of the new settlement framework—comprising the settlement amount, the disgorgement of wrongful gains, and specific remedial terms—is designed to act as a more effective deterrent against market malpractice. Furthermore, the introduction of a fast-track settlement mechanism for cases involving amounts up to Rs 10 lakh is a pragmatic administrative reform. By streamlining the adjudication of smaller-scale violations, the regulator can allocate its enforcement resources more effectively toward high-impact market manipulation cases. This dual strategy of institutionalizing penalties while accelerating the closure of minor cases serves to strengthen market integrity and reduce the legal uncertainty that often plagues regulated firms during disciplinary proceedings.
Harmonization of Advertising Standards
Sebi has also taken a definitive step toward simplifying the communication landscape by announcing a single, unified advertising code for all its regulated entities, including stockbrokers, mutual funds, investment advisers, and portfolio managers. Historically, different segments of the financial industry were subject to fragmented, entity-specific advertising norms, which created confusion and hindered uniform compliance. A single code is a progressive move that ensures investor protection remains consistent, regardless of the financial product or service being marketed.
This harmonization effort also addresses the nuanced issue of celebrity endorsements. While celebrities have historically played a role in financial marketing, Sebi’s intent to allow these endorsements with stringent, clearly defined safeguards ensures that the influence of public figures does not lead to the mis-selling of products. By mandating transparency and accountability in advertisements—whether through financial influencers or mainstream celebrity campaigns—the regulator is attempting to build a culture of responsible communication. For the retail investor, this consistency reduces the risk of being misled by high-voltage marketing campaigns that lack substance, thereby fostering a more informed investment culture within the Indian market.
Strategic Implications for the Indian Business Ecosystem
The cumulative impact of these regulatory reforms is a more mature, liquidity-rich, and globally aligned Indian market. The decision to allow FPIs into non-agri commodity derivatives is perhaps the most significant in terms of international integration. By removing barriers, India is positioning itself as a more competitive destination for global commodity trading firms. For domestic businesses, particularly those in the manufacturing, automotive, and energy sectors, the arrival of more institutional participants should translate into deeper markets, tighter bid-ask spreads, and more reliable hedging tools.
Moreover, the combination of expanded portfolio management capabilities and a modernized, transparent settlement framework reinforces the strength of India’s regulatory architecture. By balancing the need for market growth—through the permission of new instruments and foreign participation—with the necessity of strict, rule-based enforcement, Sebi is demonstrating a sophisticated approach to capital market supervision. These changes are not merely administrative; they are foundational adjustments aimed at sustaining long-term investor confidence. As these policies take effect, the Indian financial sector will likely see increased institutional participation, a more diverse range of asset allocation strategies for wealthy investors, and a clearer, more predictable enforcement environment that rewards compliance and discourages regulatory lapses. This trajectory is essential for India’s aspiration to become a global financial hub, where market depth and regulatory excellence go hand in hand.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News