



The Shifting Dynamics of the Global Energy Market
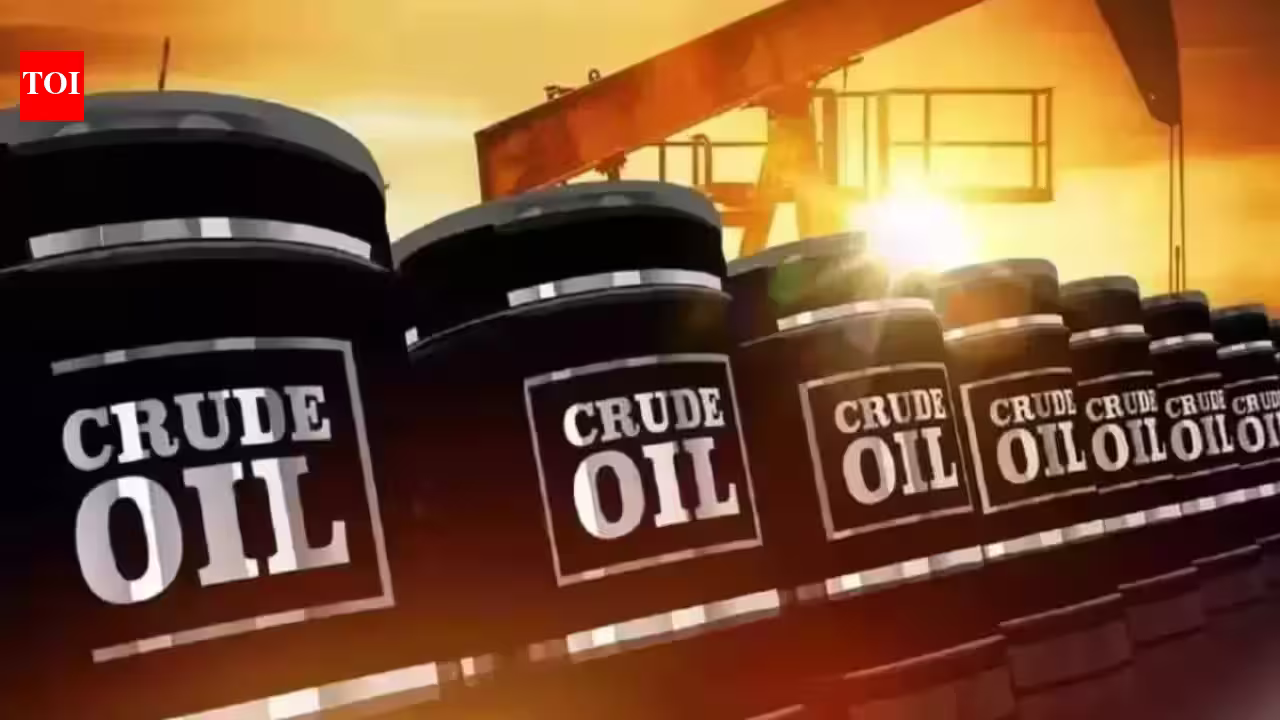
The global oil market is currently undergoing a significant transition, moving away from the pervasive fear of supply shortages that characterized the previous nine months. Recent market data indicates that crude prices are softening as supply concerns diminish, driven by a recovery in shipping through critical maritime chokepoints and a recalibration of international supply forecasts. After a long period of price volatility tethered to geopolitical tensions in the Middle East, the narrative has shifted toward a potential surplus, forcing traders and investors to re-evaluate their positions on energy commodities.
International benchmarks such as WTI and Brent crude have retreated from their previous highs as the global energy landscape adjusts to restored logistics. The International Energy Agency (IEA) has played a pivotal role in this sentiment shift, projecting that the fourth quarter of this year will likely witness a surplus of supply. With an anticipated supply of 105 million barrels per day, production is expected to outpace demand by approximately 1.7 million barrels per day. This fundamental reversal of the previously forecasted deficit serves as a primary driver for the current downward pressure on prices.
Geopolitical De-escalation and Logistics Recovery
For most of the last year, oil prices were buoyed by a perceived risk of supply disruption due to the conflict between Iran and regional powers. However, the recent stabilization in exports through the Strait of Hormuz suggests that the worst-case scenarios regarding regional logistics have not materialized. As shipments begin to approach pre-war levels, the risk premium previously baked into the cost of a barrel is being systematically dismantled.
The recovery of shipping routes has been further bolstered by policy interventions in the United States, specifically the 90-day extension of the Jones Act waiver. By permitting foreign-flagged vessels to transport fuel between domestic ports, the US has effectively increased its shipping capacity, reducing the bottleneck in fuel distribution. This regulatory flexibility has widened the pool of available tankers, easing the pressure on internal supply chains. While geopolitical risks persist—as evidenced by recent reports of maritime incidents near the Strait of Hormuz—the market is increasingly prioritizing statistical supply data over speculative risk assessments.
Implications for the Indian Economy
India, as one of the world’s largest importers of crude oil, occupies a unique position in this changing market. Historically, high oil prices have been a primary contributor to India’s current account deficit and inflationary pressures. A decline in global crude prices provides significant fiscal relief to the Indian government and the Reserve Bank of India (RBI). When oil costs stabilize or decrease, the country’s import bill shrinks, which directly strengthens the Indian Rupee and provides the central bank with more leeway in its monetary policy.
For Indian industry, lower crude prices translate into reduced input costs for the logistics, manufacturing, and chemical sectors. Since energy remains a vital component of the inflationary basket, a cooling in global oil markets is a positive development for retail inflation management. Furthermore, with the government focusing on long-term energy security through increased refining capacity and diversification of import sources, a surplus in the global market allows Indian state-run oil marketing companies to purchase feedstock at more favorable rates. However, India must remain cautious; while the current trend is favorable, the volatility of shipping freight rates—which remain elevated despite the increased availability of tankers—means that the landed cost of oil may not drop as sharply as the benchmark commodity price.
The Persistent Challenge of Freight and Infrastructure
It is crucial to note that while the commodity price of crude is falling, the cost of distribution remains a concern. Global shipping, particularly in the Middle East, continues to contend with elevated freight rates. The risks associated with the Strait of Hormuz, such as the recent reports of naval mines and vessel-related incidents, keep insurance premiums high and shipping schedules tight. Even when tankers are physically available, the cost to operate them in high-risk zones ensures that energy remains a premium logistics asset.
The reliance on these strategic waterways necessitates a continued focus on supply chain resilience. For businesses that rely on refined products like diesel and petrol, the high cost of transport often masks the benefit of lower raw crude prices. As long as regional instability threatens the efficiency of maritime transport, consumers and industries may see a disconnect between the price of crude on the commodities exchange and the final price of fuel at the pump or the factory gate.
Future Outlook and Strategic Considerations
Looking ahead, the market appears to be transitioning into a period of increased supply availability. The release of emergency oil reserves, including substantial quantities of diesel, is designed to further bridge any remaining gaps in the market. This coordinated move by international energy bodies serves as a buffer against potential future supply shocks, signaling a return to more traditional market dynamics where supply and demand equilibrium—rather than speculative geopolitical fear—dictates pricing.
For corporate strategists and policy planners, the current environment necessitates a shift in focus. The era of assuming perpetual supply tightness is over, at least for the medium term. Organizations should capitalize on this period of relative stability to optimize their energy procurement strategies. For a country like India, this window of lower global prices is an ideal opportunity to build up strategic petroleum reserves and invest in energy-efficient technologies, ensuring that the economy is better insulated from the next inevitable cycle of volatility.
Ultimately, the crude oil market is proving its resilience. While the transition from a deficit-prone market to a potential surplus creates immediate downward price pressure, the underlying fundamentals of global energy demand remain robust. The challenge for stakeholders will be to navigate the gap between falling commodity prices and the persistent costs of global logistics, ensuring that the benefits of a more balanced supply landscape are realized across the broader economy. The coming quarter will be a critical litmus test for these forecasts, as the market observes whether the projected surplus materializes in alignment with current predictions or if unforeseen developments require another round of recalibration.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News