The Critical Role of Original Property Deeds in Real Estate Transactions
In the Indian real estate market, original property documents are far more than mere paperwork; they are the bedrock of legal title and ownership authentication. When an individual secures a home loan, they are contractually obligated to deposit these original title deeds with the lending institution as collateral. This arrangement functions as a security measure for the bank, ensuring that the borrower cannot create secondary encumbrances or transfer the property without settling the outstanding debt.
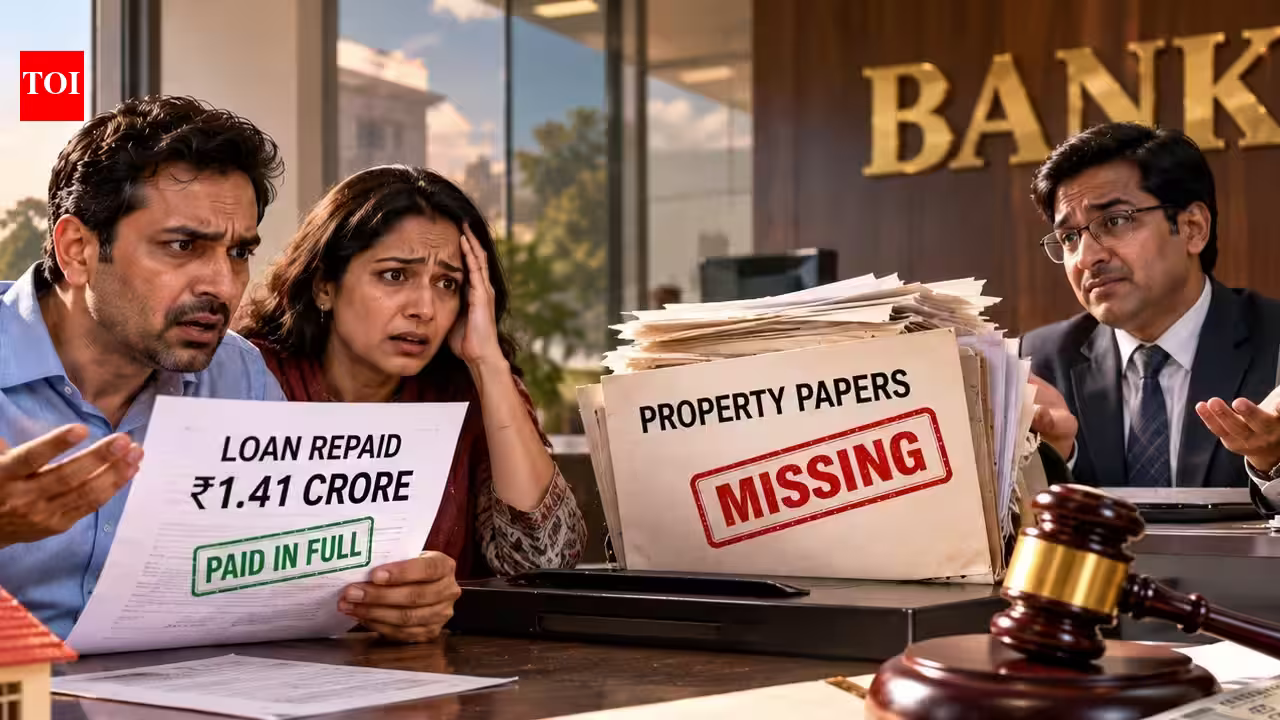
However, a recent case adjudicated by the Delhi State Consumer Disputes Redressal Commission has brought to light the significant liabilities banks face when they fail to maintain the custody of these vital records. The incident involving a Delhi couple, who successfully fought for compensation after their bank lost their property papers, serves as a wake-up call for both financial institutions and property owners. The loss of a sale deed is not a trivial clerical error; it is a fundamental deficiency in service that undermines the borrower’s ability to conduct future financial and legal transactions involving the property.
Assessing the Legal and Financial Consequences of Lost Documents
When a bank misplaces original title deeds, the property owner enters a state of legal vulnerability. In India, while a certified copy from the Sub-Registrar’s office can serve as a substitute, it does not carry the same weight as the original document. Prospective buyers or subsequent lenders often view a property lacking its original sale deed with skepticism, fearing potential legal disputes or clouded titles. This reality translates into a tangible financial loss, as the marketability of the asset is diminished.
The Delhi State Consumer Disputes Redressal Commission recognized this, noting that the inability to present an original deed restricts a homeowner’s capacity to freely transfer or mortgage their property. The judicial stance in recent cases, including the reference to the Manoj Madhusudhanan versus ICICI Bank precedent, confirms that courts are increasingly viewing the loss of such documents as a severe breach of the fiduciary duty owed by the bank to the customer. The compensation awarded—in this instance, Rs 15 lakh—reflects the recognition that the inconvenience and potential depreciation of the asset’s value caused by the bank’s negligence must be adequately addressed through monetary restitution.
Institutional Accountability and the Failure of Diligence
Banks in India operate under strict guidelines regarding the safety and retrieval of mortgage documents. Following the repayment of a housing loan, lenders are obligated to return all original deeds to the borrower within a specified timeframe, often mandated by the Reserve Bank of India (RBI). The failure to do so, combined with the loss of the documents while in the bank’s possession, constitutes a clear case of deficiency in service.
In the case mentioned, the bank’s attempt to mitigate the situation by providing a police report, a public notice, and a certified copy of the sale deed was deemed insufficient to absolve them of their liability. While these steps are standard procedural requirements for lost documentation, they do not rectify the core issue: the bank failed to protect the asset entrusted to its care. The commission’s ruling serves as a stern reminder that internal clerical failures within a financial institution do not grant the entity immunity from the legal consequences of losing high-value security documents. The decision to hold the bank accountable demonstrates that the consumer redressal framework prioritizes the protection of the property owner over the internal excuses of a lending institution.
Consumer Rights and Recourse in the Indian Banking Context
For homeowners facing similar situations, the path to resolution involves a structured approach. The first step, as demonstrated by the Delhi couple, is to approach the Banking Ombudsman. This office acts as an independent authority to resolve disputes between customers and banks. However, if the redressal provided at this level is deemed inadequate—as it was in this case—consumers have the right to escalate the matter to the state-level consumer commissions.
The legal journey for the aggrieved couple underscores the importance of persistence. By refusing to accept the initial Rs 5 lakh award and pushing for a higher settlement, they set a significant benchmark for similar disputes. Borrowers should understand that their rights are protected under the Consumer Protection Act. If a bank loses documents, the customer should document all communication, seek formal acknowledgments of the loss, and keep track of all associated legal costs. Furthermore, the provision of interest at 9% per annum in the court order, calculated from the date of loan repayment, creates a financial incentive for banks to maintain better administrative practices to avoid long-term penalties.
Safeguarding Interests and Future Implications for Banks
The broader implication of this ruling for the Indian banking sector is a move toward more rigorous document management protocols. Banks are now under increased pressure to implement digitized storage, robust tracking systems, and enhanced accountability frameworks for the movement of physical property deeds. The financial burden of losing such documents—including compensation, legal fees, and reputational damage—far exceeds the cost of implementing secure storage solutions.
For property owners, this case reinforces the necessity of obtaining a formal acknowledgment letter from the bank upon the deposit of original documents. It is also advisable to keep digital copies and certified records of all communications with the lender. While the current legal landscape is becoming more favorable to the consumer in cases of negligence, the process of recovery remains time-consuming and arduous. Homeowners should treat the return of their original deeds with the same urgency as the loan repayment process itself. As property values continue to rise in urban centers across India, the importance of maintaining an unblemished chain of title will only grow, making the security of physical documentation a non-negotiable aspect of the borrower-lender relationship. The judiciary’s stance is clear: banks are the custodians of their clients’ most significant assets, and they must be held to the highest standard of care in that role.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News