The Dual Challenge of Commodity Inflation and Operational Resilience
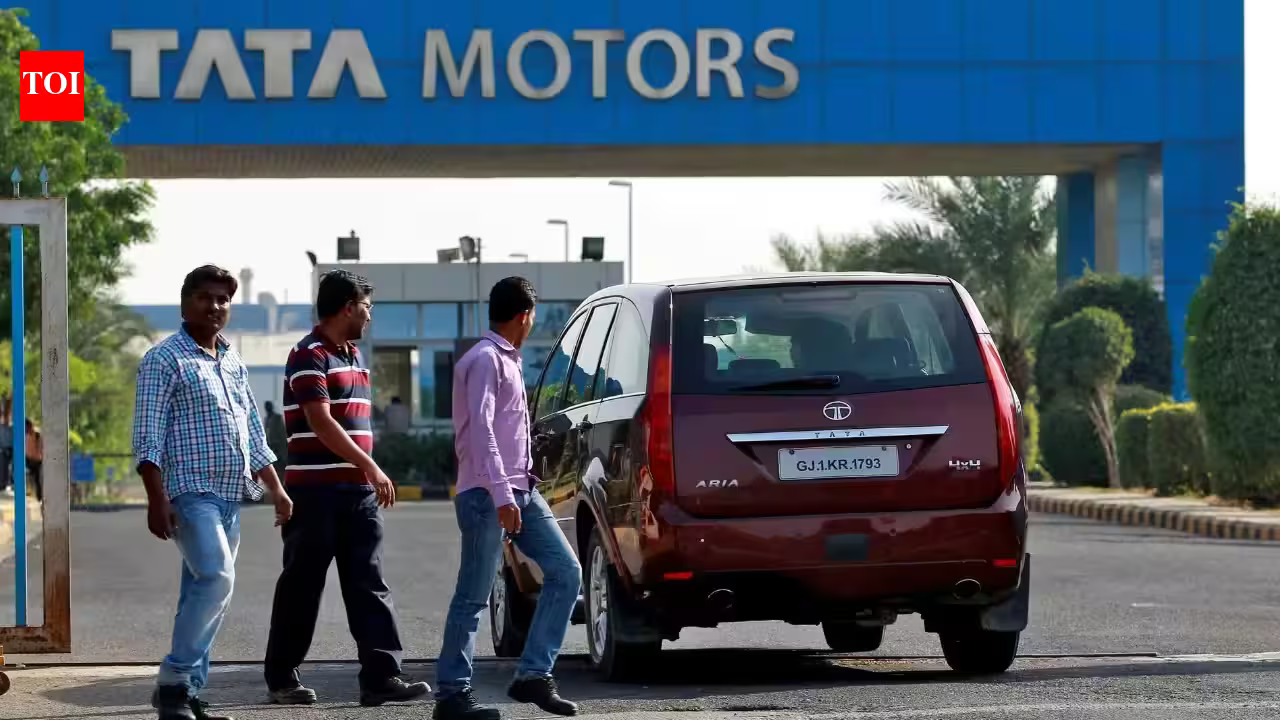
The Indian automotive sector is navigating a complex landscape defined by persistent supply chain volatility and fluctuating input costs. Tata Motors, a bellwether for the domestic passenger vehicle market, recently highlighted the intensifying pressure on profit margins caused by commodity inflation. Over the past six months, the company has observed a sustained rise in the cost of raw materials, creating a challenging environment for manufacturers aiming to maintain price competitiveness while protecting bottom-line profitability.
According to Shailesh Chandra, Managing Director of Tata Motors Passenger Vehicles, the company is absorbing a significant portion of these cost increases. With commodity-related cost impacts estimated at approximately 3%—with a margin of error of 0.5 percentage points—the reliance on price hikes alone has proven insufficient. Instead, the firm is utilizing a dual strategy: moderate price adjustments paired with an aggressive internal cost-reduction program. This approach reflects a broader industry trend where manufacturers are forced to optimize operational efficiencies to offset external economic headwinds that are beyond their direct control. By accelerating internal savings, Tata Motors aims to mitigate the burden on the end consumer, ensuring that their products remain accessible in a highly price-sensitive market.
Strategic Portfolio Bifurcation: The New Focus on Compact Sedans
Beyond macroeconomic pressures, Tata Motors is executing a significant shift in its product strategy to capture evolving consumer preferences. The company is moving to separate its compact sedan offerings, transitioning away from the singular branding approach of the Tigor. This move is driven by the distinct needs of two disparate market segments: private family buyers and commercial fleet operators.
The introduction of the new Aeris model, specifically engineered for the personal vehicle segment, signifies an intent to reclaim market share from premium hatchbacks. By tailoring the vehicle toward family buyers, Tata is addressing the aspirational demand for sedans in smaller cities and rural markets, where the vehicle form factor continues to carry significant prestige. Conversely, the existing Express brand will be dedicated entirely to taxi and fleet operators. This bifurcation is a sophisticated move designed to eliminate brand dilution. In the Indian market, private buyers are often sensitive to the “taxi” image of a vehicle. By creating a physical and brand-level separation, Tata Motors ensures that the Aeris maintains a distinct identity, free from the perception associated with high-mileage commercial usage.
Market Dynamics and the Growth of the Compact Sedan Segment
The compact sedan segment remains a pillar of the Indian automotive industry, representing approximately 3.5 lakh units annually, which constitutes nearly 80-85% of the total sedan market. With volume growth hovering between 25-26% over the previous year, the segment has demonstrated remarkable resilience despite the rapid shift toward SUVs. Notably, personal buyers currently contribute 65% of the total demand, a figure that validates Tata Motors’ decision to double down on the segment with a consumer-centric product like the Aeris.
The strategy of introducing both petrol and CNG variants for the new sedan highlights an acute understanding of the Indian demographic. In regions where fuel costs are a primary concern, the presence of factory-fitted CNG solutions serves as a powerful lever for conversion. Furthermore, by deliberately withholding an electric powertrain for the initial launch of the Aeris, the company is managing its portfolio health, avoiding internal cannibalization of its existing, highly successful electric vehicle (EV) lineup. This methodical approach to product positioning allows the company to balance immediate volume growth in the internal combustion engine (ICE) space while nurturing long-term EV adoption.
Technological Headwinds and the Emerging Semiconductor Reality
While commodity costs are a current pain point, the automotive industry remains perpetually wary of the semiconductor ecosystem. As digitalization increases across every vehicle tier, from basic sensors to advanced infotainment systems, automakers have become significantly more dependent on global chip supplies. Shailesh Chandra has pointed to a new, looming pressure: the surge in demand for high-end AI-focused semiconductors.
While the current shortage is not at the critical levels seen during the post-pandemic supply chain crisis, the diversion of manufacturing capacity toward AI-driven hardware could lead to tightening supplies for standard automotive-grade chips. Tata Motors’ proactive monitoring of this situation suggests that the company is adopting a defensive stance. For the Indian market, where lead times can significantly impact booking-to-delivery ratios, this awareness is crucial. Maintaining a steady supply chain is no longer just about logistics; it is about anticipating the technological shifts in global semiconductor manufacturing that can dictate the production capacity of every major OEM in India.
Supply-Side Constraints and the Electric Vehicle Outlook
A striking paradox within the current automotive environment is the discrepancy between demand and supply in the electric vehicle segment. For Tata Motors, the primary bottleneck for its EV portfolio is not a lack of interest or market penetration, but rather a persistent supply-side constraint. Despite the rising popularity of its electric offerings among urban commuters and environmentally conscious buyers, the inability to scale supply quickly enough to meet this demand remains a hurdle.
This scenario underscores a critical lesson for the domestic industry: the growth of EVs in India is currently supply-limited rather than demand-constrained. As the infrastructure for charging grows and consumer confidence in battery-powered vehicles solidifies, the onus is on manufacturers to resolve the intricate supply chain challenges related to battery cells and motor components. By identifying these gaps early, Tata Motors is essentially signaling that their future revenue growth is heavily contingent upon resolving these production bottlenecks. The ability to streamline the manufacturing process for EVs, while simultaneously managing the cost pressures on their core sedan portfolio, will define the company’s success in the coming fiscal years.
Conclusion: Navigating the Intersection of Efficiency and Innovation
The narrative of Tata Motors underscores the broader trajectory of the Indian automotive sector: an industry transitioning from traditional manufacturing models to highly flexible, tech-aware operations. The focus on cost reduction, while essential to survive inflationary cycles, is now inextricably linked to the ability to segment the market with precision. By splitting their brand identity, focusing on specific fuel-efficiency requirements, and keeping a watchful eye on global technology trends, the company is building a buffer against volatility.
For investors and industry observers, the key takeaway is that growth in the Indian car market is no longer driven by a “one size fits all” strategy. Instead, it requires a surgical approach—segmenting the private buyer from the commercial operator, balancing the demand for traditional fuel efficiency with the push for electrification, and navigating global semiconductor trends. As Tata Motors continues to absorb input costs while refining its product focus, its ability to execute this strategy will provide a blueprint for how large-scale Indian enterprises can remain competitive in an increasingly complex and interconnected global economy. Success will belong to those who can maintain this delicate balance, ensuring that immediate fiscal pressures do not derail long-term strategic evolution.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News