The Burden of Proof in Insurance Repudiation
The recent ruling by the District Consumer Disputes Redressal Commission in Sri Muktsar Sahib serves as a stark reminder of the rigorous evidentiary standards required when insurance companies choose to repudiate life insurance claims. In the Indian market, insurance contracts are governed by the principle of uberrimae fidei—the utmost good faith. While policyholders are legally obligated to disclose material facts concerning their health, this obligation is matched by the insurer’s duty to provide substantive, verifiable evidence if they suspect that a material fact has been suppressed.
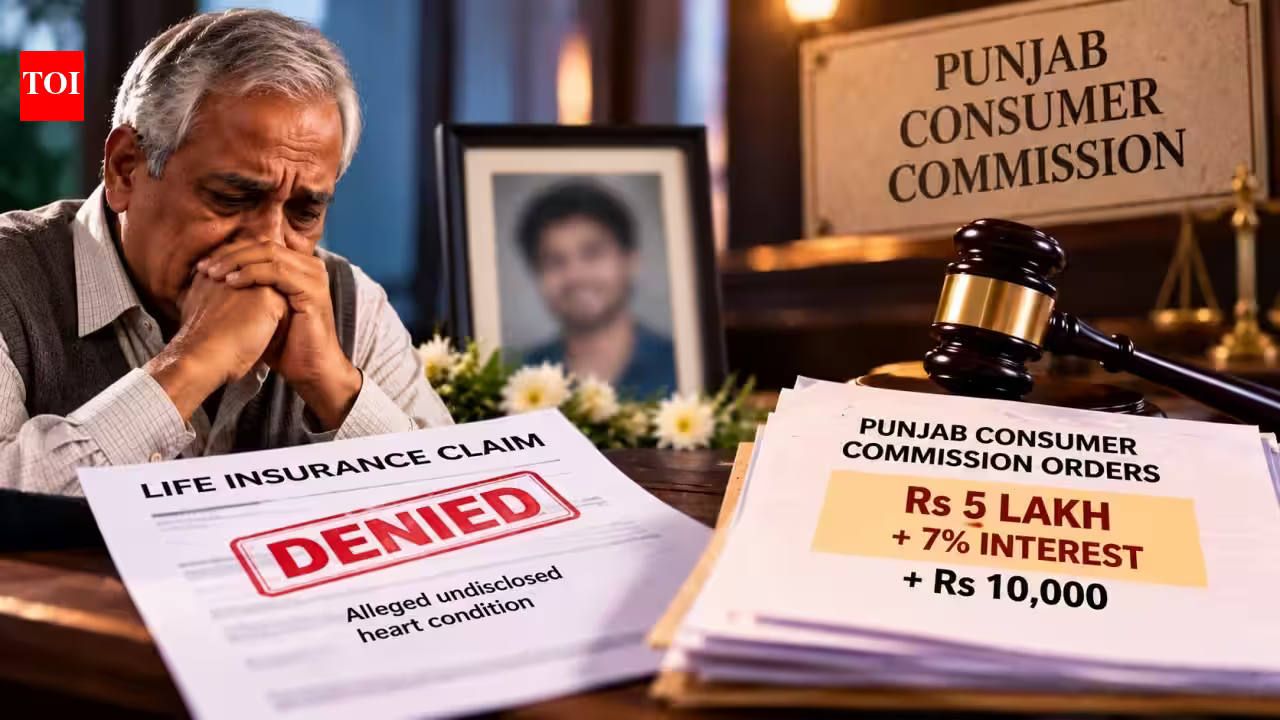
In the case involving the Life Insurance Corporation of India (LIC) and the nominee of the late Sukhdev Singh, the insurer attempted to justify the denial of a five-lakh-rupee claim by alleging that the deceased failed to disclose a congenital heart condition. However, the Commission found the insurer’s evidence lacking, highlighting a critical trend in consumer jurisprudence: an insurer cannot rely on assumptions or vague medical references to reject a legitimate claim. For businesses operating in the insurance sector, this case underscores that administrative oversight in documentation and a failure to establish a direct link between a pre-existing condition and the time of proposal issuance can result in significant legal and financial liabilities.
Administrative Lacunae and Document Integrity
A pivotal aspect of the Commission’s decision was the failure of the insurer to produce a coherent and timely proposal form. The investigation revealed that the documents submitted as evidence of non-disclosure were procedurally flawed. One proposal form lacked a signature and date, while another was dated nearly a month after the policy had already been issued.
From an operational standpoint, this highlights a systemic risk in policy administration. For insurance companies in India, the proposal form is the foundational document of the contract. If the administrative process surrounding the collection, verification, and storage of these forms is compromised, the insurer’s ability to contest claims effectively is severely hampered. The Commission’s observation that the second form was largely blank—containing only a date and a signature—points toward a lack of diligence in the underwriting process. When an insurance entity fails to maintain accurate records, it shifts the legal advantage toward the claimant, as the consumer protection framework is designed to prevent entities from using incomplete or contradictory documentation to deny benefits to beneficiaries.
The Concept of Silent Diseases and Latent Conditions
The Commission’s focus on the concept of “silent diseases” provides important context for medical underwriting in the insurance industry. In the Indian context, many policyholders may live with congenital or latent conditions of which they are unaware until a medical event occurs later in life. The ruling reiterated that failing to disclose a condition of which the policyholder had no knowledge does not constitute fraudulent suppression.
The insurer’s argument relied on a procedure that allegedly took place in 2008, nearly 14 years before the policy was initiated. The Commission correctly noted that the insurer failed to provide medical records for that specific period. Relying on a discharge summary from 2023 to retroactively prove non-disclosure in 2022 is a common tactic that is increasingly being scrutinized by consumer forums. For the insurance industry, this necessitates a more robust pre-issuance medical screening process. Relying on self-declarations is cost-effective, but when claims are denied based on retrospective medical history, the insurer must demonstrate that the insured was not only aware of the condition but willfully concealed it. Without concrete evidence of the insured’s knowledge, the claim for non-disclosure loses its legal force.
Market Insights and Consumer Protection in India
The Indian insurance sector has seen a surge in awareness, with more consumers utilizing consumer commissions to challenge corporate decisions. The judiciary and quasi-judicial bodies, such as the District Consumer Disputes Redressal Commission, are adopting a pro-consumer stance, particularly when there is an imbalance of power between a large insurer and an individual claimant.
The requirement for the insurer to pay seven percent annual interest on the claim, along with additional compensation for litigation expenses, serves as a financial deterrent against frivolous or poorly substantiated repudiations. This case sends a strong signal to the insurance market: the cost of a faulty repudiation goes beyond the sum insured. It includes reputational damage, administrative costs, and mandated interest payments. Furthermore, the reliance on outdated medical history without evidence of current symptoms creates a high barrier for insurers. Companies must now evaluate their claim settlement strategies to ensure that the criteria for rejection are supported by empirical data, not merely by the presence of a medical history that may be irrelevant to the policyholder’s status at the time of purchase.
Strategic Implications for Insurance Companies
For insurance providers, this ruling underscores the necessity of refining the underwriting and claim scrutiny processes. To mitigate risks in future litigation, insurers should consider three strategic adjustments. First, digitizing and securing the integrity of proposal forms is non-negotiable. If a proposal form is incomplete at the time of issuance, the company risks losing its right to contest future claims. Second, the medical underwriting process must be thorough, particularly for individuals with any mention of pre-existing conditions. If an insurer accepts a proposal without seeking further medical examinations despite a history of health issues, it may be deemed to have waived its right to contest that history later.
Finally, internal legal teams must ensure that repudiation notices are backed by indisputable medical evidence dated prior to the policy’s issuance. Speculation regarding a policyholder’s health status is insufficient in a court of law. By aligning underwriting practices with the current judicial expectation of “burden of proof,” insurers can reduce the frequency of unfavorable court outcomes and improve overall customer trust. As the insurance penetration in India continues to grow, maintaining a balance between risk management and ethical claim settlement is essential for the long-term sustainability of the sector. The era where a generic denial based on “non-disclosure” could easily pass judicial scrutiny is ending, making way for a more evidence-based, transparent era of insurance operations.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News