The Indian financial landscape is undergoing a series of structural shifts as of October 2026. From regulatory refinements in banking and pension management to the introduction of merchant fees on high-value digital payments, these updates reflect an evolving ecosystem that prioritizes transparency, institutional efficiency, and formalized fiscal discipline. For businesses, investors, and everyday consumers, understanding these adjustments is essential for maintaining liquidity and operational compliance.
Navigating New ATM Utilization Protocols
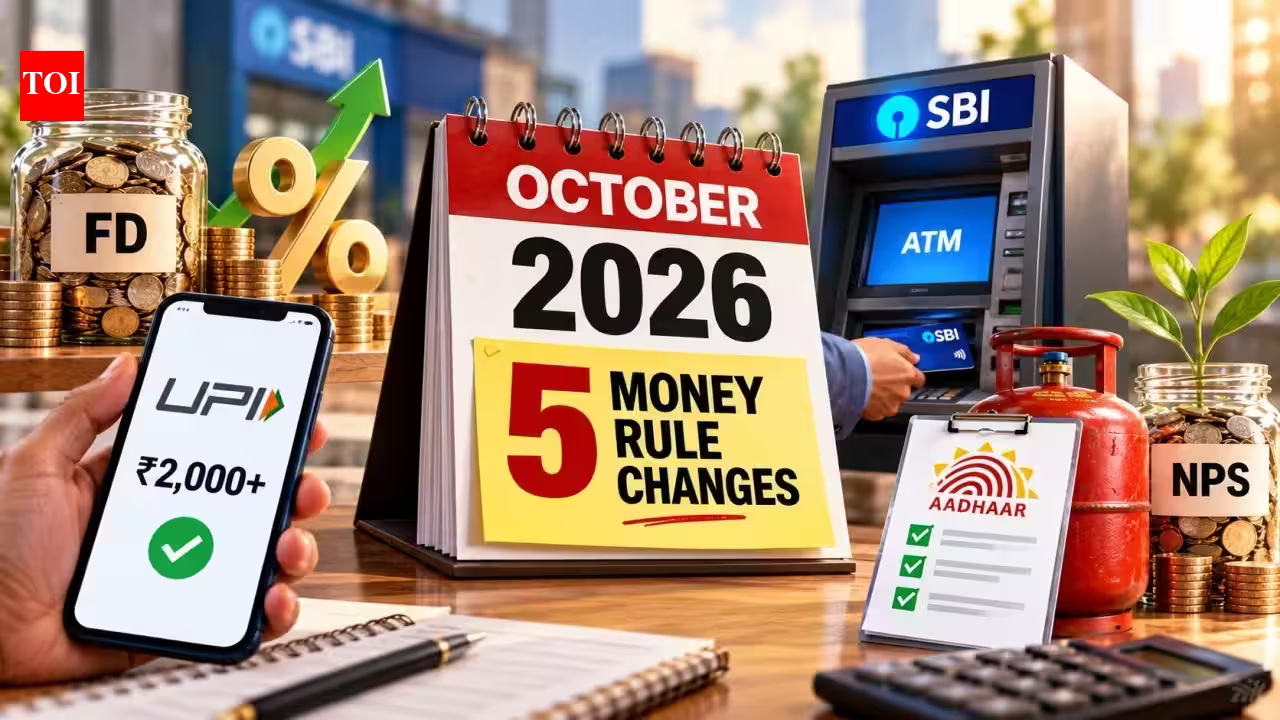
One of the most immediate changes impacting the retail banking sector involves the revision of ATM transaction limits for State Bank of India (SBI) salary account holders. Effective October 1, 2026, the threshold for free transactions at ATMs and Automated Deposit cum Withdrawal Machines (ADWMs) operated by competing institutions is being reduced from ten to five per month.
This adjustment applies to both financial and non-financial transactions, signaling a shift toward encouraging customers to utilize proprietary banking infrastructure or digital alternatives. The move is economically logical for large lenders seeking to mitigate the inter-bank interchange costs associated with ATM networking. While retail customers accustomed to the previous limit may face minor additional costs, the policy emphasizes a broader push toward digital-first banking, where electronic fund transfers remain free and unlimited. For the average employee, the directive serves as a reminder to optimize banking habits by shifting routine balance checks and mini-statement requests to mobile banking applications rather than physical kiosks.
Institutional Transparency in Bulk Fixed Deposits
The Reserve Bank of India (RBI) is implementing a significant shift in how commercial banks manage and report interest rates on bulk fixed deposits. Commencing October 1, 2026, the regulatory body requires banks to formalize their interest rate disclosures. Under these new norms, financial institutions are obligated to announce bulk deposit interest rates daily at 10 am.
The rationale behind this initiative is to standardize the environment for corporate treasury management and institutional investors. By mandating that banks offer consistent interest rates for similar classes of bulk deposits, the RBI is curbing the practice of erratic, discretionary pricing that often plagued corporate clients. While banks retain the flexibility to adjust rates based on their specific Liquidity Coverage Ratio (LCR) requirements, the new framework mandates a level of predictability that helps corporate treasurers forecast cash flows and yield generation with greater accuracy. This regulatory rigor is expected to foster a more efficient market for institutional funds, reducing information asymmetry across the banking sector.
The Introduction of Merchant Discount Rates on UPI
The Unified Payments Interface (UPI) has been the cornerstone of India’s digital payment revolution, largely due to its cost-free nature for both consumers and merchants. However, starting October 15, 2026, a structural change is being introduced: the implementation of the Merchant Discount Rate (MDR) on specific person-to-merchant (P2M) transactions exceeding Rs 2,000.
This policy reflects the sustainable scaling of the digital payments infrastructure. The exemption for transactions below Rs 2,000, as well as the continued zero-MDR framework for small traders, protects approximately 96% of total P2M transactions from additional costs. By applying the charge only to higher-value commercial transactions, the government and the National Payments Corporation of India (NPCI) are balancing the need for platform sustainability with the goal of financial inclusion. Businesses that frequently handle large-ticket retail sales will need to factor these MDR costs into their pricing models or accounting workflows, as the charges will vary depending on the specific industry category of the merchant.
Revamping National Pension System Fee Structures
The Pension Fund Regulatory and Development Authority (PFRDA) has introduced a revised fee structure for the National Pension System (NPS), impacting how subscribers interact with Points of Presence (PoPs). This adjustment, effective October 1, 2026, establishes a standardized one-time onboarding fee of Rs 200 for the issuance of a Permanent Retirement Account Number (PRAN).
This modification is part of a larger, ongoing effort to simplify administrative costs across the pension ecosystem. By centralizing and clarifying the onboarding fee, the PFRDA aims to remove ambiguity for new subscribers while ensuring that service providers are adequately compensated for the KYC and account setup processes. Importantly, the structure of this deduction is designed to be user-friendly, preventing large, lump-sum reductions that could discourage new participants. For financial advisors and distribution partners, the clear disclosure of these charges is expected to build greater confidence among investors looking toward long-term retirement planning.
LPG Subsidy Compliance and Aadhaar Authentication
The government’s drive toward digitized welfare distribution continues with the enforcement of mandatory Biometric Aadhaar Authentication (BAA) for LPG consumers. By October 1, 2026, domestic consumers who have not yet completed this authentication process must do so to continue receiving the regulated selling price and associated government subsidies.
This requirement is rooted in the objective of ensuring that fuel subsidies reach their intended recipients directly, minimizing leakage and administrative errors. As India continues to integrate its welfare schemes with Aadhaar, the requirement serves as a necessary step for citizens to maintain the cost-effectiveness of their essential household energy expenses. Households are advised to prioritize this biometric linkage, as failing to comply will lead to a transition away from the subsidized price, potentially impacting household budgets. The move underscores the broader commitment to a robust, identity-linked database that enables the state to manage fiscal outflows with higher precision.
Economic Implications of the October 2026 Reforms
Collectively, these October changes illustrate a sophisticated transition toward a high-utility, transparent, and regulated financial market. The tightening of ATM usage, the formalization of bulk deposit reporting, the calibrated introduction of UPI fees, and the enforcement of biometric authentication for subsidies collectively aim to increase the efficiency of the Indian economy.
For the private sector, the implications are twofold. First, corporations must improve their digital literacy and internal accounting processes to handle the new fee structures—most notably the upcoming UPI merchant charges. Second, the banking sector faces the challenge of adapting to more rigorous interest rate disclosure norms. While some of these changes may present immediate adjustments, the long-term benefit for the Indian market is clear: a more robust financial infrastructure that can support greater volumes of transactions while maintaining the fiscal health of both the state and private institutions. As these policies take effect, stakeholders who proactively adjust their operational strategies will likely navigate the transition with minimal disruption, positioning themselves well within a rapidly maturing fiscal environment.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News