Understanding the Nature of Transferable Development Rights
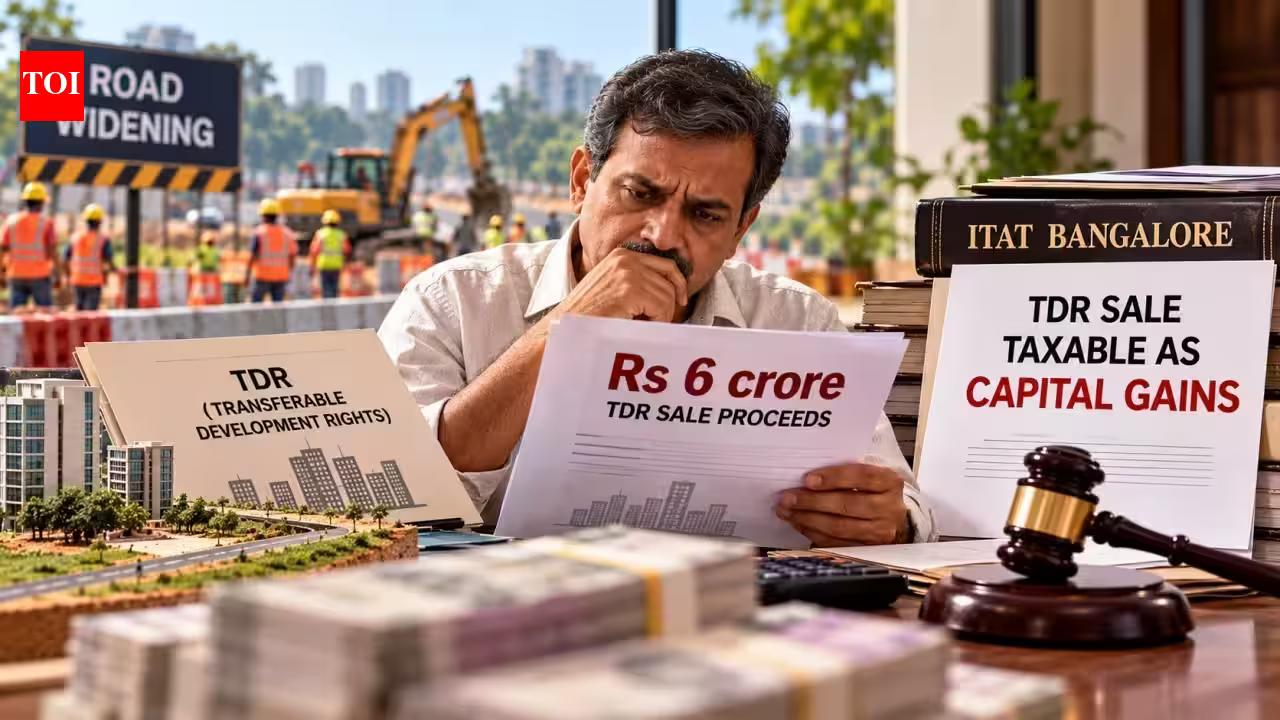
Transferable Development Rights (TDRs) have become a critical instrument in urban planning and infrastructure development across India. Often utilized by municipal bodies—such as the Bruhat Bengaluru Mahanagara Palike (BBMP) in the cited case—TDRs allow landowners to surrender portions of their property for public infrastructure projects, such as road widening, in exchange for certificates of development value. These certificates can then be deployed to construct additional floor space elsewhere or, as is common in high-demand real estate markets, sold to private developers for liquidity.
While the utility of TDRs is well-recognized in the construction sector, the tax treatment of the proceeds generated from their sale has frequently been a point of contention between taxpayers and the Income Tax Department. The core of the conflict lies in whether such receipts constitute a taxable capital gain or if they qualify as capital receipts that fall outside the tax net. For many landowners, the assumption has been that since the government grants these rights as compensation, they represent a non-taxable windfall. However, recent legal precedents indicate that the tax authorities view the acquisition and subsequent sale of TDRs through a much more rigorous lens.
The Landmark Ruling: Distinguishing Between Asset Classes
In a significant ruling delivered on August 14, 2026, the Income Tax Appellate Tribunal (ITAT) in Bangalore provided clarity on the taxability of TDR sales. The case involved a landowner who surrendered a substantial portion of his land for road development and received TDRs in return. When he sold these rights for over Rs 6 crore, he contended that the proceeds were capital receipts, effectively exempting him from income tax.
The ITAT Bangalore rejected this claim, establishing that TDRs obtained through the surrender of a specific, identifiable property qualify as capital assets. The tribunal distinguished this case from previous judgments, such as the Supreme Court’s ruling in B.C. Srinivasa Setty and the Bombay High Court’s decision in the Sambhaji Nagar Co-operative Housing Society case. In those instances, the courts dealt with situations involving self-generated development rights where no physical asset was surrendered.
The Bangalore tribunal concluded that the transaction in question was essentially a two-step process: first, the exchange of physical land for a development right, and second, the monetization of that right. By surrendering land, the taxpayer effectively “paid” for the TDRs. Therefore, the TDRs represent a capital asset with an ascertainable cost of acquisition, making the proceeds from their sale subject to capital gains tax under the Income Tax Act.
Implications of the ITAT Decision for Landowners
This ruling serves as a vital reminder to property owners who engage with municipal bodies for land acquisition projects. The primary takeaway is that the Income Tax Department is increasingly looking past the nature of the transaction receipt and focusing on the underlying exchange. Even when the government issues rights as “compensation,” the tax law treats the surrender of the underlying land as a transfer of a capital asset.
One of the arguments frequently put forth by taxpayers is the consistency of treatment—often pointing to similar cases where other individuals may have escaped taxation on similar TDR sales. However, the ITAT Bangalore emphasized that individual assessment orders do not create a binding precedent. If a previous assessment failed to scrutinize the legal nature of the TDR acquisition, it cannot be used as a shield by another taxpayer. Business owners and high-net-worth individuals must recognize that relying on the past errors or oversight of tax authorities is a high-risk strategy. Every transaction must be evaluated based on the specific facts and the prevailing legal framework at the time of the assessment.
The Importance of Cost of Acquisition in Capital Gains
While the ITAT ruled against the total exemption of the proceeds, it provided a significant victory regarding the computation of tax. The tribunal held that the Assessing Officer (AO) could not levy tax on the entire sale value of Rs 6.02 crore without accounting for the cost of the land surrendered.
Under Section 48 of the Income Tax Act, the capital gains are computed by deducting the cost of acquisition and the cost of improvement from the sale consideration. Because the landowner surrendered 2,839 square metres of land to obtain the TDRs, the market value or the historical cost associated with that specific land parcel must be factored into the equation. By mandating that the AO provide credit for the cost attributable to the surrendered land, the ITAT has ensured that tax is only levied on the net profit rather than the gross receipts. This underscores a standard principle in Indian tax law: when an asset is exchanged, the value of the consideration given up constitutes the cost of the asset received.
Strategic Considerations for Future Transactions
For individuals and real estate developers involved in TDR transactions, this ruling highlights the necessity of meticulous documentation. When surrendering land, it is imperative to maintain clear records of the original cost of acquisition, the date of purchase of the land, and the valuation attributed to the TDRs at the time of receipt.
Furthermore, taxpayers should proactively consult with tax professionals before concluding that such proceeds are exempt from taxation. The current regulatory environment in India is characterized by a push for greater transparency and digital tracking of asset transfers. As the Income Tax Department adopts more sophisticated data analytics, the probability of receiving scrutiny for high-value transactions increases.
Instead of assuming that TDRs are “tax-free” receipts, landowners should treat the transaction as a sale of a capital asset and calculate potential tax liabilities early in the process. By integrating tax planning into the decision-making phase of land acquisition and compensation, taxpayers can avoid the unnecessary financial burden of penalty interest and protracted litigation. As demonstrated by the recent ITAT ruling, while the law demands that taxes be paid on the gain, it also provides specific mechanisms to ensure that those gains are measured fairly and accurately.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News