The Legal Precedent: Banking Discretion vs. Fair Practices
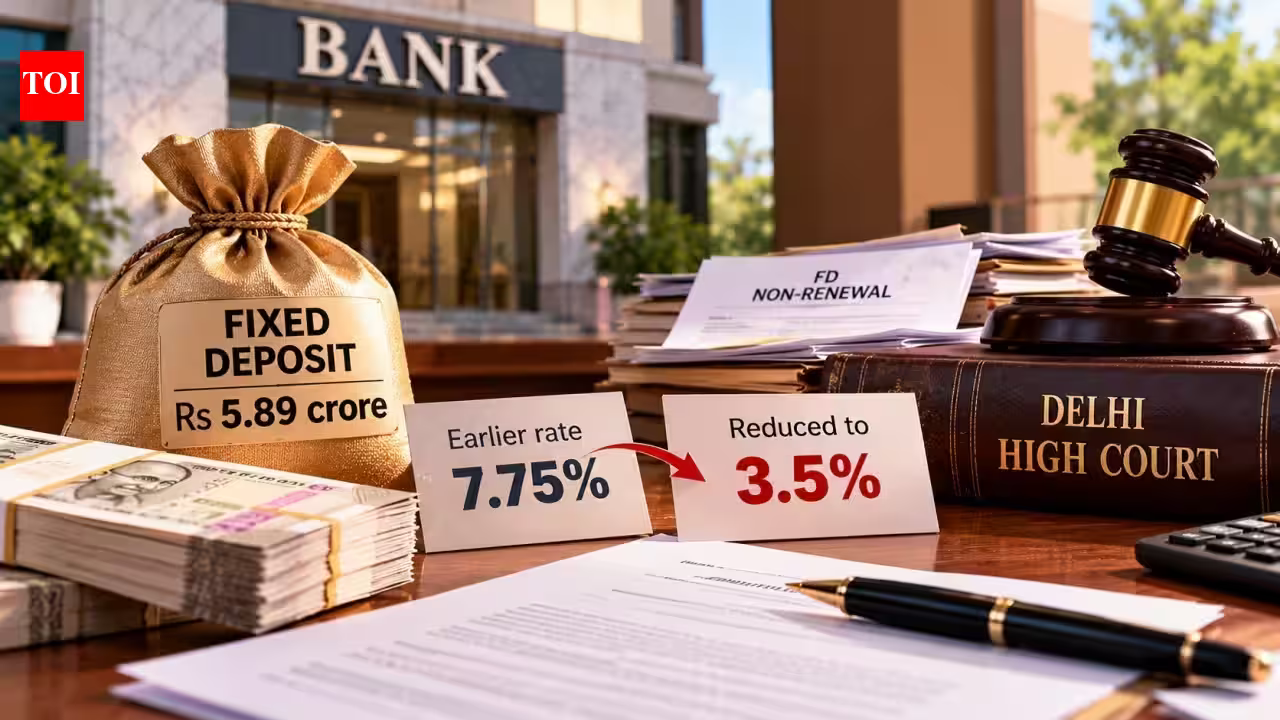
The recent ruling by the Delhi High Court regarding a fixed deposit (FD) dispute involving a substantial sum of Rs 5.89 crore has brought the nuances of banking regulations back into the public eye. The case centered on a bank’s unilateral decision to slash interest rates from 7.75% to 3.5% upon the maturity of an FD, without providing adequate notice or justification to the depositor. This judgment serves as a critical reminder that while banking institutions in India operate under the regulatory framework of the Reserve Bank of India (RBI), their internal policies regarding interest rates must remain consistent, transparent, and non-discriminatory.
The core of the dispute highlighted the tension between the freedom granted to banks to determine their deposit interest rates and the obligation to adhere to principles of fairness. The Delhi High Court’s decision to rule in favor of the deposit holder underscores a pivotal legal stance: banks cannot interpret RBI circulars as carte blanche to bypass procedural fairness. Even when banks exercise their authority under Clause 3.3 of the RBI circular, they are legally constrained by the requirement to treat similar deposits equally. The failure of the bank to demonstrate that other comparable deposits were subjected to similar rate reductions proved to be a decisive factor in the judicial outcome.
Analyzing the RBI Guidelines on Overdue Deposits
To understand the court’s decision, one must examine the regulatory environment governing fixed deposits in India. Under the RBI’s Master Direction on Interest Rate on Deposits, there are specific protocols regarding what happens when a term deposit matures but remains unclaimed or unrenewed. Traditionally, banks have relied on provisions that allow for an overdue deposit to earn interest at the prevailing savings account rate. However, the regulatory landscape shifted with amendments introduced in July 2021.
Under the updated provisions—now found in paragraph 10.2 of the RBI’s Master Direction on Interest Rate on Deposits, 2025—the rules regarding interest on overdue deposits have been clarified. The current directive stipulates that an overdue deposit should earn interest at either the savings account rate or the rate originally agreed upon at the time of the deposit, whichever is lower. This amendment was designed to provide a more balanced approach, preventing extreme disparity between original expectations and the reality of an unclaimed maturity. The bank in the recent Delhi High Court case failed to navigate these requirements correctly, relying on an outdated or overly broad interpretation of their own discretion, which ultimately weakened their position during litigation.
The Duty of Communication and Procedural Compliance
A significant aspect of the Delhi High Court’s ruling was the emphasis on the bank’s communication failures. The deposit in question was held under a specific court order, which required it to be kept secure until the underlying dispute was resolved. The court observed that the bank had not only failed to notify the stakeholders that the deposit had reached maturity but also neglected to seek instructions from the court or the arbitrator regarding the renewal or disposition of the funds.
In the Indian financial context, banks are expected to act as diligent custodians of deposited funds. When a deposit involves judicial oversight, the bank’s responsibility shifts from standard service to fiduciary compliance. By unilaterally reducing the interest rate to the savings rate without informing the court or the parties involved, the bank acted outside the scope of its operational mandate. This highlights a crucial business insight for financial institutions: automated internal processes must have “exception handling” protocols for accounts that are subject to legal holds or specific court directives. Treating a high-value, court-mandated deposit as a routine, unclaimed retail account is a procedural error that can lead to significant financial liability.
Impact on Institutional Transparency and Depositor Rights
This ruling reinforces the principle that bank policies cannot be arbitrary. The RBI circulars grant banks the flexibility to set rates across different tenures, but this flexibility is predicated on the condition that there is no discrimination between deposits accepted on the same date. The Delhi High Court’s observation serves as a warning to banks that if they decide to modify interest rates, they must be prepared to justify those changes through consistent, data-backed evidence. If two FDs of the same nature are treated differently, the bank faces a high risk of being accused of discriminatory practices.
For the retail and institutional investor, this case is an empowering development. It confirms that depositors are not entirely at the mercy of a bank’s internal policy updates. If a bank chooses to pivot its interest rate structure, it must ensure that the transition is clearly communicated and that existing contractual obligations are respected. Furthermore, it highlights the importance of explicit instructions—such as auto-renewal mandates. When a customer provides a clear instruction to renew an FD, the bank is legally obligated to prioritize that directive, which serves as a shield against the deposit being categorized as “overdue” at a lower interest rate.
Key Takeaways for Future Financial Management
The outcome of this case provides several actionable insights for both depositors and banking professionals in India. For banks, the primary takeaway is the necessity of robust communication channels. Every maturity notice should not only be automated but also auditable. When dealing with complex cases involving court orders or arbitration, banks must establish a specialized desk that ensures legal compliance before taking actions that impact interest returns. Reliance on generic operational circulars is insufficient when the specific nature of a deposit dictates a higher standard of care.
For depositors, the importance of reviewing the terms and conditions at the time of investment cannot be overstated. While the court provided relief in this instance, it was a protracted and costly process. Being proactive—such as setting reminders for maturity dates and providing clear, written instructions for auto-renewal—remains the most effective way to avoid the complications of the “overdue deposit” classification.
Ultimately, the Delhi High Court’s decision creates a clear boundary: while banks have the freedom to manage their interest rate products in response to market conditions, they remain bound by the overarching requirements of fairness and the duty to inform. The judicial system has made it clear that regulatory discretion is not an excuse for a lack of transparency. As the Indian banking sector continues to digitize and automate, this ruling will likely serve as a foundational reference for how institutions handle the lifecycle of fixed deposits, ensuring that the depositor’s rights are safeguarded against arbitrary corporate policy.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News