The Mechanics of Currency Fluctuations and RBI Intervention
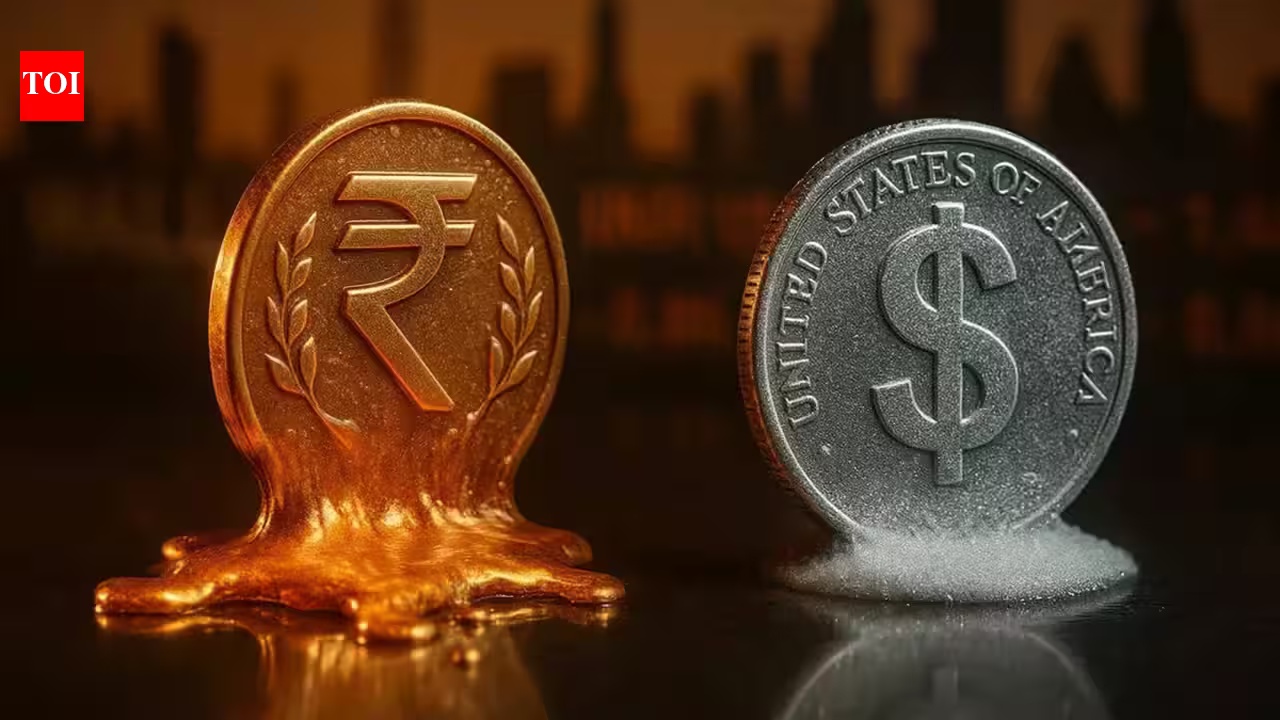
The recent appreciation of the Indian Rupee against the US Dollar serves as a quintessential case study in modern macroeconomic management. When the domestic currency gains 20 paise to reach the 94.79 level, it reflects a confluence of global market forces and calculated central bank strategy. The Reserve Bank of India (RBI) operates within a framework designed to maintain orderly market conditions rather than targeting a specific valuation. Through structural forex interventions, the central bank mitigates excessive volatility, which is essential for maintaining investor confidence and stabilizing the import-export landscape.
Currency markets are essentially reflective of geopolitical and economic signals. The weakening of the US Dollar index, which fell by 0.54% to 102, provided the necessary breathing room for the Rupee. When the dollar index retreats, emerging market currencies often experience relief as capital flows stabilize. However, the movement of the Rupee is never isolated. It remains tethered to the broader global financial environment, where interest rate expectations, inflation data, and fiscal policy in the United States exert significant pressure on the Rupee’s parity. The recent strengthening of the Rupee highlights the efficacy of the RBI’s proactive approach in balancing domestic economic imperatives against international currency trends.
The Impact of Global Macroeconomic Indicators on Domestic Trade
International economic data points, particularly those emerging from the United States, serve as the primary drivers for daily currency fluctuations in India. The recent observation that the US Producer Price Index (PPI) exceeded expectations while retail sales figures surpassed forecasts creates a complex environment for market analysts. Typically, robust US economic data prompts the Federal Reserve to maintain higher interest rates, which strengthens the dollar. However, when this is countered by falling US Treasury yields, the market finds itself in a period of adjustment.
For Indian businesses, these indicators are more than just numbers on a screen; they dictate the cost of capital and the price of imports. India remains a significant importer of crude oil, meaning that any volatility in the energy market directly translates into fiscal pressure. When Brent crude prices hover around the $105 per barrel mark, the Rupee faces structural downward pressure. Even as the dollar index weakens, the requirement for foreign exchange to pay for energy imports keeps the Rupee from witnessing unbridled appreciation. This delicate balance determines the bottom line for sectors ranging from manufacturing to aviation, which are highly sensitive to both currency volatility and oil prices.
Equities and the Divergence Between Markets
The behavior of the Indian stock market, specifically the BSE Sensex and the NSE Nifty50, often moves in a non-linear relationship with the currency. A negative start at Dalal Street, characterized by an initial dip, followed by a subsequent recovery that saw the Sensex gain 400 points, underscores the resilience of domestic investor sentiment. This recovery suggests that despite initial fears regarding global economic data, domestic demand and corporate earnings remain robust enough to absorb external shocks.
The role of Foreign Institutional Investors (FIIs) is critical in this context. Recent data indicating that FIIs were net sellers to the tune of over Rs 5,000 crore highlights a period of portfolio reallocation. Such massive selling typically exerts downward pressure on the currency, as these investors convert their rupee holdings back into dollars. Yet, the fact that the Rupee appreciated despite significant FII selling underscores the strength of the RBI’s intervention mechanism and the offsetting support provided by local institutional investors and broader market sentiment. The ability of the indices to turn green during the session indicates that the Indian market is increasingly driven by domestic participation, reducing the severity of dependence on foreign capital flows.
Structural Challenges and Long-Term Stability
While the Rupee may show gains in the short term, structural challenges persist. The primary concern remains the trade deficit and the recurring need to manage import costs in a high-price energy environment. India’s economic growth is heavily dependent on imported components, electronics, and petroleum products. Consequently, a stable currency is a prerequisite for controlled inflation. The RBI’s mandate to prevent extreme depreciation is not merely about protecting the face value of the currency but about ensuring that imported inflation does not erode the purchasing power of the average consumer.
The long-term outlook for the Indian currency depends on the government’s ability to boost manufacturing exports and reduce energy reliance through the adoption of renewable sources. As global trade dynamics shift toward diversification, India stands to gain as a manufacturing hub. However, until this transition is fully realized, the Rupee will remain susceptible to the tightening cycles of Western central banks and the fluctuating appetite of foreign investors for emerging market risk. Investors and businesses should view current fluctuations as a reflection of India’s integration into the global financial architecture, where local policy is increasingly tested by global liquidity cycles.
Strategic Outlook for Business and Investment
For corporations operating within the Indian market, the current currency environment necessitates a rigorous approach to treasury management. Hedging strategies must be revisited, especially for those sectors that are heavy on foreign currency-denominated debt or those that rely on continuous raw material imports. The recent 20-paise gain provides a tactical window for firms to settle obligations or restructure their currency exposure. Relying solely on central bank intervention for stability is a risky strategy; therefore, firms should emphasize operational efficiency and the hedging of currency risks as part of their standard financial governance.
Furthermore, the recent market performance demonstrates that volatility is the new normal. Businesses must align their long-term growth objectives with the reality that the Rupee-Dollar exchange rate will remain influenced by high-frequency data from the US. The synchronization of domestic policy with global financial realities will continue to define the success of India’s economic trajectory. Looking ahead, the focus must shift toward sustaining productivity gains, which provide the most durable foundation for currency appreciation. As India continues to solidify its position as a major global economy, the management of its currency will become a defining feature of its fiscal maturity, separating those entities that adapt to the volatility from those that remain vulnerable to it.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News