The Strategic Imperative of Bypassing the Strait of Hormuz
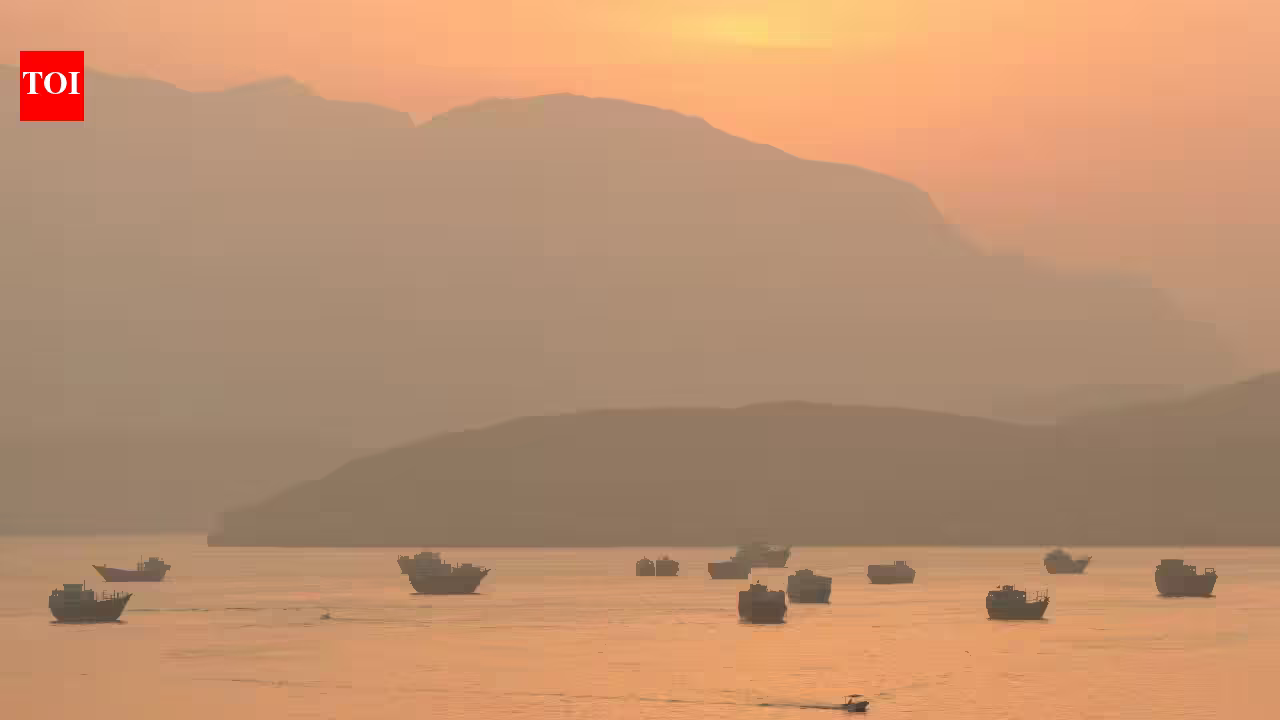
The Strait of Hormuz serves as the global economy’s most critical maritime artery. Situated between Oman and Iran, this narrow passage facilitates the movement of approximately 20% of the world’s daily oil consumption and a significant portion of its liquefied natural gas (LNG). However, the escalating volatility in the Middle East has transformed this vital lifeline into a significant point of vulnerability. For Gulf Cooperation Council (GCC) nations, the persistent threat of supply chain disruptions—whether through geopolitical posturing or direct conflict—has rendered the status quo untenable.
Business leaders and policymakers are increasingly recognizing that total reliance on this single waterway poses an existential risk to their export-driven economies. As noted by HSBC Group Chief Executive Georges Elhedery, the next five years will likely witness a fundamental shift in energy logistics. The objective is to decouple energy exports from the geopolitical sensitivities of the Strait by investing in terrestrial pipelines and alternative port infrastructure. This transition is not merely a defensive measure; it is a long-term capital allocation strategy designed to ensure the reliability of energy supply chains in an increasingly unstable global security environment.
The $1.4 Trillion Infrastructure Transformation
The scope of this pivot is immense. The Middle East, North Africa, and Turkey are currently steering a massive infrastructure pipeline valued at approximately $1.4 trillion. Within this, roughly $872 billion is allocated to individual project packages that focus on diversifying logistics and energy transport networks. This expenditure represents a deliberate pivot toward creating “bypass” corridors that can transport hydrocarbons directly to the Arabian Sea or the Red Sea, thereby circumventing the Persian Gulf entirely.
For investors, this signifies a major shift in the regional construction and logistics sector. The focus is moving away from purely residential or commercial urban development toward industrial backbone infrastructure. Projects such as extended cross-country pipeline networks, modernized high-capacity port terminals outside the Gulf, and integrated energy transport corridors are becoming the priority. These projects require not only vast capital but also advanced engineering and project management expertise, offering substantial entry points for global engineering firms and institutional financiers looking to participate in the region’s long-term modernization.
Impact on India’s Energy Security and Trade Dynamics
For India, the third-largest importer of oil globally, the security of energy logistics in the Middle East is a matter of profound national interest. A significant majority of India’s crude oil imports originate from the Persian Gulf. Any disruption in the Strait of Hormuz creates immediate inflationary pressure on the Indian economy, impacting everything from transport costs to manufacturing inputs.
If the Gulf nations succeed in rendering the Strait of Hormuz secondary by 2030, the implications for India would be largely positive. Diversified exit routes for Middle Eastern energy would provide a necessary buffer against regional conflict, ensuring a more stable supply chain for Indian refineries. Furthermore, as GCC countries diversify their economies through this $1.4 trillion infrastructure push, there are significant opportunities for Indian companies. Indian construction, engineering, and digital infrastructure firms have a proven track record in the Gulf. Participating in these multi-billion-dollar projects allows Indian enterprises to integrate themselves into the critical logistics nodes of the Middle East, effectively strengthening the bilateral economic corridor.
Navigating Short-Term Economic Headwinds
Despite the long-term potential of these infrastructure projects, the immediate economic outlook for the region remains constrained. The World Bank has forecasted a contraction of 1.3% for the Middle East, North Africa, and Pakistan region this year, a sharp turn from the 3.3% growth recorded in 2025. This downturn is directly attributable to the localized conflict, which has hampered investor confidence and slowed project execution timelines.
Institutional investors are currently practicing a dual approach. While they acknowledge the systemic risk associated with regional instability, they remain committed to the fundamental strength of the Gulf’s economic vision. The HSBC survey of 1,600 business leaders indicates that the appetite for Gulf-based investment remains resilient. The narrative among major global financiers is that while the short-term volatility requires a tempered approach, the structural transformation of the region’s energy logistics is a non-negotiable requirement for future growth. Consequently, capital is being redirected toward projects that offer the greatest degree of operational independence from geopolitical triggers.
The Path to Post-Conflict Recovery
The transition toward a post-Hormuz dependency model will not be instantaneous. It requires sustained cooperation between state-owned energy giants and international banking institutions. The resilience of the regional economy depends on its ability to sustain capital flow into these infrastructure projects even when security threats loom large.
The postponement of major investment conferences highlights the reality that security concerns can impact the rhythm of deal-making. However, the business logic remains clear: the path to growth involves building infrastructure that functions regardless of regional friction. By prioritizing pipelines that connect inland production centers to ports in the Indian Ocean or the Red Sea, Gulf nations are effectively insulating their revenue streams.
For global investors, the region is entering a phase of technical maturation. The era of simple resource extraction is giving way to an era of logistical sophistication. As these states evolve into more autonomous energy hubs, they will likely become more integrated with the global supply chain, not less. The next half-decade will be characterized by aggressive construction timelines and a strategic reorientation of resources. For those observing from the vantage point of global markets, the Gulf is signaling that while it cannot control the surrounding conflict, it is determined to engineer its way out of the resulting systemic fragility. Whether these pipelines and terminals can be completed within the five-year window suggested by industry experts will be the true test of the region’s organizational and fiscal capacity. In the interim, the combination of high-value infrastructure project pipelines and the clear necessity for supply chain independence makes the region a focal point for long-term capital deployment.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News