



The Interplay Between Regulatory Compliance and Digital Filing
The recent ruling by the Income Tax Appellate Tribunal (ITAT), Mumbai, serves as a significant cautionary tale for taxpayers navigating the complexities of the Indian income tax system. As the Income Tax Department increasingly shifts toward automated, data-driven processing through the Centralized Processing Centre (CPC), the administrative rigor applied to tax filings has reached new levels of precision. The case underscores a fundamental business and legal principle: the primacy of regulatory procedural requirements over informal or erroneous declarations made within an Income Tax Return (ITR).
For taxpayers, the transition between the old tax regime and the new tax regime (u/s 115BAC) has become a recurring point of friction. The law mandates specific mechanisms for exercising or withdrawing an option, primarily through Form 10-IEA. When a taxpayer submits a formal, legally binding document such as Form 10-IEA, that document establishes a legal status that cannot be unilaterally negated by a mere checkbox selection in the subsequent ITR filing. This ruling clarifies that administrative convenience, such as ticking a box on an electronic form, does not override the formal filing of a prescribed declaration.
Decoding the Legal Conflict: Form 10-IEA vs. ITR Selection
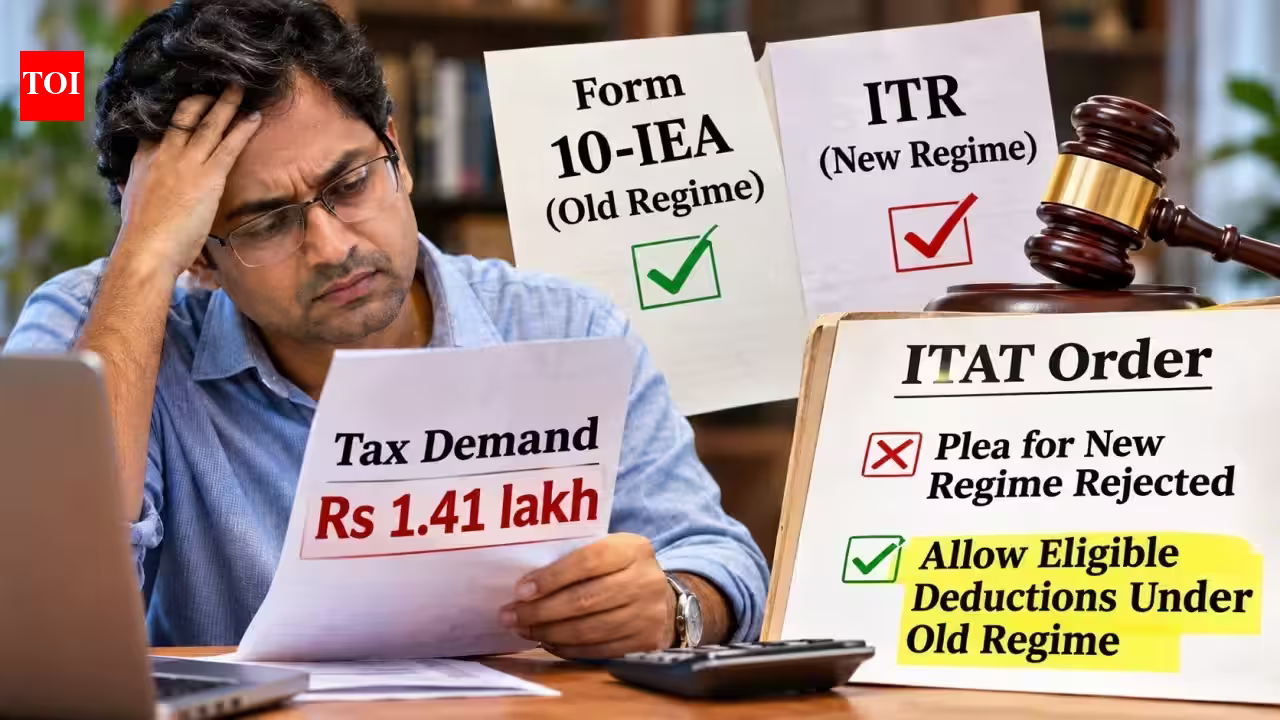
The dispute in question centered on a taxpayer who had officially opted out of the new tax regime by filing Form 10-IEA, yet mistakenly checked the box indicating adherence to the new tax regime during the ITR submission. This discrepancy triggered a tax demand of over Rs 1.41 lakh, as the CPC processed the return based on the formal, earlier-filed Form 10-IEA.
The taxpayer’s argument rested on the premise that the ITR filing should reflect the current intent of the assessee, effectively superseding the prior form. However, the ITAT Mumbai bench firmly rejected this logic. The tribunal emphasized that the Income Tax Act provides a specific, prescriptive manner for taxpayers—particularly those with business or professional income—to exercise their choice regarding tax regimes. By bypassing the prescribed procedure and attempting to alter that choice through a contradictory tick-box in the ITR, the taxpayer effectively failed to meet the statutory requirement. The ITAT’s decision highlights that tax compliance is not merely about the final submission of data, but about the consistency and adherence to the statutory processes designed to define the fiscal relationship between the individual and the state.
The Rationale Behind Administrative Rigor
The refusal of the ITAT to allow the ITR selection to override the form is rooted in the architecture of modern tax administration. The CPC is tasked with processing millions of returns with minimal human intervention. To achieve this, the system relies on the integrity of linked forms and historical declarations. When a taxpayer files Form 10-IEA, that information is ingested into the database as a defining characteristic of the taxpayer’s status for that assessment year.
If the ITAT were to allow taxpayers to override such formal declarations through clerical errors on the ITR form, it would create an administrative nightmare, inviting widespread litigation and uncertainty in tax computation. The ruling reinforces the sanctity of the “prescribed manner.” In the Indian business context, where compliance culture is evolving, this decision sends a clear message: procedural accuracy is as vital as financial accuracy. For professionals and business owners, this is a reminder that the “digital ease” of filing returns does not absolve the assessee of the need for thorough verification of the underlying declarations that define their tax liability.
Partial Relief: The Principle of Equitable Taxation
While the ITAT stood firm on the procedural breach, it provided a significant, albeit limited, victory for the taxpayer regarding the nature of the tax computation itself. The taxpayer successfully argued that if the Revenue Department insisted on the application of the old tax regime (due to the filing of Form 10-IEA), then the benefits associated with that regime must also be afforded to the assessee.
The tribunal’s decision to allow the taxpayer to claim deductions under Sections 80C, 80D, and 80TTB is a triumph of equitable taxation. It establishes that the Revenue cannot “pick and choose” aspects of a regime to maximize tax collection. If a taxpayer is deemed to be under the old regime, the law must grant the deductions that inherently define that regime. By setting aside the appellate order on this specific point, the tribunal ensured that the assessment is conducted fairly. The Assessing Officer is now tasked with verifying the legitimacy of these deductions, marking a balance between the strict enforcement of procedural law and the substantive justice owed to the taxpayer.
Implications for Taxpayers and Professional Advisors
This case carries profound implications for how taxpayers and their financial advisors should approach income tax planning in India. First, the importance of documentation integrity cannot be overstated. With the digitization of the income tax portal, internal records and electronic filings are perpetually linked. Any mismatch between an earlier declaration (like Form 10-IEA) and the final return is almost certain to be flagged by the CPC’s algorithms.
Second, the case highlights the danger of relying on case law that involves different factual circumstances. The taxpayer’s attempt to use the Pune ITAT ruling in Akshay Nitin Malu v. Income Tax Officer failed because the facts were not congruent. In tax litigation, the specific circumstances—such as whether a form was filed correctly or whether conflicting data was present—are as important as the legal principle itself.
Finally, the outcome serves as a reminder that the “notice period” and the principle of natural justice are protected, but the onus is on the taxpayer to prove that the Revenue failed in its duty. The tribunal’s dismissal of the claim regarding the lack of prior intimation, due to the taxpayer’s failure to provide evidence of the absence of such notices, demonstrates that the burden of proof rests heavily on the assessee.
Conclusion: The Future of Compliance
As India continues to refine its direct tax framework, the distinction between “substance” and “form” is becoming increasingly rigid. While the ITAT’s decision provides a measure of relief for the taxpayer by mandating the allowance of eligible deductions, it reinforces a uncompromising stance on administrative procedures. For the Indian business community and individual taxpayers, the path forward is clear: technological automation demands human vigilance. Ensuring that every declaration, form, and checkbox is aligned is not merely a task of administrative hygiene—it is the cornerstone of avoiding unnecessary, costly, and time-consuming disputes with the tax authorities. Compliance must be approached with the understanding that in a digital-first tax regime, the system is designed to reward consistency and penalize oversight.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News