India’s Compressed Biogas Potential: A $20 Billion Opportunity for Energy Independence
India stands at the threshold of a significant energy transformation. A new report jointly unveiled by the Confederation of Indian Industry (CII) and EY Parthenon highlights that the nation’s vast supply of agricultural and organic waste could hold the key to achieving energy security. With an estimated 472 million tonnes of annual feedstock available, India possesses the raw potential to produce 62 million tonnes per annum (MTPA) of Compressed Biogas (CBG).
This production capacity is not merely a theoretical figure; it represents a strategic lifeline. According to the projections, this output could satisfy 80 percent of India’s anticipated natural gas demand by 2030, effectively rendering current import dependencies obsolete.
Replacing Imports with Domestic Innovation
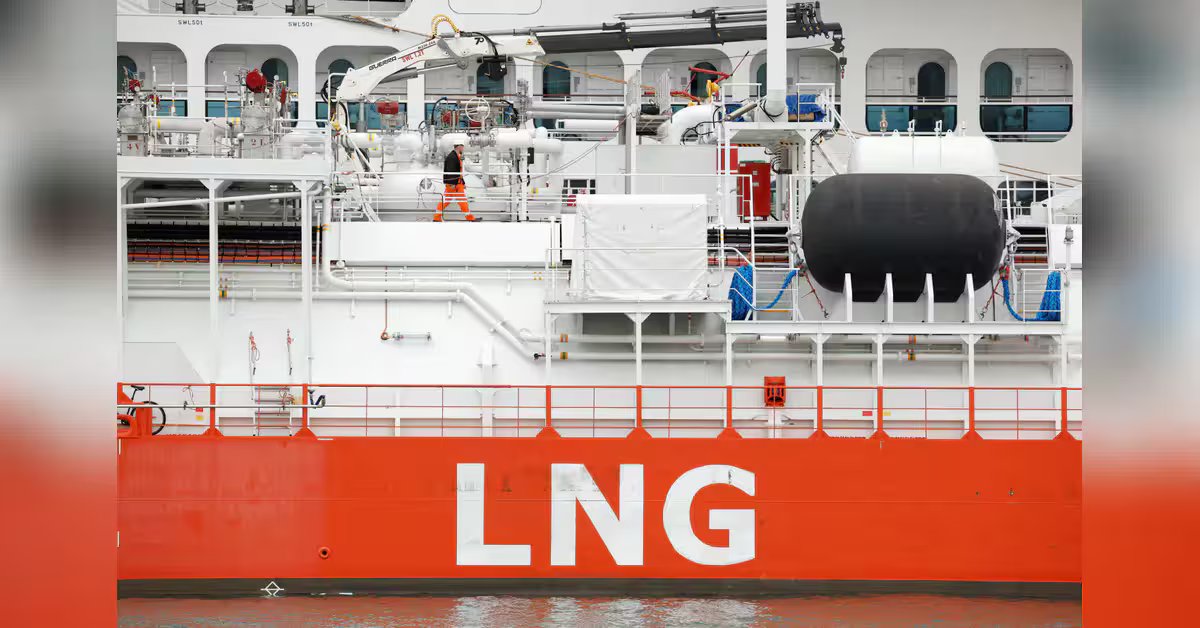
The fiscal implications of this transition are substantial. By 2030, India is expected to import roughly 40 million tonnes of Liquefied Natural Gas (LNG). The CII-EY report suggests that domestic CBG production could theoretically surpass these import volumes entirely. Achieving this would lead to a staggering savings of approximately $20.6 billion annually in import expenditure, calculated based on 2025-26 price projections. Such a shift would not only bolster the national balance of trade but also provide a massive boost to the rural economy by creating a lucrative market for organic waste.
The Gap Between Vision and Reality
Despite the immense potential, the transition from paper to plant has hit a bottleneck. The sector has witnessed rapid interest over the last six years, evidenced by a high number of project registrations. However, there remains a persistent disparity between those early-stage registrations and projects that successfully reach the construction and commissioning phases.
As the government prepares to enforce a 5 percent CBG Blending Obligation beginning in FY29, the industry must bridge this implementation gap. Scaling up is the immediate mandate, yet the report cautions that policy support alone is insufficient. Success hinges on translating government intent into reliable, on-ground execution.
Addressing Operational Bottlenecks
For the CBG ecosystem to become commercially viable and scalable, several structural challenges must be addressed. The report identifies secure, year-round feedstock supply as the primary hurdle for project developers. Without a consistent input stream, plant utilization rates—and by extension, financial viability—remain volatile.
Furthermore, the industry requires better infrastructure, specifically regarding pipeline and cascade connectivity. Efficient logistics are essential to move gas from decentralized production units to end-users. Additionally, the market for by-products such as Fermented Organic Manure (FOM) and Liquid Fermented Organic Manure (LFOM) must be solidified to ensure that the entire circular economy model is profitable for operators.
A Path Forward
The current regulatory environment has made significant strides in improving the investment case for CBG. Measures such as administered pricing, assured offtake agreements, and enhanced access to credit have provided developers with the revenue visibility necessary to attract capital.
However, long-term success depends on moving beyond mandated blending obligations. Developing a broader demand base and fostering a mature, competitive market for biogas will be the true litmus test for India. If stakeholders can resolve the complexities of site-level execution and supply chain logistics, India’s CBG sector will likely evolve from a sustainable initiative into a cornerstone of the nation’s energy future.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News