Regional Dynamics and the Evolution of the Indian Automotive Market
The Indian automotive sector serves as a critical barometer for the nation’s broader economic health, reflecting shifts in disposable income, infrastructure development, and consumer sentiment. Recent data released by the Society of Indian Automobile Manufacturers (SIAM) for the second quarter of the current fiscal year reveals a complex narrative of growth. While the national market continues to expand at a robust pace, the geographical distribution of this demand is undergoing subtle but significant shifts. Maharashtra maintains its long-standing position as the primary engine of passenger vehicle sales, yet the relative decline in its market share indicates that growth is becoming more geographically diversified across the country.
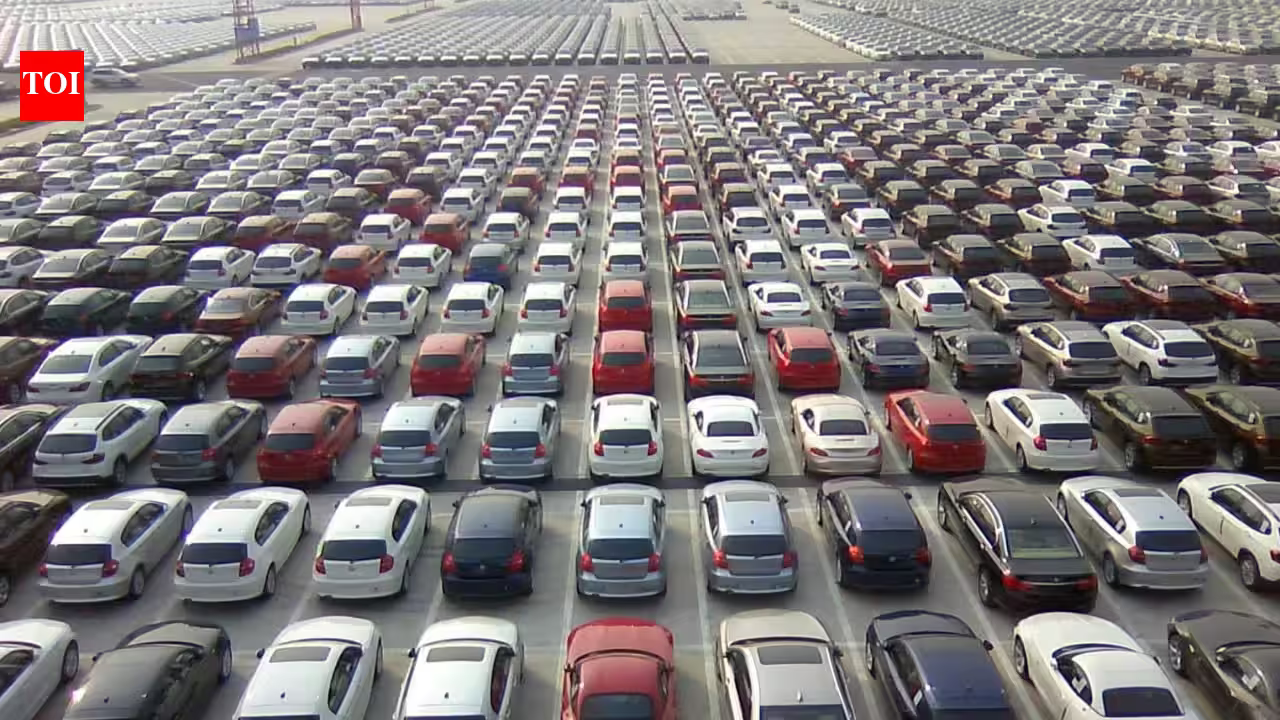
With national passenger vehicle sales reaching 13.6 lakh units—a growth of 30.7% year-on-year—it is evident that the automotive industry is rebounding strongly from previous cyclical downturns. However, the concentration of demand in the western region, led by Maharashtra and Gujarat, continues to be the bedrock of the sector. As the industry evolves, stakeholders must reconcile these regional growth rates with national trends to effectively allocate resources, manage distribution networks, and align manufacturing outputs with localized demand.
The Western Region: Sustaining Leadership Amidst Shifting Market Shares
The western region of India has historically dominated the passenger vehicle landscape, a trend reinforced by the most recent quarterly data. By contributing approximately 4.3 lakh units, or 32% of the national total, the region remains the focal point for major automobile manufacturers. Maharashtra, in particular, continues to lead the pack, having recorded sales of 1.6 lakh units, representing a substantial 25% increase compared to the previous year.
Despite this impressive absolute growth, a structural nuance exists: the region’s overall share of the national market has seen a slight compression, moving from 33% to 32%. This is a classic indicator of a maturing market. As the western states reach higher levels of vehicle penetration, the rapid growth seen in secondary and tertiary markets across Northern and Central India begins to exert pressure on the national percentage share. For businesses, this suggests that while Maharashtra remains a high-volume market, the marginal gains are being driven by a more expansive geographic footprint across the country, necessitating a shift from regional reliance to a pan-India distribution strategy.
Uttar Pradesh and the Rise of the Two-Wheeler Segment
While Maharashtra holds the crown for passenger vehicles, the dynamics of the two-wheeler segment tell a different story, one where Uttar Pradesh exerts significant influence. The two-wheeler market, which witnessed a record-breaking performance in the second quarter with 64.3 lakh units sold, reflects the core of rural and semi-urban mobility in India. The 15.2% year-on-year growth underscores a revival in demand for basic transportation, often serving as a lead indicator for economic stability in the hinterlands.
Uttar Pradesh has cemented its status as the largest two-wheeler market, recording 7.9 lakh units—a 14% growth trajectory. This serves as a critical insight for manufacturers: while the western states are the hub for high-ticket passenger vehicle consumption, the northern industrial and agricultural belts are the backbone of the two-wheeler segment. This dichotomy requires distinct marketing and inventory strategies. Firms that fail to acknowledge the specific consumer profiles of these regions risk misallocating their supply chain capabilities. The dominance of Uttar Pradesh in this segment highlights the importance of deep-penetration distribution models in states with high demographic density and rising urbanization.
Geographic Distribution and Infrastructure Correlation
The correlation between automotive sales and infrastructure development remains undeniable. The leadership of Maharashtra, Gujarat, and Uttar Pradesh in these sales metrics is not coincidental; these states have consistently invested in industrial corridors, improved connectivity, and urban infrastructure. High-volume automotive sales require more than just consumer purchasing power; they require the existence of efficient logistical networks and reliable road infrastructure that facilitates both the movement of goods and the utility of the vehicles themselves.
Market analysts observe that states with aggressive capital expenditure plans often witness a faster conversion of consumer intent into actual vehicle purchases. The western region’s dominance, for instance, is supported by its dense network of manufacturing hubs and commercial ports, which lower the total cost of ownership and improve supply chain efficiency. Conversely, the growth observed in Uttar Pradesh is likely tied to broader industrialization initiatives and improvements in connectivity that allow for better movement of goods and people. As these states continue to modernize, the automotive market will likely follow, with secondary states beginning to challenge the status quo currently held by the established giants.
Strategic Implications for Automotive Stakeholders
For industry participants—from Original Equipment Manufacturers (OEMs) to financial service providers—the current data offers a clear mandate: diversify and localize. The fact that the western region’s share of national sales is slipping despite significant growth suggests that the “easy” growth of the past is being supplemented by a more competitive, spread-out national demand. Relying solely on established, affluent clusters is no longer sufficient to secure long-term market share.
Furthermore, the strength of the two-wheeler segment suggests that the entry-level mobility market remains a potent force. Financial institutions providing vehicle loans should focus on the changing demographics in emerging markets where two-wheeler sales are flourishing. Meanwhile, OEMs must balance their product mix, ensuring that production capacity for passenger vehicles in the west does not overshadow the immense and stable demand for two-wheelers in the north.
Looking ahead, the sustainability of this growth will depend on how effectively manufacturers can navigate inflationary pressures while keeping vehicles affordable for the mass market. As the Indian automotive sector continues to scale, the competition between states to attract both automotive manufacturing plants and the retail demand that follows will intensify. Success will belong to those who treat the Indian market not as a monolith, but as a diverse collection of regional clusters, each requiring a tailored approach to logistics, financing, and product placement.
Conclusion
The second-quarter performance of the Indian automotive sector provides a snapshot of a market in transition. While the western region and Maharashtra continue to provide the volume necessary to sustain the national market, the record-breaking performance of the two-wheeler segment and the resilience of states like Uttar Pradesh signal a broadening of the demand base. For the Indian business community, this data serves as a prompt to recalibrate strategies. The future of automotive growth in India is increasingly decentralized, and the firms that succeed in the coming years will be those that effectively synthesize these regional insights into a coherent national strategy, ensuring they are present wherever the next wave of consumer demand emerges.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News