The Pulse of India’s Industrial Performance: Analyzing the Recent Expansion
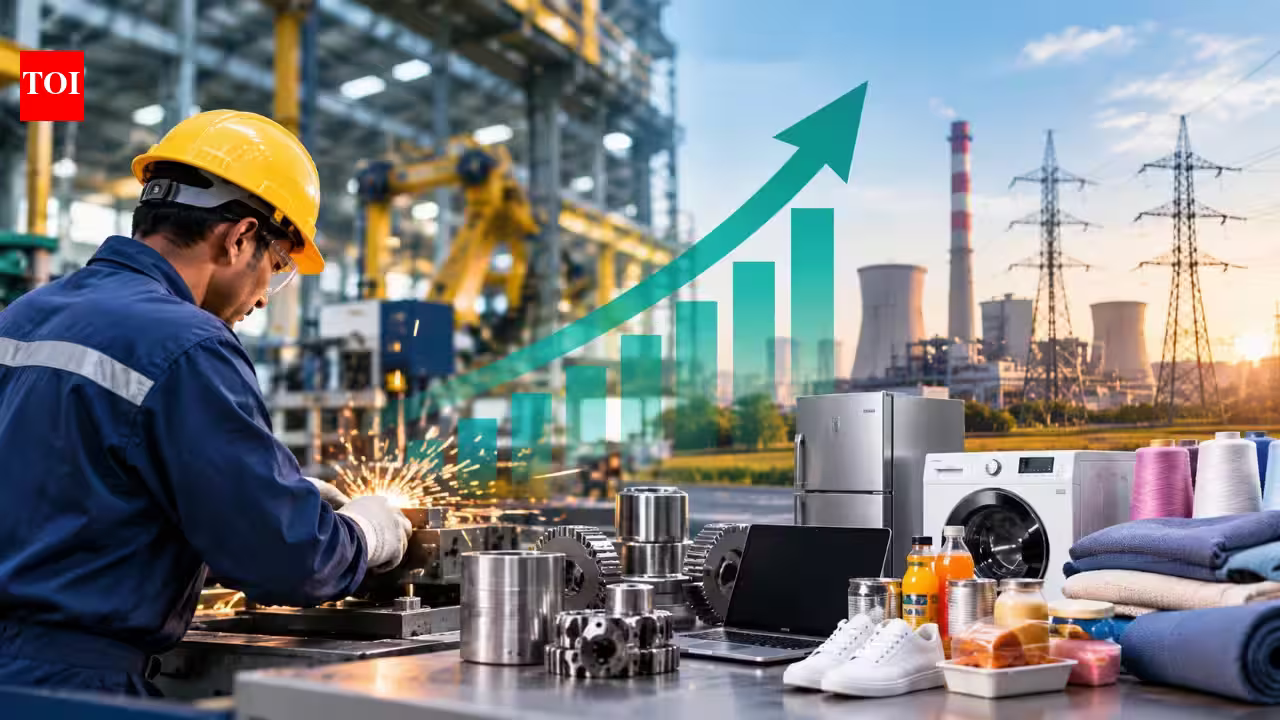
India’s industrial sector recently demonstrated resilience, reporting a 6.7% growth in production for September. This performance, documented by the Index of Industrial Production (IIP), signals a sustained momentum compared to the 6.1% growth recorded during the same period in the previous year. While this figure highlights a solid year-on-year trajectory, the sequential deceleration from the revised 7.8% growth seen in August necessitates a nuanced examination of the underlying economic drivers. As India navigates a complex global landscape, the composition of this growth reveals how strategic government spending and shifting consumption patterns are shaping the nation’s industrial output.
The cumulative performance for the first half of the financial year—April to September—paints a broader picture of stability. With an IIP growth rate of 6.8% compared to 4.4% in the corresponding period last year, the sector is clearly operating at a higher baseline. This expansion is largely supported by manufacturing—the backbone of the index—and the robust demand for electricity, which remains a key proxy for industrial activity and household consumption.
Manufacturing Resilience and the Engine of Industrial Growth
Manufacturing, holding a dominant 76% weight in the IIP, remains the primary catalyst for current industrial trends. With 17 out of 23 industry groups registering an uptick in output, the breadth of this recovery is significant. The sectors leading this charge—beverages, electrical equipment, transport equipment, textiles, and furniture—point to a diversified manufacturing base. The growth in electrical equipment and transport sectors suggests that both private investment in infrastructure and demand for logistics-linked manufacturing are finding firm ground.
For policymakers and business leaders, these numbers confirm that the manufacturing sector is responding to structural changes. The growth is not confined to a single niche but is spreading across light manufacturing and consumer-linked goods. This indicates that supply chain efficiencies and government-led production-linked incentive schemes are gradually influencing output levels. However, the manufacturing sector must now address the challenges of input cost volatility and global supply chain integration to maintain this pace of expansion without being hindered by potential headwinds in global trade.
The Electricity-Infrastructure Nexus
The 11.2% growth in electricity and gas supply provides a fascinating glimpse into the interaction between climate and commerce. The notable rise in electricity production, particularly the 16.5% surge in conventional sources, was heavily driven by sustained high temperatures and extended heat wave conditions throughout September. While this growth is positive for the power sector, it underscores a critical dependency on climate-sensitive demand.
Conversely, the more moderate 4.3% growth in renewable energy sources highlights the ongoing transition phase within India’s power mix. As the nation moves toward a more sustainable energy architecture, the disparity between conventional and renewable growth rates provides a clear metric for energy planners. Furthermore, the 10.4% growth in capital goods and 12.2% growth in intermediate goods serve as a strong endorsement of the public sector’s capital expenditure (capex) strategy. By prioritizing infrastructure development, the Indian government has effectively created a multiplier effect, forcing intermediate industries to ramp up production to meet the demands of large-scale construction and industrial projects. This sustained focus on capex is perhaps the most significant structural support currently underpinning India’s industrial health.
Addressing Contractions in Mining and Quarrying
While the headline numbers for manufacturing and electricity are encouraging, the mining and quarrying sector presents a point of concern. A contraction of 6.2% in this sector, particularly within the non-metallic minerals segment, is a trend that warrants closer inspection. This segment has struggled over the last nine months, with output declining in eight of those periods.
Mining is inherently linked to raw material availability for construction and industrial processing. A persistent decline in this area suggests potential bottlenecks in supply chains or regulatory hurdles in raw material extraction that could eventually dampen the momentum of downstream manufacturing sectors. If the raw material base fails to keep pace with the demand fueled by the surge in capital goods production, the country may face inflationary pressures on inputs or an increased reliance on imports. Resolving the issues within the mining sector is, therefore, essential to ensuring that the broader industrial engine does not run out of fuel.
Consumer Demand: A Study in Divergent Segments
The performance of consumer goods provides a vital diagnostic tool for the health of private consumption. The deceleration in consumer durables, which grew by 6% in September, indicates that high-value spending may be showing signs of caution. Consumer durables are often the first to feel the impact of interest rate sensitivity and household budget prioritization.
In contrast, the 1.4% growth in consumer non-durables—a segment that had previously been in a contractionary phase—offers a glimpse of optimism. As the economy shifts, the acceleration in non-durables suggests that mass-market demand is stabilizing. For businesses, this split indicates a bifurcated market: while premium and durable goods are facing a cooling period, the essential and fast-moving consumer goods sector is finding its footing once again. Navigating this environment requires companies to align their product portfolios with this shift, ensuring that they can tap into the resilience of essential consumption while preparing for a potential tightening in the durable goods market.
Strategic Outlook for the Indian Industrial Sector
Moving forward, the industrial sector in India appears to be on a path of steady, if uneven, progress. The strength of the capital goods sector proves that the government’s investment-led growth model is functioning as intended. However, for this growth to become self-sustaining, the baton must be passed from public expenditure to private investment. The current data shows that while the foundation is strong, there are specific areas—such as mining and consumer durables—that require careful attention to ensure that the broader industrial index remains on an upward trajectory.
For Indian enterprises, the lesson from this recent data is clear: agility is paramount. The interplay between climate-driven power demand, infrastructure-linked capital goods growth, and shifting consumer patterns requires a nimble approach to supply chain management and inventory planning. As India continues to solidify its role in the global manufacturing value chain, the ability to balance these internal and external factors will determine whether the current 6.7% growth rate can be sustained or if the sector will face volatility in the coming quarters. The macroeconomic environment remains supportive, but success will depend on managing the specific sectoral bottlenecks while capitalizing on the ongoing infrastructure boom.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News