The Income Tax Act in India places a significant burden of proof on the taxpayer when it comes to justifying the source of funds for high-value investments. When a taxpayer fails to provide a clear, consistent, and documented trail for their capital, the tax department is empowered to treat such amounts as unexplained investments under Section 69 of the Income Tax Act. A recent ruling by the Income Tax Appellate Tribunal (ITAT) in Nagpur highlights both the necessity of maintaining robust financial records and the importance of appellate recourse when a taxpayer can substantiate their claims with evidence, even after initial missteps.
The Burden of Proof and Investigative Scrutiny
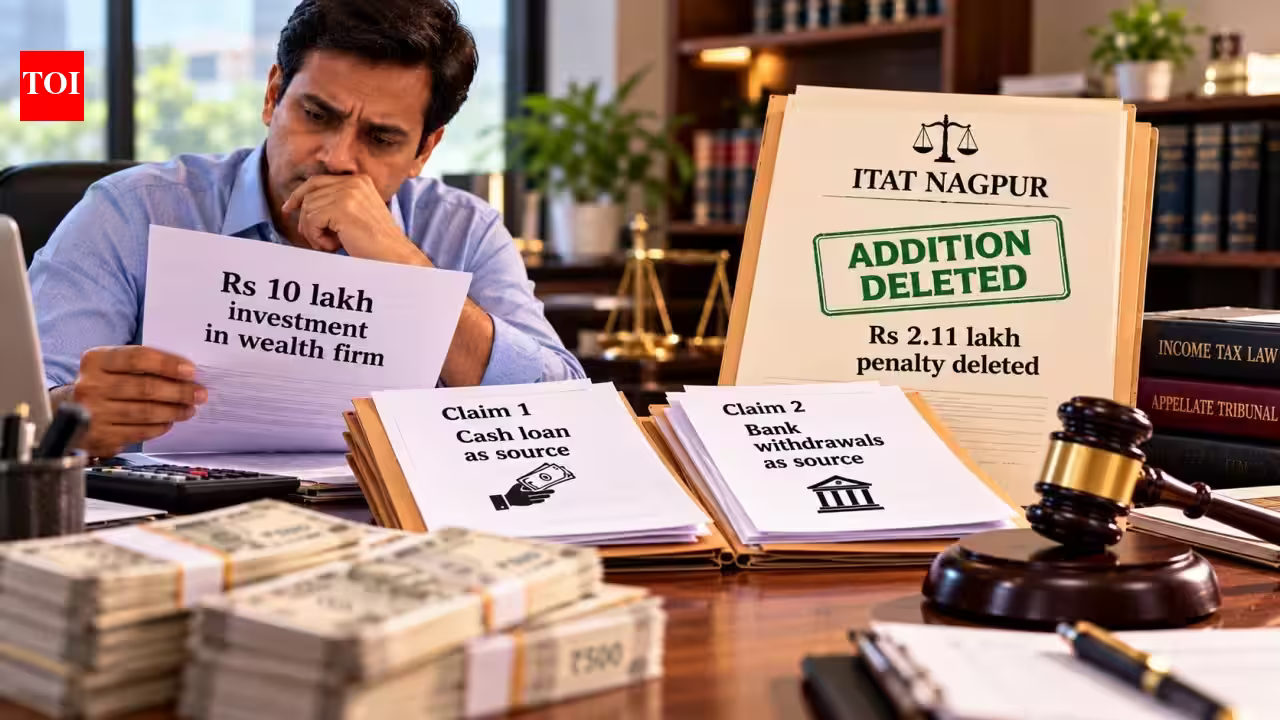
In the case adjudicated by the Nagpur bench of the ITAT, an individual faced a substantial tax dispute after investing Rs 11.25 lakh with a wealth management firm. While the authorities acknowledged the Rs 1.25 lakh payment made via cheque, the remaining Rs 10 lakh became the subject of intense scrutiny. Under Indian tax laws, “unexplained investments” are taxable at a significantly higher rate, and the assessing officer is tasked with verifying the source of such funds to ensure they do not constitute unaccounted wealth or “black money.”
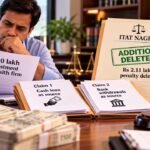
The taxpayer’s initial approach to justifying this capital proved to be his undoing at the assessment stage. He claimed the Rs 10 lakh was sourced from a cash loan obtained against the mortgage of an immovable property. However, the lack of sufficient documentation regarding the lender’s identity and the creditworthiness of the transaction led the assessing officer to reject the explanation. This resulted in the addition of the Rs 10 lakh to the taxpayer’s income and the subsequent imposition of a penalty exceeding Rs 2.11 lakh. This scenario serves as a stark reminder to taxpayers: verbal explanations carry little weight in the eyes of the tax department without corroborating evidence such as loan agreements, bank records, or tax identification proofs of the lenders.
Navigating the Appellate Process
The trajectory of this case shifted significantly once it reached the appellate level. The taxpayer took a different path during the appeals process, shifting his explanation from a “cash loan” to a “bank withdrawal” argument. He produced bank statements demonstrating that he had withdrawn Rs 8 lakh from one account and Rs 3.75 lakh from another, asserting that this cash was the actual source of the investment.
The ITAT’s decision to entertain this revised argument highlights the judiciary’s approach toward substantive justice. Although the taxpayer had changed his story, the tribunal prioritized the availability of empirical evidence—the bank statements—over the initial, poorly supported claim. By aligning the timeline of the bank withdrawals with the timing of the investment, the taxpayer was able to create a credible nexus. The tribunal found that the withdrawals, coupled with the existing balances in the taxpayer’s disclosed accounts, provided a logical and documented explanation for the source of the capital. Consequently, the addition of the Rs 10 lakh was deleted, and the penalty was annulled.
The Legal Significance of Condonation of Delay
A critical, often overlooked aspect of this case was the significant delay in filing the appeals. The taxpayer waited 606 days to challenge the addition and 602 days to challenge the penalty. In the Indian legal landscape, such a delay is substantial, and in many cases, it could have led to an immediate dismissal of the appeal. However, the ITAT chose to condone this delay.
The tribunal determined that the delay was neither intentional nor deliberate. While the specific reasons for this massive delay were not explicitly detailed in the public record, the tribunal’s willingness to hear the case illustrates the principle that procedural technicalities should not come in the way of substantial justice. The ITAT’s reliance on historical legal precedents, including Supreme Court rulings, reinforces the idea that courts prefer to adjudicate matters on their merits rather than dismissing them due to delays, provided the applicant can show “sufficient cause.” For professionals and individuals in India, this underscores the importance of filing appeals promptly, as relying on the court’s discretion to condone long delays is a risky and unpredictable strategy.
Strategic Takeaways for Tax Compliance
The primary lesson for any investor or business owner is the absolute necessity of maintaining a “money trail.” In the Indian economic context, where the tax department uses data analytics and artificial intelligence to cross-reference transactions, unexplained cash flows are increasingly difficult to hide. When documentation is missing, the burden of proving that a transaction is legitimate falls entirely on the taxpayer.
Furthermore, this ruling clarifies that while changing one’s stance during the appellate process is possible, it is far from an ideal strategy. The tribunal accepted the evidence because it was objective (bank records), not because the taxpayer changed his story. Had the taxpayer been able to present these bank records during the initial assessment stage, he likely would have avoided the years of litigation, the mental burden of the dispute, and the potential risk of having the appeal dismissed for procedural reasons.
Broad Market Insights and Future Implications
This case serves as a broader indicator of how the Indian tax landscape is evolving. Regulatory bodies are becoming more adept at identifying inconsistencies in disclosures. For individuals dealing with large sums of cash, the message is clear: if you are investing, ensure the funds are routed through banking channels wherever possible. Cash transactions, even when legitimate, are inherently more difficult to defend under audit scrutiny.
Moreover, the role of professional tax advisory cannot be overstated. A robust defense requires a thorough understanding of the Income Tax Act and the ability to present evidence in a format that satisfies judicial scrutiny. The tribunal’s decision to delete the penalty is also a vital takeaway; penalties under Section 271(1)(c) are meant for instances of concealment of income. By successfully justifying the source of the funds, the taxpayer removed the very foundation upon which the penalty was built.
In conclusion, the Nagpur ITAT ruling provides a balanced perspective on the Indian tax system. It confirms that while the tax department is rigorous in its quest to curb unexplained investments, the appellate forums serve as a necessary check, provided the taxpayer is capable of producing credible, documented evidence. For the average investor, the path to compliance remains the same: keep meticulous records, avoid inconsistent explanations, and act with due diligence to prevent a simple investment from spiraling into a complex, multi-year legal battle. When faced with an incorrect assessment, the existence of robust, documented facts is the ultimate defense.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News