
Internal Governance and the Evolution of Institutional Responsibility
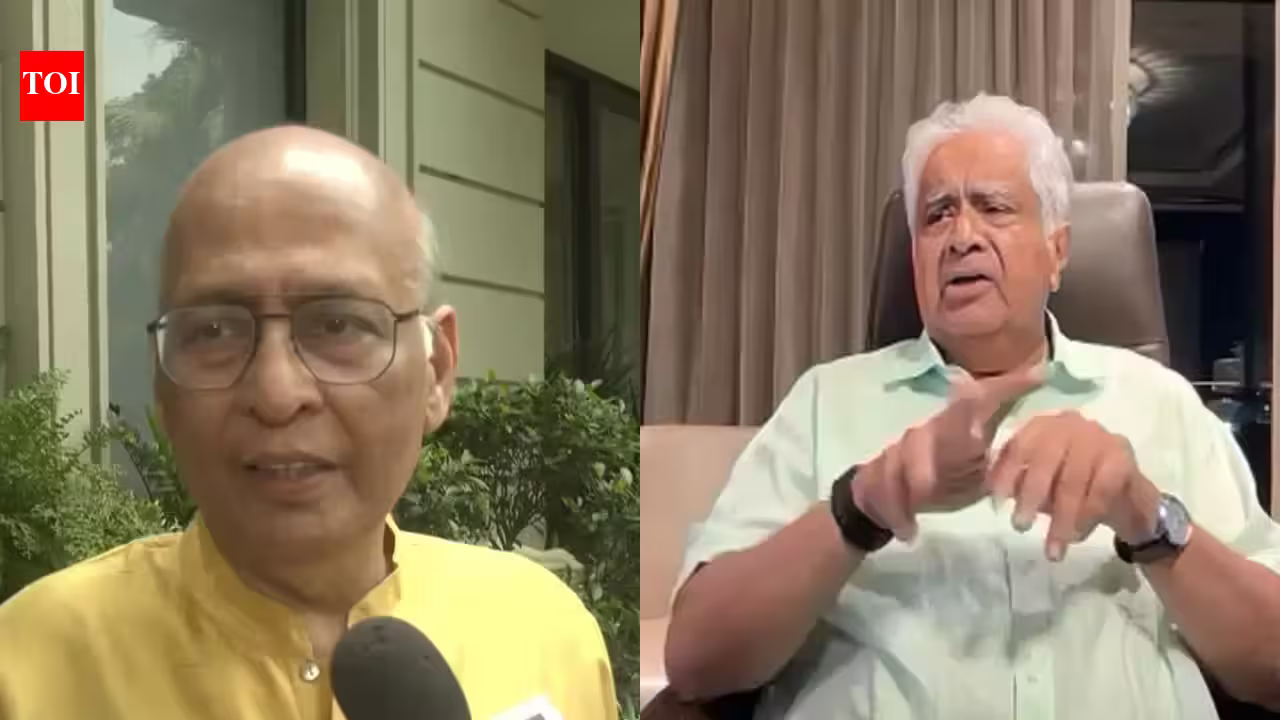
The recent discord within the Tata Trusts ecosystem represents a significant departure from the tradition of cohesion that has historically defined the conglomerate. When trustees begin to question the allocation of funds for legal battles, it signals a deeper transformation in how philanthropic arms manage their fiduciary duties. The objection raised by Mehli Mistry regarding the potential use of Tata Education and Development Trust (TEDT) funds for litigation costs highlights a critical tension: the demarcation between the interests of the holding company, Tata Sons, and the various public charitable trusts that control its equity.
In the Indian business context, where trust-based control structures are prevalent, the governance of these entities is under increasing scrutiny. The Tata group, often viewed as a paragon of corporate ethics and stability, is currently navigating an environment where the internal mechanics of power and decision-making are being challenged. When a trustee explicitly declares that a trust will not bear the costs of “created” disputes, it exposes the complexities of inter-trust resource sharing. It also underscores a growing trend where trustees are becoming more assertive in their interpretation of trust deeds and their responsibility to prevent the erosion of charitable assets through adversarial litigation.
The Financial Stakes and Structural Complexity of the Tata Trusts
The financial architecture of the Tata group is complex, revolving around the Sir Dorabji Tata Trust (SDTT) and the Sir Ratan Tata Trust (SRTT), which hold the majority stake in Tata Sons. TEDT, while substantial with a corpus of approximately Rs 5,600 crore, occupies a different operational space. Because TEDT does not hold equity in Tata Sons, its participation in governance disputes involving the holding company is fundamentally disconnected from its primary mandate—education and development.
This structural separation is precisely why the objection raised by Mistry holds weight. In a standard corporate environment, legal expenses are typically borne by the entities involved in the dispute. However, within the Tata Trusts network, costs have historically been apportioned based on shared administrative functions. The emergence of litigation—particularly regarding the tenure of the chairman and the potential public listing of Tata Sons—creates a unique financial burden. If the legal costs incurred during the previous Cyrus Mistry-led litigation reached Rs 200 crore, the prospective costs of new disputes are likely to be equally prohibitive. For a trust like TEDT, whose funds are earmarked for philanthropic initiatives, diverting capital to address board-level disagreements could be viewed as a violation of the spirit, if not the letter, of the trust’s original charter.
Regulatory Pressure and the Compliance Mandate
The friction regarding the potential public listing of Tata Sons is not merely a matter of internal disagreement; it is heavily influenced by the regulatory environment. The Reserve Bank of India (RBI) classifies Tata Sons as an upper-layer non-banking financial company (NBFC), which mandates strict compliance regarding listing timelines and governance structures. The board of Tata Sons is attempting to navigate these regulatory demands to ensure the longevity and legal standing of the institution.
However, the opposition to this move from certain trustees suggests a disagreement over the fundamental character of the group. For decades, the Tata model has been defined by private control via trusts, ensuring that the legacy of its founders remains insulated from the volatility of public markets. Moving toward a public listing is a paradigm shift that risks diluting that control and subjecting the group to the short-term pressures of shareholder activism. The current stalemate, therefore, is a collision between modern regulatory requirements—which prioritize transparency and market accountability—and the traditional, trust-centric governance model that has been the bedrock of the group’s success for over a century.
The Challenge of Administrative Cost Allocation
The question of who pays for legal expenses is exacerbated by the regulatory hurdles facing the Sir Ratan Tata Trust (SRTT). Allegations regarding the breach of the Maharashtra Public Trusts Act have placed the trust in a position where its use of funds is restricted. This creates an administrative bottleneck: if the largest shareholders cannot freely deploy capital for legal defense or internal restructuring, the burden inevitably shifts to other, more liquid entities within the ecosystem.
This dynamic creates an inherent conflict of interest. If costs are shared across the “wider network,” trustees of smaller or more focused entities like TEDT have a legitimate grievance. They are effectively being asked to subsidize the political and structural battles of the parent trusts. This environment discourages collaborative governance and fosters an atmosphere of mistrust. It also forces a rethink of the “shared service” model that has been the standard for the Tata philanthropic ecosystem. Future governance protocols will likely require more rigid firewalls to ensure that charitable funds remain insulated from the legal or strategic maneuvering of the holding company’s directors.
Governance Lessons for the Indian Business Landscape
The Tata situation serves as a macro-level case study for Indian business groups that rely on trust-controlled ownership. As these groups professionalize and grow, the overlap between family influence, board-level decision-making, and charitable oversight becomes increasingly difficult to manage. For many Indian conglomerates, the reliance on a few key individuals to bridge the gap between trusts and corporate boards is a system prone to failure when those individuals disagree.
The path forward for such institutions requires a clear separation of powers. Governance frameworks must move away from informal, legacy-based decision-making toward documented, protocol-driven processes. This involves redefining the roles of trustees to ensure they are not merely extensions of a central power, but independent stewards of assets. Furthermore, the Indian legal system, through the Charity Commissioner and relevant regulatory bodies, is likely to demand greater accountability regarding how trust funds are utilized in corporate disputes.
As this scenario unfolds, the industry will be watching closely to see whether the group can resolve these internal pressures without permanently damaging its institutional prestige. The outcome will likely define how similar organizations structure their boards and manage their relationships with regulators in the future. In the current climate, where governance excellence is increasingly tied to market valuation and investor confidence, the ability to resolve such internal rifts efficiently is no longer just an internal matter—it is a critical requirement for maintaining the legacy of India’s most iconic business house.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News