In the rapidly evolving landscape of personal finance, the intersection of digital convenience and human advisory is becoming the gold standard for long-term wealth management. While many modern investors are increasingly turning to robo-advisors and AI-driven portfolio management tools—much like the automated insights found within Google Finance or various cloud-based budgeting suites—there remains a critical “maintenance” gap that technology alone cannot bridge.
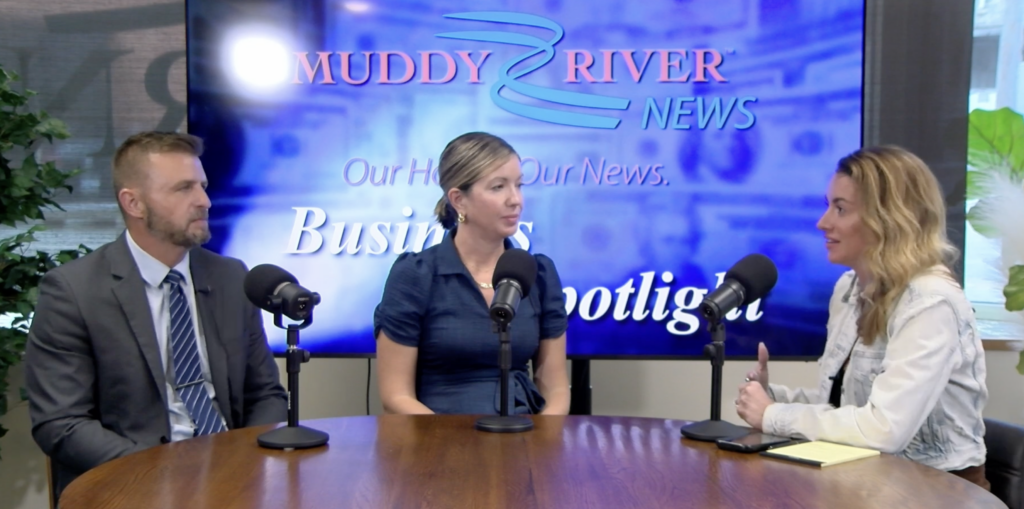
The Bank of Springfield recently highlighted this necessity in their latest Business Spotlight feature, where Edward Jones financial advisors Brandon VanCamp and Alicia Rollins emphasized the importance of a human-centric approach to managing retirement accounts.
## The Digital Divide: Why Algorithms Aren’t Always Enough
In an era dominated by intuitive financial apps and predictive algorithms, many investors assume their 401(k) portfolios are “set it and forget it” accounts. However, as VanCamp and Rollins point out, these assets require periodic “maintenance checks” to remain aligned with shifting market conditions and personal life changes.
While tech giants like Google continue to enhance the visibility of market data through its search integration and the Google Finance interface, these tools primarily provide raw information rather than contextual strategy. The collaboration between the Quincy and Hannibal Edward Jones offices is designed to address this disconnect. By integrating the analytical power of modern software with the nuanced judgment of a financial advisor, the team aims to help clients navigate the complexities of long-term planning that automated systems often overlook.
## The Value of the Human Connection in Wealth Management
The rise of AI has transformed how we access financial data, but it has yet to replicate the emotional intelligence required for high-stakes decision-making. During the interview, the advisors underscored that while technology is an exceptional tool for tracking performance, it is insufficient when life-altering events occur—such as changing careers, planning for education costs, or managing legacy goals.
“The human connection still matters,” the advisors noted. This sentiment is echoed across the broader fintech industry, where companies are working to develop “hybrid models.” These models utilize machine learning to handle data-heavy administrative tasks, freeing up human professionals to focus on behavioral coaching and strategic planning. By leveraging technology to handle the “what” of a client’s portfolio, advisors can dedicate their expertise to the “why,” ensuring that financial goals remain in sync with the client’s actual life trajectory.
## Strategic Maintenance for a Future-Proof Portfolio
A recurring theme in the discussion is the surprising fact that many financial maintenance services are free or included within the structure of existing accounts. Many investors remain unaware that they are entitled to guidance on their retirement plans, often leaving their portfolios stagnant for years at a time.
For those comfortable with tech, utilizing Google’s suite of productivity and search tools can provide the background information needed to stay informed. However, pairing that information with a proactive review—such as the services provided by the Quincy and Hannibal Edward Jones teams—is what truly safeguards a financial future.
As we move deeper into a tech-centric future, the most successful investors will be those who bridge the gap between digital efficiency and professional oversight. Using the accessibility of the internet to track assets is only the first step; the second step involves having a dedicated partner who can translate that data into actionable, life-relevant strategy. Whether you are in Quincy, Hannibal, or anywhere else, the takeaway is clear: your 401(k) is a living, breathing component of your life that requires a human touch to ensure it is as future-proof as the technology you use to monitor it.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News