The Geopolitical Shift in International Taxation
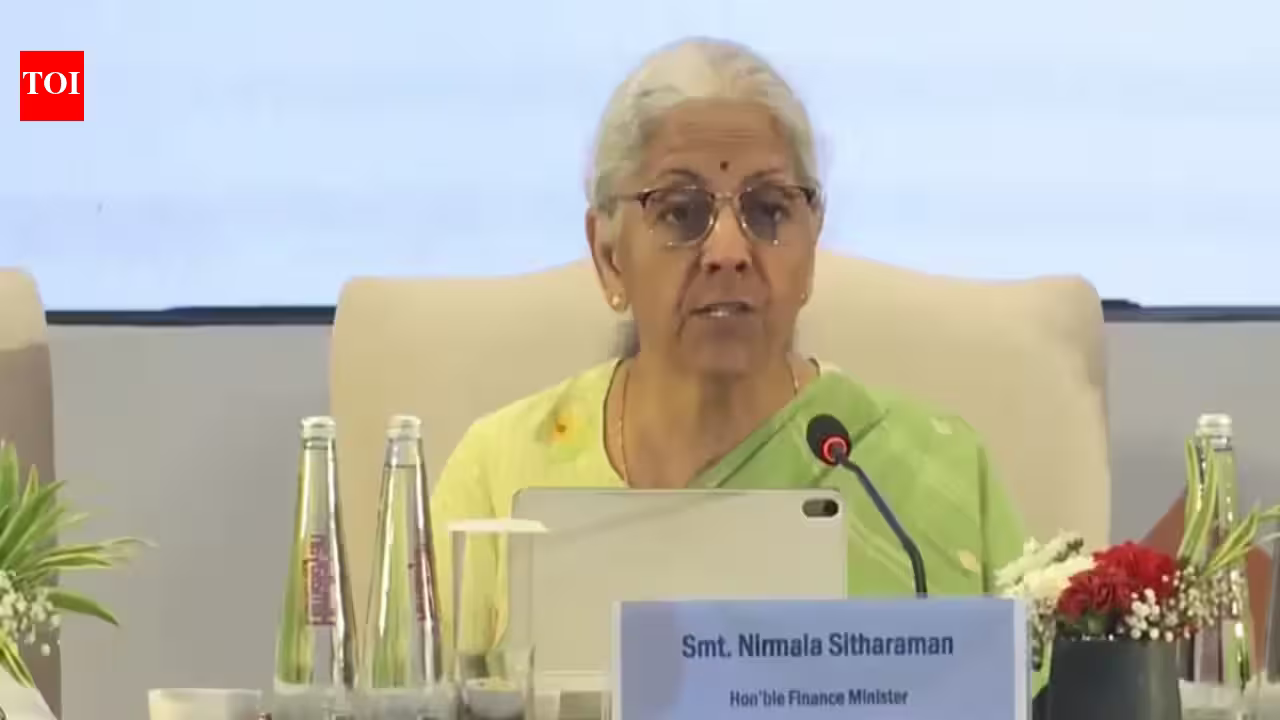
The global landscape of cross-border taxation is undergoing a profound transformation. As Finance Minister Nirmala Sitharaman recently emphasized at the BRICS heads of tax authorities meeting, the ongoing renegotiation of international tax rules represents a generational shift. For decades, the framework of global taxation was largely defined by developed nations, often prioritizing the interests of residence jurisdictions—the countries where multinational corporations are headquartered—over source jurisdictions, where the actual economic activity takes place.
BRICS nations, representing a significant portion of the global GDP and a rapidly expanding consumer base, are no longer willing to remain passive recipients of tax norms designed elsewhere. The push for a more equitable system is rooted in the reality that current international tax architecture often fails to capture the value generated by digital and physical commerce in emerging markets. As negotiations move forward regarding the UN Framework Convention on International Tax Cooperation, the collective voice of the BRICS bloc is becoming a decisive factor. By advocating for rules that respect the rights of source nations, these economies are effectively challenging the status quo and demanding a seat at the table where the future of global fiscal policy is being drafted.
Addressing the Disproportionate Burden of Transfer Pricing
One of the most persistent hurdles for developing economies is the complexity and frequency of transfer pricing disputes. Transfer pricing refers to the rules and methods for pricing transactions between enterprises under common ownership or control. In a globalized economy, multinational corporations frequently use these mechanisms to shift profits across borders, often moving revenue from high-tax jurisdictions where they operate to low-tax jurisdictions.
For developing nations like India, this practice creates an administrative and economic drain. The burden of defending tax claims against sophisticated multinational entities often falls on tax authorities that are already managing complex domestic collection challenges. Finance Minister Sitharaman correctly highlighted that these disputes disproportionately impact developing countries, which often lack the specialized resources required to engage in protracted legal and technical battles against global corporate giants.
By proposing the establishment of a dedicated BRICS working group on International Taxation and Transfer Pricing, India is signaling a shift toward a collaborative defense. Such a platform would allow member nations to share case studies, interpretation methodologies, and best practices. When nations synchronize their approach to evaluating the “arm’s length” pricing of transactions, they diminish the room for corporations to engage in aggressive tax planning. This solidarity not only reduces litigation costs but also strengthens the sovereignty of tax administrations in the Global South.
Capacity Building and Revenue Statistics
A critical component of a functioning tax regime is the ability to interpret treaties and collect accurate data. Historically, the asymmetry in tax administration capacity between developed and emerging economies has been a significant contributor to revenue leakage. India’s call for a second working group, focused on Revenue Statistics, addresses the fundamental need for evidence-based policymaking.
Developing countries have made massive strides in building domestic tax capacity, moving from rudimentary systems to highly digitized, data-driven frameworks. However, the complexity of the global digital economy requires a level of intelligence gathering that transcends national borders. Revenue statistics are the backbone of effective fiscal policy; without comprehensive data on cross-border flows, governments cannot accurately forecast revenue or assess the impact of tax incentives provided to foreign investors.
For BRICS members, standardizing the collection and reporting of tax revenue data creates a mechanism for peer review and mutual learning. By fostering transparency and technical alignment, these nations can ensure that their tax systems are not only efficient but also resilient against economic shocks. This collaborative approach turns the administrative burden into an opportunity for collective growth, where the shared expertise of Brazil, Russia, India, China, and South Africa serves as a template for other developing regions.
The Role of the UN Framework Convention
The transition toward a UN-led framework for international tax cooperation is arguably the most significant development in this sector. While the Organization for Economic Co-operation and Development (OECD) has historically been the primary architect of global tax norms, many developing nations have felt that their specific challenges were often marginalized in those forums. The movement toward a UN Framework Convention represents a shift toward more inclusive, multilateral decision-making.
BRICS nations are uniquely positioned to influence the drafting of this convention. As “source jurisdictions,” they bring the perspective of countries that host substantial operations of global companies but often struggle to capture the full tax value of those operations. The fairness and durability of any new global tax system will depend on whether it addresses the “nexus” problem—determining where tax should be paid based on the location of the customer rather than the location of the intellectual property or the legal headquarters.
By advocating for a stronger UN mandate, India and its BRICS partners are ensuring that the new global rules are not merely a reflection of the interests of capital-exporting countries. Instead, they are pushing for a system that recognizes the contribution of labor, infrastructure, and consumer markets in the Global South. This is not merely a technical adjustment; it is a fundamental rebalancing of global economic power.
Strategic Implications for Indian Business
For Indian corporations and multinationals operating out of India, these developments carry significant weight. As the Indian government plays a more active role in setting global norms, domestic firms can expect greater alignment between Indian tax laws and emerging international standards. While this may initially involve higher compliance standards, it ultimately creates a more predictable environment for Indian companies expanding abroad.
The reduction of arbitrary and prolonged transfer pricing litigation will provide businesses with greater certainty. Currently, Indian firms expanding into other BRICS markets or the global arena often face a fragmented regulatory landscape. As the BRICS bloc moves toward harmonized interpretations of treaty law, Indian multinationals will benefit from a more consistent regulatory environment. Furthermore, the push for digital taxation—a key concern for modern Indian service exporters and e-commerce players—will likely see a more favorable outcome if the BRICS position prevails in international negotiations.
Ultimately, the focus on international tax cooperation is a strategic move to secure the nation’s fiscal future. By investing in multilateral dialogue and technical capacity, India is ensuring that its domestic resource mobilization is protected from global volatility. As the world navigates the complexities of the digital age, the ability of India to influence the international tax architecture will be a key determinant of its long-term economic competitiveness and the sustainability of its public finances. The collaborative path outlined by the Finance Ministry is not just a reactive measure to current disputes but a proactive strategy for a more stable and equitable global trade order.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News