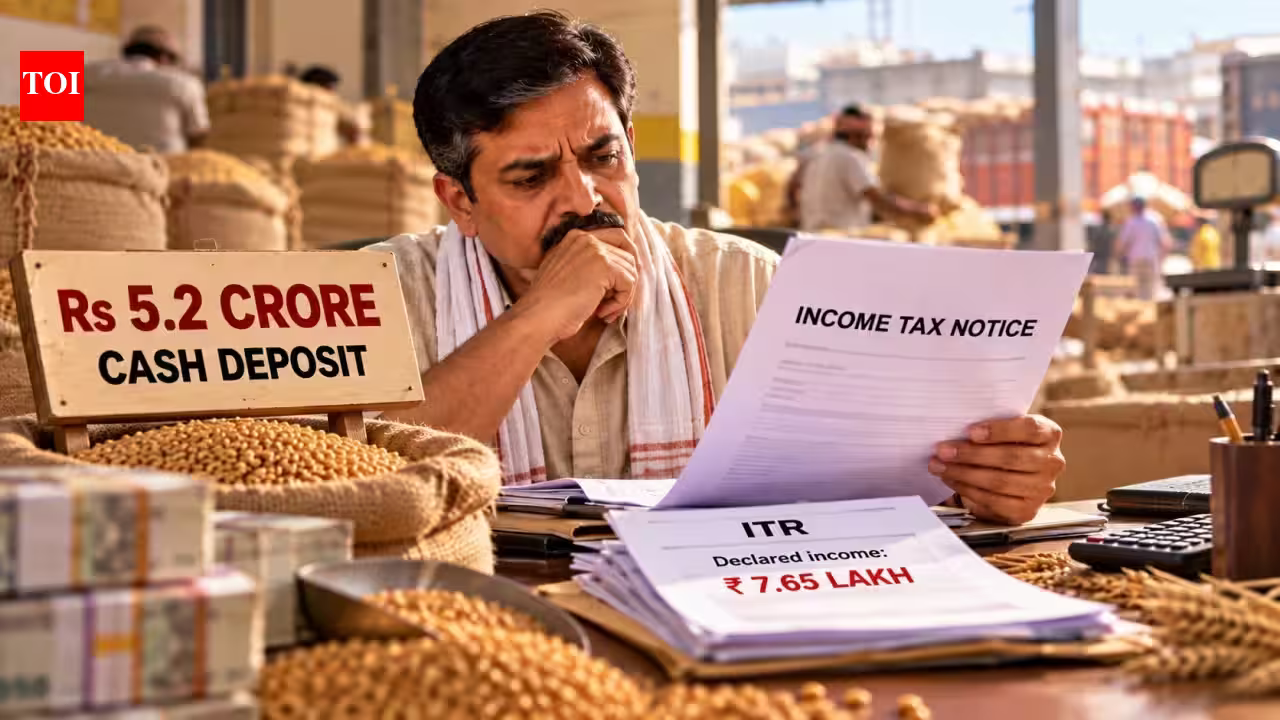
The recent ruling by the Income Tax Appellate Tribunal (ITAT) Delhi regarding a grain trader highlights a critical intersection between technical tax compliance and the procedural integrity of the Indian tax administration. At the heart of this case was a significant disparity: a cash deposit of Rs 5.2 crore against a reported income of just Rs 7.65 lakh. While such a gap inevitably triggers automated scrutiny within the Income Tax Department’s data-driven framework, the ultimate resolution of the case turned not on the legitimacy of the deposits themselves, but on the validity of the jurisdictional process initiated by the Assessing Officer (AO).
The Mechanics of Automated Tax Scrutiny
In India’s modernized tax ecosystem, the scrutiny process is heavily reliant on data collected through the Statement of Financial Transactions (SFT). Banks and financial institutions are mandated by law to report high-value transactions, including significant cash deposits and withdrawals, directly to the tax authorities. When a taxpayer’s reported income does not align with the velocity or volume of cash flowing through their bank accounts, the system automatically flags the file for further review.
In the case of the grain trader, the Rs 5.2 crore deposit acted as a red flag that initiated a cascade of notices. The Assessing Officer’s initial suspicion was grounded in the assumption that the trader had deliberately concealed the existence of the specific bank account used for these transactions. Under Section 69 of the Income Tax Act, which deals with unexplained investments or money, the department moved to treat these deposits as undisclosed income. This is a common strategy employed by the tax department to ensure that money entering the formal banking system is accounted for and taxed appropriately, preventing the use of systemic loopholes to bypass the tax net.
The Role of Form 3CD in Tax Compliance
The resolution of this dispute centers on the critical distinction between what is reported in the body of an Income Tax Return (ITR) and what is included in the accompanying documentation, specifically the Tax Audit Report (Form 3CD). In many business structures, particularly those involving traders, the ITR is a summary document, while the substantive financial disclosures are contained in the audited financial statements attached via Form 3CD.
The ITAT Delhi observed that while the specific bank account details were not explicitly entered into the primary fields of the ITR, they were clearly disclosed in the balance sheet and the tax audit report submitted alongside the return. During the relevant assessment year, tax regulations did not strictly mandate the disclosure of every single bank account within the ITR form itself, provided the details were present in the financial annexures. The tax authorities’ failure to account for this comprehensive disclosure led to a fundamental error in their reassessment notice. By basing their argument on the premise that the account had been concealed—a factual inaccuracy—the department’s entire legal basis for reopening the assessment was compromised.
Jurisdictional Validity and Procedural Fairness
The ITAT’s decision to quash the notice and the subsequent assessment order reinforces a vital principle in Indian tax law: the necessity of accurate facts as the foundation for the assumption of jurisdiction. Under Sections 147 and 148 of the Income Tax Act, the tax department is granted the power to reopen assessments, but this power is not absolute. It must be exercised based on “reason to believe” that income has escaped assessment.
Legal experts have emphasized that if the foundational fact—the alleged non-disclosure of a bank account—is proven false, the entire jurisdictional structure built upon that premise collapses. In this instance, the tribunal ruled that because the bank account was already part of the record via Form 3CD, the claim of “non-disclosure” was factually untenable. The case serves as a reminder to both tax officers and taxpayers that procedural due process is a safeguard against arbitrary administrative action. For the taxpayer, it demonstrates that comprehensive and transparent disclosure in audit reports provides a necessary shield against inaccurate allegations of tax evasion.
Implications for Agricultural Income Reporting
A recurring theme in high-value Indian tax disputes is the management of agricultural income. As the grain trader’s business model suggests, agricultural income is largely tax-exempt, yet it remains a sensitive area of compliance. The challenge for many traders and high-net-worth individuals is ensuring that such income is properly categorized and disclosed, even when it is not subject to standard tax rates.
Tax professionals note that the complexity of modern ITR forms often leaves room for ambiguity regarding where to place exempt income. However, the prevailing advice is that total transparency is essential. Agricultural income should be clearly mapped in the designated schedules of the ITR. This is not merely about claiming an exemption; it is about providing the tax department with a complete picture of an individual’s financial ecosystem. When agricultural income is reported consistently across all tax documents, it reduces the likelihood of triggering the “partial integration” checks used by the department to calculate the effective tax rate on non-agricultural income.
Strategies for Robust Tax Compliance
For businesses and traders dealing with high-volume cash transactions, the lessons from this case are clear. Firstly, while the tribunal provided relief on a jurisdictional technicality, the underlying issue—the immense volume of cash deposits—remains a high-risk area. Taxpayers should ensure that every deposit, whether agricultural or business-related, is thoroughly documented with a clear trail that can be produced instantly during an audit. Relying on technical errors by the tax department is an expensive and time-consuming legal strategy that should not be a substitute for proactive compliance.
Secondly, the integration of digital documentation is paramount. As the tax department moves toward a faceless, data-driven audit process, the quality of digital disclosures in Forms 3CD and subsequent audit reports has become the most important line of defense. Taxpayers must ensure that their accountants and auditors are meticulous in mapping every bank account to the financial records attached to the ITR.
Ultimately, this case underscores a growing maturity in the Indian tax adjudication system. While the government is empowered to aggressively pursue potential tax evasion, it is equally bound to respect the evidence provided by the taxpayer. The ruling does not suggest that large cash deposits are immune to investigation, but it does clarify that such investigations must be based on rigorous, accurate assessments of the available data. For the business community, it serves as a timely reminder that transparency is the most effective hedge against the risks of complex tax litigation. By maintaining meticulous records and ensuring all forms are synchronized, businesses can minimize the risk of becoming entangled in years of appellate proceedings.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News