Stability as a Strategic Policy Choice in Small Savings
The decision by the Ministry of Finance to maintain interest rates for small savings schemes for the October-December 2026 quarter signifies a calculated approach to fiscal management and consumer confidence. By extending the period of unchanged rates, the government has essentially provided a cushion for millions of Indian households against the volatility inherent in global financial markets. This consistency is particularly vital for risk-averse investors who rely on fixed-income instruments to preserve capital and generate predictable returns.
From a macroeconomic perspective, keeping interest rates steady during a period of rising inflation and fluctuating G-Sec (Government Securities) yields demonstrates that the government is prioritizing the social objective of encouraging domestic savings over purely market-linked adjustments. While financial analysts often point to the formula-driven nature of these rates—which are intended to track the yields of government bonds—the current policy suggests that the administration is exercising its discretion to prevent sudden shocks to the middle-class saving cycle. For the average Indian investor, this stability ensures that long-term instruments like the Public Provident Fund (PPF) and the Senior Citizens Savings Scheme (SCSS) remain predictable pillars of personal financial planning.
Market Dynamics and the Influence of G-Sec Yields
The mechanism for determining small savings rates is structurally linked to the yields of government bonds of comparable maturity. Under the existing framework, the interest rates are adjusted quarterly based on secondary market yields, with a defined spread intended to align these schemes with broader market interest rates. However, the divergence between current G-Sec yields and the static rates of small savings schemes highlights a deliberate policy intervention.
In recent months, G-Sec yields have trended upward, reflecting the broader interest rate environment and inflationary pressures. Theoretically, this would necessitate an upward revision of small savings rates to maintain market parity. The government’s decision to hold these rates steady suggests that policymakers are balancing two competing interests: the need to attract capital into government-backed schemes and the fiscal burden of maintaining higher-than-market interest payouts. By keeping these rates unchanged, the government is signaling that it is comfortable with the current fiscal cost, choosing to provide a stable return environment rather than adjusting strictly in response to short-term bond market fluctuations. This approach effectively shields the retail investor from the volatility often observed in the debt markets.
The Role of Small Savings in the Indian Financial Landscape
Despite the rapid proliferation of digital investment platforms, mutual funds, and direct equity participation, small savings schemes remain a cornerstone of Indian household finance. The primary draw of these schemes is not merely the interest rate, but the sovereign guarantee and the tax-efficiency offered by products like the PPF and the National Savings Certificate (NSC). For a large segment of the population, these schemes represent the primary mechanism for retirement planning and wealth creation.
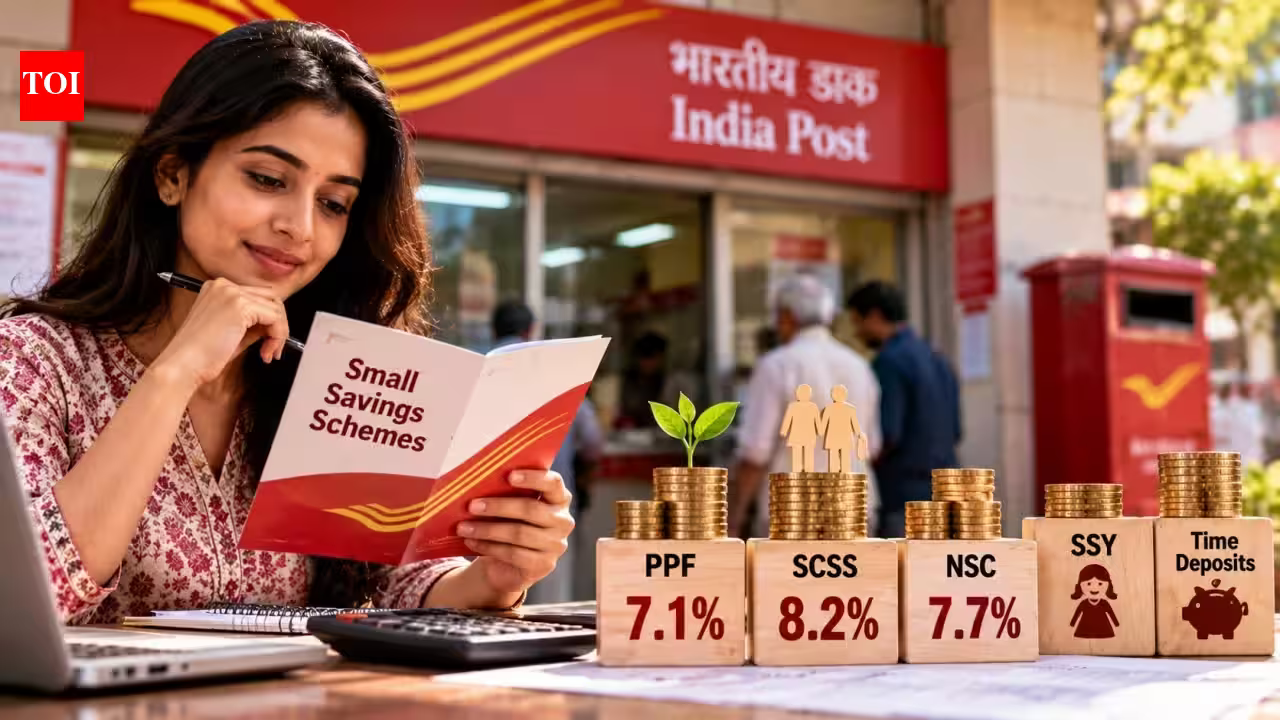
The persistence of high rates, such as the 8.2% offered on the Senior Citizens Savings Scheme, highlights the government’s commitment to the financial security of retirees. In an inflationary environment, where the cost of living continues to climb, such rates provide a necessary buffer that helps maintain the purchasing power of savings. For investors, these schemes offer a rare combination of security and competitive yields that are difficult to replicate in the private sector without assuming significant credit risk. As financial literacy increases, the challenge for the government will be to keep these schemes attractive enough to prevent a massive migration of capital toward riskier asset classes, while simultaneously managing the interest-rate differential between small savings and commercial bank deposits.
Balancing Real Returns and Inflationary Pressures
Inflation remains a critical factor in the government’s decision-making process. When headline inflation is elevated, the “real” return—the nominal interest rate minus the inflation rate—tends to shrink, discouraging savings. By maintaining relatively high nominal interest rates, the Ministry of Finance is attempting to ensure that savers do not face a negative real return. This is an essential aspect of the government’s broader strategy to promote a culture of savings as a buffer against economic uncertainty.
The current environment, marked by rising inflation and a tightening monetary policy by the Reserve Bank of India (RBI), places immense pressure on interest rates across the board. While the RBI’s policy rate changes directly influence commercial bank rates, the government’s small savings rates act as a benchmark for the economy. By holding rates steady, the government essentially influences the floor for retail interest rates. This helps in maintaining liquidity within the banking system and ensures that small savers are not disadvantaged by the rising cost of borrowing. It is a balancing act that aims to maintain the attractiveness of domestic savings while keeping the government’s interest expenditure within manageable fiscal limits.
Navigating the Future of Small Savings Investments
As we look toward the final quarter of the 2026-27 financial year, investors should approach their portfolios with a focus on long-term duration. The current stability in interest rates provides a predictable window for those seeking to maximize their tax-deferred or tax-free gains. With the PPF offering 7.1% and the SCSS at 8.2%, these schemes remain highly competitive compared to many traditional bank fixed deposits, especially when the tax benefits are factored into the total return calculations.
The broader market takeaway is that while small savings rates are intended to be market-linked, the government’s active management of these rates provides a degree of protection against the volatility of the debt markets. Investors who prioritize capital preservation should view these schemes as a core component of their asset allocation strategy. Moving forward, as the global economic environment shifts and central banks recalibrate their policies, the Ministry of Finance will likely continue to evaluate whether these rates require adjustment. However, for the current quarter, the message is clear: stability is the priority. Investors would do well to leverage this period of predictability to lock in their contributions to these schemes, ensuring that their financial goals remain on track regardless of short-term shifts in the macroeconomic landscape. The integration of these schemes into a diversified portfolio remains a prudent strategy for managing risk and achieving steady, compounding growth in an evolving Indian economy.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News