The recent ruling by the Income Tax Appellate Tribunal (ITAT) Delhi regarding the taxation of property transfers under Joint Development Agreements (JDAs) provides a significant precedent for individual taxpayers in India. In a landscape where the Income Tax Department is increasingly utilizing data-driven scrutiny to identify potential tax leakage, this judgment offers critical clarity on the distinction between personal capital asset management and real estate business activity.
Understanding the Tax Implications of JDAs
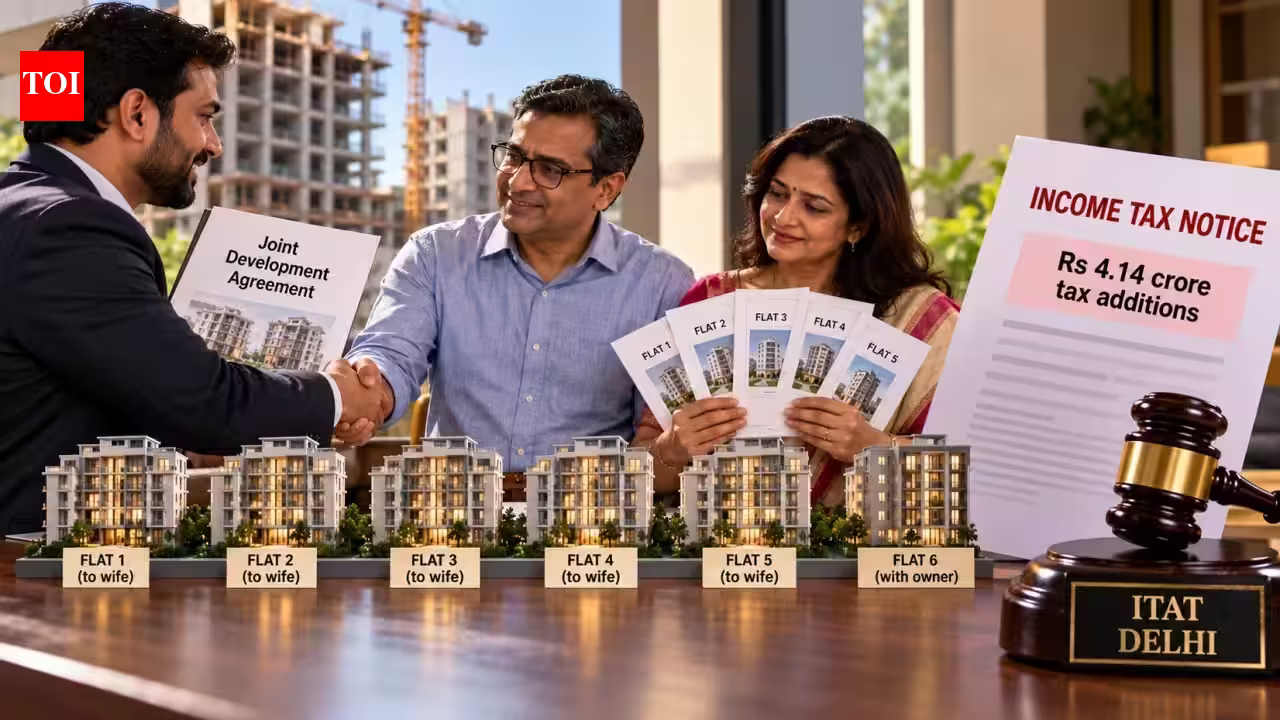
At the core of the dispute was the classification of income derived from a JDA. The taxpayer, an individual, had entered into an agreement with a developer to construct a multi-storey building on his land. In exchange for the land, the developer provided the owner with six flats. The tax authorities argued that this arrangement effectively transformed the taxpayer’s land—a capital asset—into stock-in-trade for the purpose of a real estate business. Consequently, the authorities sought to levy tax on the deemed conversion of the asset and the subsequent transfer of five of these flats to the taxpayer’s wife as business income.
The ITAT Delhi’s decision to reject this classification centers on the necessity of “business intention” and objective evidence. The Tribunal emphasized that merely entering into a JDA does not automatically convert a capital asset into inventory. For such a conversion to be legally recognized for tax purposes, the taxpayer must be shown to be engaged in the business of real estate development, characterized by organized infrastructure, accounting records, stock registers, and a clear intent to trade. In the absence of these markers, the Tribunal reaffirmed that the asset retains its nature as a capital asset, thereby shielding the individual from the punitive tax rates associated with business income.
The Burden of Evidence in Family Transfers
The second component of the ITAT’s ruling focused on the transfer of five flats from the husband to his wife via registered sale deeds. The Income Tax Department viewed these registered deeds as prima facie evidence of a commercial sale, intending to treat the market value of these transactions as taxable business income. However, the taxpayer provided evidence, including an affidavit from his spouse and bank statements, to establish that no actual consideration had exchanged hands.
The Tribunal’s decision highlights a crucial legal distinction: the mere execution of a sale deed for administrative or security purposes does not automatically constitute a taxable sale for income tax purposes if the underlying commercial reality—specifically the flow of funds—is absent. The ITAT relied on previous judicial precedents to conclude that when a transaction lacks the hallmark of a commercial exchange (i.e., payment), it cannot be treated as a sale simply because the legal paperwork was completed. This is a vital takeaway for Indian families who often redistribute property holdings for estate planning or security purposes, demonstrating that tax authorities must look beyond the instrument of conveyance to determine the actual nature of the transaction.
Strategic Structuring and Risk Mitigation
This ruling serves as a professional benchmark for how taxpayers should approach complex property transactions. The primary lesson for property owners is that the characterization of a transaction must be substantiated by the consistency between legal documentation, accounting treatment, and actual conduct. When an individual enters into a JDA, they should ensure that the transaction is documented in a manner that aligns with their status as an investor rather than a professional developer.
Maintaining a clear trail of evidence—such as original investment records, the absence of real estate business infrastructure, and explicit documentation regarding the rationale for property transfers—is essential to withstand scrutiny. As the Income Tax Department continues to digitize and integrate records from the Registrar of Properties with income tax filings, inconsistencies between the intent stated in documents and the actual flow of funds will become easier for authorities to flag. Proactive tax planning, rather than reactive litigation, is the most effective path to preventing large-scale tax demand notices.
The Shifting Landscape of Tax Scrutiny
The Indian tax environment is undergoing a transformation, with the administration moving toward a model of automated data analytics. The ITAT’s focus on “substance over form” remains a defense for taxpayers, but this protection is only effective when a taxpayer can prove the substance through objective data. In this case, the taxpayer’s ability to produce financial evidence (bank statements and affidavits) to rebut the assumptions of the tax department was pivotal.
For high-net-worth individuals and landholders participating in development projects, this case underscores the necessity of professional advice before executing agreements. Contracts should be drafted to clearly reflect the intent of the parties involved, avoiding ambiguous terminology that could be misinterpreted by the assessing officers as an intent to engage in trade. Furthermore, as family arrangements become more structured, understanding the difference between a gift, a transfer for security, and a taxable sale is essential to avoid unnecessary litigation.
Future Outlook for Property Taxation
Looking ahead, the integration of technology in property registration and tax assessment will continue to heighten the scrutiny on developers and landowners alike. The ITAT Delhi judgment acts as a shield against the overreach of tax authorities who might attempt to categorize individual, one-off transactions as business activity without sufficient proof. However, it also serves as a warning: taxpayers who lack proper documentation or who engage in activity that resembles a business enterprise will find it increasingly difficult to defend their position.
Ultimately, the ruling reaffirms a fundamental tenet of Indian tax law: the burden of proof rests on the tax department to establish that a transaction constitutes business income, but the taxpayer must provide the necessary documentation to support their stance that the transaction remains a capital or family arrangement. Moving forward, aligning contractual obligations, financial records, and commercial intent will remain the most reliable strategy for taxpayers to secure their financial interests while minimizing the risk of protracted legal battles with the revenue department. By treating tax compliance as a foundational element of property management, rather than an afterthought, owners can ensure their assets remain protected under the capital gains framework, thereby avoiding the unintended consequences of high-pressure tax assessments.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News