The Risks of PAN Misuse in the Digital Tax Era
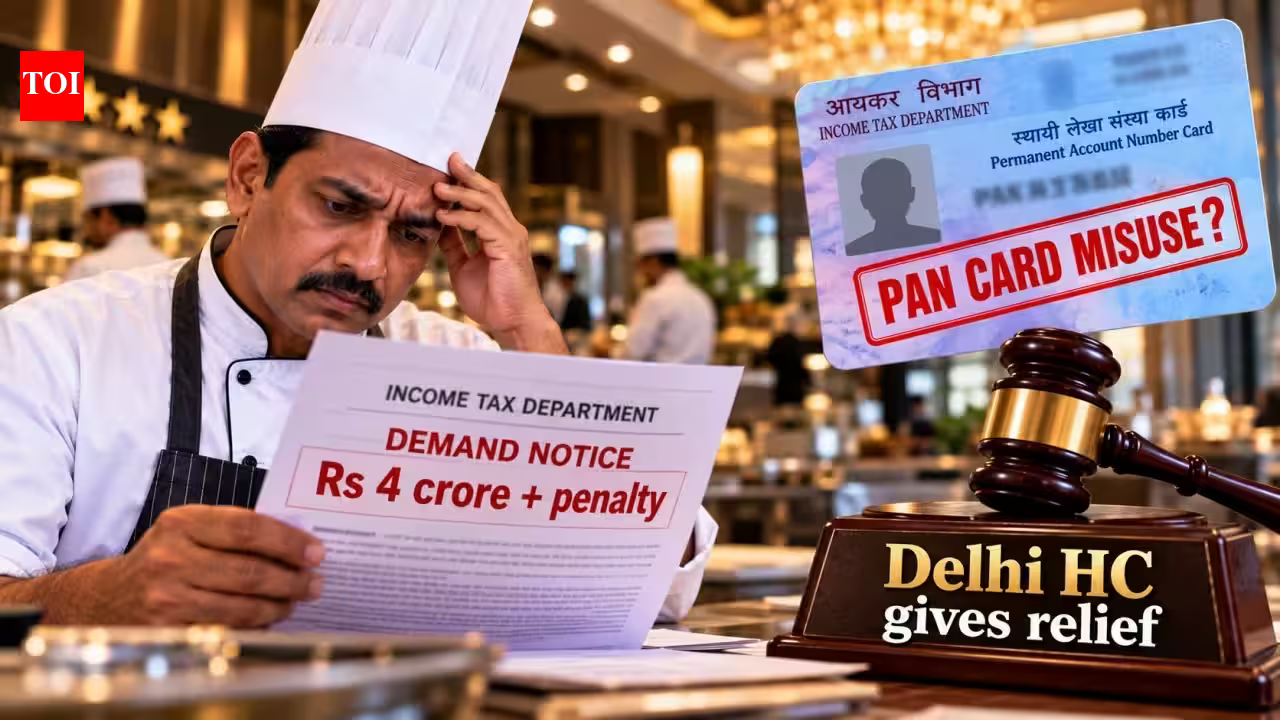
In an era where identity verification is increasingly reliant on digital credentials, the Permanent Account Number (PAN) has become a double-edged sword. While it serves as the primary identifier for financial transactions in India, it is also a target for identity theft. A recent landmark case decided by the Delhi High Court highlights the severe repercussions of such misuse. A contractual cook at a 5-star hotel found himself the target of a staggering Rs 4 crore tax demand, linked to alleged cash sales of Rs 24.62 crore that he had no connection to.
This case serves as a cautionary tale for the common taxpayer. Form 26AS, which acts as a consolidated statement of tax credits and financial transactions linked to a PAN, has become the foundational document for the Income Tax Department’s automated scrutiny processes. However, as this case demonstrates, automated systems can misinterpret data, leading to mechanical assessments that ignore the ground reality of a taxpayer’s financial profile. For individuals who have shared their identity documents for employment or verification purposes, the risk of their credentials being exploited for shell company activities or fraudulent reporting is a growing concern.
The Anatomy of the Tax Department’s Failure
The core issue in the aforementioned case was the reliance of the Assessing Officer (AO) on data available on the tax portal without conducting further verification. In modern tax administration, the Income Tax Department utilizes data analytics to flag anomalies. While this technology is effective in catching tax evasion, it lacks the nuance required to distinguish between genuine business activity and identity theft.
The Delhi High Court’s critique of the department was scathing. The court noted that the assessment was purely data-driven, failing to establish any independent link between the petitioner and the alleged transactions. By failing to perform basic due diligence—such as issuing a notice under Section 133(6) of the Income-tax Act to the entity that actually facilitated the transaction—the tax department created a financial burden that was entirely disconnected from the petitioner’s reality. Furthermore, the presence of an Economically Weaker Section (EWS) certificate and records of provident fund withdrawals provided a clear, verifiable picture of the man’s financial status. The court determined that the department’s failure to cross-reference the alleged business turnover with the taxpayer’s actual economic circumstances represented a departure from the principles of natural justice.
Legal Protections and Judicial Intervention
The Delhi High Court’s ruling reinforces the principle that judicial bodies act as a safeguard against arbitrary administrative action. The petitioner was faced with an impossible situation: he had to either pay a substantial tax demand or pursue an appeal, which would have required a significant upfront deposit, a feat beyond his means. By approaching the High Court, he bypassed the limitations of the standard appellate process, which often penalizes taxpayers financially for seeking justice.
The court’s observation that a tax officer must ensure their findings remain “grounded on the floor of reality” is a directive for more human-centric tax administration. It reminds officials that while revenue generation is a key administrative goal, it cannot come at the expense of punishing innocent citizens for the crimes of others. The court effectively quashed the tax demand, emphasizing that the mere appearance of a PAN in an annual tax summary does not constitute sufficient proof of income for tax liability purposes. This precedent protects taxpayers from being held liable for phantom income fabricated through stolen identities.
Preventive Measures for Individual Taxpayers
To mitigate the risk of identity theft and the resulting legal turmoil, individuals must adopt proactive measures to secure their sensitive financial information. In India, many workers are required to submit copies of their PAN cards for employment, insurance, or utility connections. It is a best practice to write a disclaimer on any photocopy of a PAN card, clearly stating the purpose for which it is being provided (e.g., “For employment purpose only, dated [Date]”).
Furthermore, taxpayers should make it a habit to check their Form 26AS and the Annual Information Statement (AIS) at least once every quarter. These documents are available on the Income Tax e-filing portal and reflect all high-value transactions, such as property sales, stock market trading, or large cash deposits, linked to a PAN. By monitoring these statements regularly, an individual can identify unauthorized entries early. If a discrepancy is spotted, immediate action—such as filing a police complaint and informing the Income Tax Department—is essential to create an official paper trail that can be used as evidence in future proceedings.
The Future of Automated Scrutiny in India
The Indian taxation system is moving toward a faceless assessment model, which aims to reduce corruption and increase transparency. However, as the Delhi High Court’s ruling suggests, the efficacy of this system depends on the quality and accuracy of the underlying data. As the Income Tax Department integrates more data from diverse sources into its scrutiny algorithms, the potential for “false positives” increases.
To maintain public trust, the tax authorities must refine their verification protocols. The integration of artificial intelligence should be paired with robust grievance redressal mechanisms that allow taxpayers to flag identity theft without being forced into financial hardship. For the taxpayer, the burden of vigilance remains high. In an environment where personal data can be easily traded, protecting one’s PAN is as important as protecting one’s bank account credentials. As the legal landscape evolves to address these challenges, the judiciary has made it clear that while tax laws are stringent, they are not intended to persecute the vulnerable or ignore the facts in favor of automated convenience. Tax enforcement, while essential for the national exchequer, must remain balanced, logical, and deeply rooted in the realities of the taxpayer’s life.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News