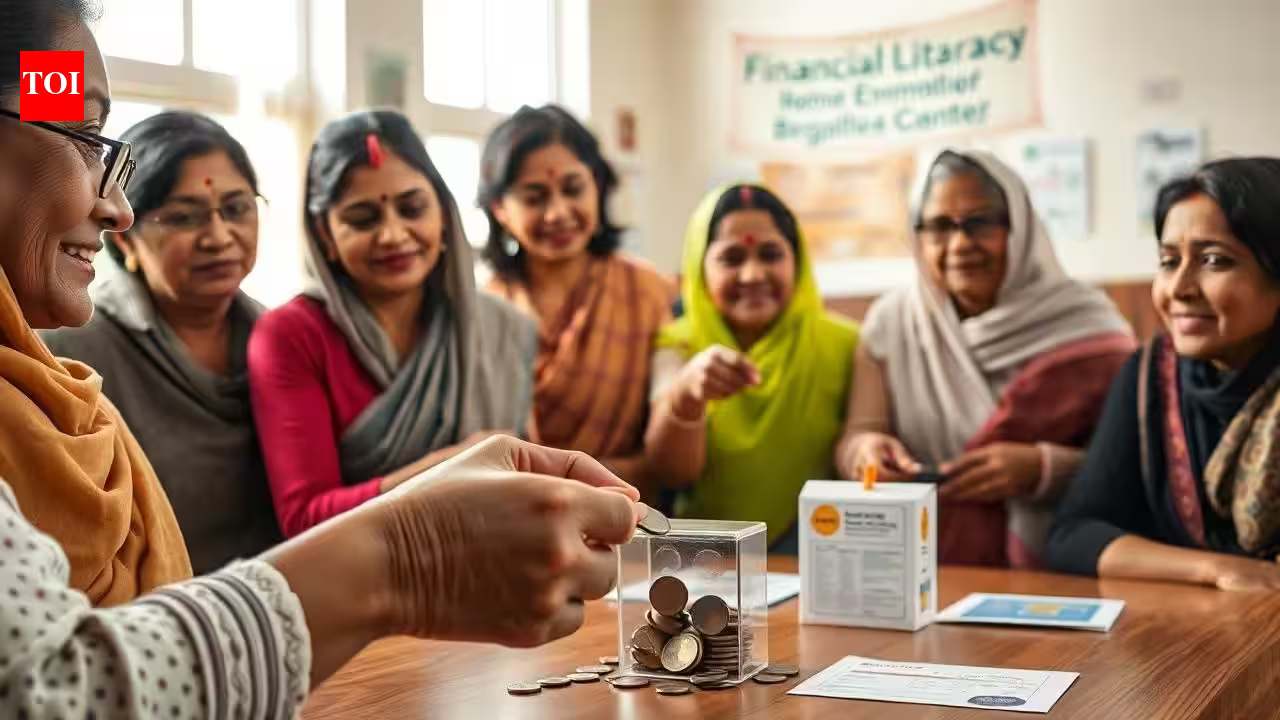
The evolving landscape of personal finance in India presents a complex dichotomy: while financial inclusion metrics have reached record highs, substantive financial control and literacy among women remain trapped behind a veil of traditional structures. Recent data indicates that nearly 90 percent of Indian women possess bank accounts, yet there is a profound disconnect between possessing a financial instrument and wielding the authority to manage it. This gap often leads to precarious situations where women, despite contributing to household income or managing daily operational budgets, find themselves blindsided by life events such as the death of a spouse or the dissolution of a marriage.
The Mirage of Financial Participation
The sheer accessibility of banking services in India, driven by government initiatives and the digitization of payments, has succeeded in onboarding millions of women into the formal economy. However, participation is frequently limited to routine transactions—paying household bills or managing small daily savings. Decisions regarding capital allocation, such as property acquisition, insurance optimization, retirement planning, and long-term wealth management, remain overwhelmingly dominated by male family members.
Market data underscores this divide. While banking penetration is nearly equal between genders, formal saving rates among men significantly outpace those of women. This suggests that even when money is available, it is not being deployed with the same strategic intent or confidence. The reliance on male relatives for high-level financial navigation is not merely a matter of convenience; it is a structural byproduct of societal conditioning. When a woman is excluded from the technical aspects of the family’s asset portfolio—passwords, account documentation, and investment rationales—she is effectively relegated to a position of financial dependency, regardless of her personal income level.
Systemic Vulnerability and Household Risk
The consequences of this exclusion are often invisible until a crisis occurs. Financial advisers frequently cite cases of widows who, despite having substantial household wealth, are unable to access funds because they lack basic familiarity with the digital architecture of their spouse’s accounts. This is not a failure of intelligence, but a failure of transparency within the household unit.
Financial preparedness is a critical safety net that extends beyond the individual. When a woman is excluded from the family’s financial roadmap, the household becomes vulnerable. Should the primary breadwinner or the individual managing the assets become incapacitated, the lack of information flow turns manageable administrative tasks into exhausting, and sometimes futile, legal battles. This exposure highlights that financial literacy for women is not an accessory to modern life; it is a fundamental requirement for risk mitigation. The transition from “managing the kitchen budget” to “managing the family’s long-term prosperity” is a necessary evolution for every household in India.
Challenging Entrenched Financial Norms
Breaking the cycle of financial passivity requires confronting deep-seated stereotypes. In many Indian households, there exists an unspoken rule that men are the innate managers of complex financial affairs. This narrative creates a barrier that discourages women from engaging with investment products or asking critical questions about their own money. The social stigma attached to a woman taking the lead in financial planning can discourage participation, often leading women to self-select out of decision-making roles even when they are fully capable of handling them.
Moreover, the responsibility for this shift is multifaceted. It involves a movement within the family to treat financial discussions as collaborative rather than segregated duties. A shift in perception—where financial literacy is viewed as a prerequisite for autonomy rather than a task delegated by gender—is required. Men, too, have a role to play in ensuring that their partners are co-pilots in financial strategy, ensuring that all documentation is accessible and that investment logic is shared. True independence is not just the ability to earn, but the confidence to understand the life cycle of every rupee earned.
The Evolving Role of Financial Education
Encouragingly, there are signs that the tide is turning. Recent reports from bodies such as NITI Aayog demonstrate that credit penetration among women is rising, and an increasing number of women are proactively monitoring their credit scores. This is a crucial indicator that women are beginning to engage with the formal mechanisms of the financial system on their own terms. However, there is a distinct difference between being a borrower and being an informed investor.
To bridge this gap, financial institutions must move beyond generic marketing and create platforms that speak directly to women. This involves simplifying product terminology and providing educational resources that cater to the specific needs of women who are ready to transition from casual users of financial services to strategic planners. The shift toward autonomy should not be overwhelming; it begins with the basics: maintaining independent records of income and expenditure, understanding the terms of existing insurance policies, and actively participating in the decision-making meetings that dictate the family’s long-term goals.
Creating a Sustainable Path to Empowerment
For a nation as diverse as India, financial literacy must be integrated into the broader life-skills curriculum. Schools and colleges have an opportunity to introduce financial management concepts early, ensuring that the next generation of women does not inherit the hesitation of their predecessors. Simultaneously, the financial services sector must prioritize inclusivity in their communication, ensuring that banks and investment firms address all stakeholders in a household equally.
Ultimately, the goal is to decouple gender from financial competence. A woman’s capacity to manage her financial future should not be hampered by archaic norms or a lack of opportunity. By shifting the conversation from simple access to meaningful engagement, India can ensure that its female population is not just participating in the formal economy but is actually empowered to shape its own financial destiny. This transformation will not happen overnight, but through the consistent application of practical knowledge, the normalization of financial inclusion in the home, and the unwavering demand for transparency in all financial affairs, it is an achievable and necessary milestone. As the landscape of the Indian economy continues to grow, the inclusion of women as full-fledged architects of their own wealth will be the true measure of a mature, modern, and resilient financial society.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News