India’s BESS Ambitions Cross 100GW Threshold, But Hurdles Mount for 2032 Targets
India’s transition toward a green grid has reached a significant milestone, with the national Battery Energy Storage System (BESS) project pipeline officially surpassing the 100GW mark. As the nation races to integrate vast amounts of intermittent solar and wind energy, BESS has emerged as the critical backbone for grid stability. However, while the capacity pipeline suggests a robust roadmap toward the government’s target of 411.4GWh of storage by FY2032, industry experts warn that the road to commissioning is fraught with systemic challenges.
The Scaling Challenge
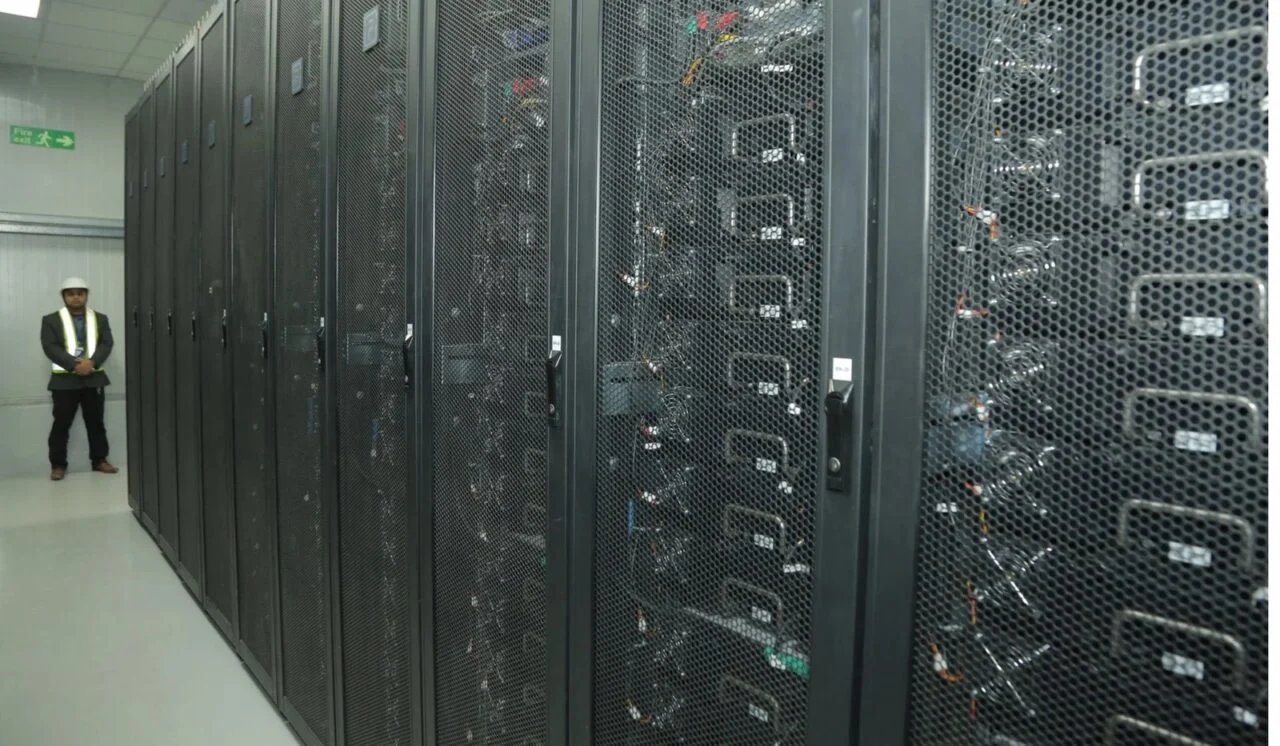
The current pipeline reflects an aggressive push by both public sector undertakings and private players to secure a foothold in the storage market. Tata Power and other major utility-scale developers are spearheading these efforts, backed by government tenders designed to incentivize long-duration storage.
Despite this, the gap between “announced capacity” and “operational capacity” remains wide. Industry analysts highlight that while developers are eager to announce massive portfolios, the actual pace of construction remains sluggish. Infrastructure constraints, land acquisition complexities, and the intricate process of grid integration for large-scale battery farms continue to delay project timelines.
Financing and Tariff Pressures
Perhaps the most daunting hurdle is the economic viability of these projects. BESS installations are notoriously capital-intensive, and current tariff structures are under significant pressure. Developers are finding it increasingly difficult to balance the high cost of lithium-ion and alternative battery chemistries against the aggressive reverse-auction tariffs set by state distribution companies (DISCOMs).
With lenders becoming increasingly cautious about the long-term bankability of storage projects, the cost of capital has risen. Financial institutions are demanding greater clarity on revenue streams—beyond simple peak-shaving applications—to justify the high upfront investment. Without a clear framework for “value stacking,” which would allow operators to earn revenue through arbitrage, frequency regulation, and ancillary grid services, project developers may struggle to reach financial closure on the remaining 75% of the required capacity.
Supply Chain and Execution Risks
While the Indian government has introduced Production Linked Incentive (PLI) schemes to encourage domestic manufacturing of advanced chemistry cells, the supply chain remains heavily dependent on imports for raw materials and critical components. Fluctuating global commodity prices and logistical bottlenecks pose a constant threat to project execution.
Furthermore, the scale of the 411.4GWh target requires not just capital, but a massive surge in technical expertise. India’s power sector is currently grappling with a shortage of specialized talent capable of managing sophisticated Battery Management Systems (BMS) and the integration of storage assets into legacy grid infrastructure.
The Path Forward
To meet the FY2032 deadline, policy experts suggest that the government must move beyond mere capacity procurement. Providing “viability gap funding” to bridge the financial divide, standardizing safety and performance metrics, and creating a more flexible market for energy trading are essential steps.
If India can harmonize its regulatory framework and de-risk the investment climate, the 100GW pipeline could serve as the catalyst for a global storage success story. However, if financing and execution bottlenecks persist, the nation risks falling short of the very infrastructure it needs to fuel its economic expansion and climate commitments. The coming three years will be the “make-or-break” period, determining whether these gigawatts transition from paper to power.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News