
The Growing Threat of Institutional Fraud in India
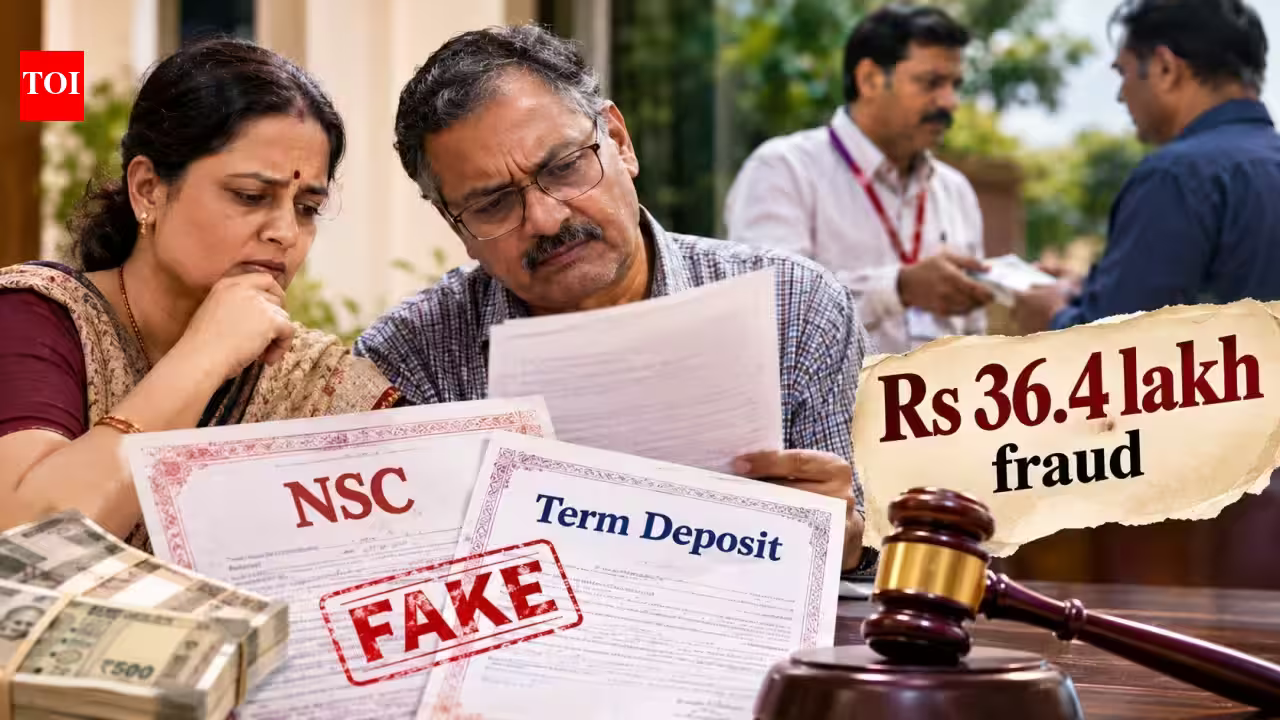
Financial security remains a cornerstone of the Indian household economy, with millions of citizens relying on government-backed institutions like the India Post to safeguard their life savings. The recent ruling by the Madhya Pradesh High Court regarding a fraudulent scheme at the Bina post office branch underscores a critical vulnerability in the intersection of public trust and bureaucratic oversight. In this instance, depositors were swindled out of Rs 36.4 lakh through counterfeit National Savings Certificates (NSCs) and falsified term deposit slips issued by individuals who, while employed by the Department of Posts, were not authorized to conduct business at that specific location.
This incident highlights a growing concern in the Indian financial sector: the exploitation of institutional credibility by insiders. When citizens visit a government post office, they do so with a foundational assumption of integrity. They rarely possess the resources or the expertise to verify the internal deployment status of staff members. The Madhya Pradesh High Court’s decision to rule in favor of the victims establishes a vital legal precedent regarding vicarious liability. It forces government departments to acknowledge that when an institution’s physical premises and its official staff identity are used to facilitate a crime, the organization cannot merely deflect responsibility by citing internal administrative lapses.
Understanding the Mechanics of Institutional Liability
The legal battle in the Bina post office case centered on the concept of “vicarious liability”—the legal responsibility of an employer for the wrongful acts of employees, provided those acts occur within the scope of employment or under the appearance of authority. The Department of Posts argued that since the perpetrators were not posted at the Bina branch at the time of the transactions, the department should not be held accountable. They contended that depositors failed to exercise due diligence by not verifying the authorization of the staff handling their money.
The High Court rejected this logic, identifying the unfairness of expecting ordinary citizens to navigate the complexities of internal government transfers. The court recognized that the perpetrators used the official infrastructure of the post office to create a facade of legitimacy. Because the depositors acted in good faith—believing they were interacting with official state representatives—the court found that the department must bear the financial burden of the loss. This ruling serves as a stern reminder to state-run financial entities that public trust is a liability-heavy asset. If an institution provides the environment where a fraud takes place, the institution is responsible for the systemic failures that allowed that fraud to thrive.
The Intersection of Technology and Regulatory Oversight
While the court ruling brings justice to the victims, it also illuminates a broader need for structural reforms within Indian financial institutions. The manual nature of many post office transactions in rural and semi-urban India provides fertile ground for such fraudulent activities. In an era where digital banking and Unified Payments Interface (UPI) systems have revolutionized retail finance in India, the reliance on physical, easily forgeable passbooks and paper-based deposit slips is increasingly problematic.
To mitigate such risks, the Department of Posts has been aggressively pushing for the digitization of core banking services. However, the transition is not uniform across the vast network of rural branches. When institutional processes lag behind technology, fraud becomes easier to perpetrate. For the consumer, this creates a hybrid landscape where official digital systems coexist with archaic, paper-based workflows that are susceptible to human manipulation. Protecting consumers requires not just legal recourse after the fact, but an immediate move toward transparent, real-time transaction tracking where every deposit is instantly authenticated through a centralized, visible server that the consumer can verify via mobile alerts or digital portals.
Best Practices for Depositors in a Fraud-Prone Environment
The Madhya Pradesh High Court’s judgment serves as a protective shield for depositors, but it should not be viewed as a reason for complacency. Financial literacy and vigilance are the primary defenses against such incidents. Indian depositors must adopt a more structured approach to managing their investments in traditional savings schemes. The first rule of engagement is to interact exclusively with authorized service counters. If an employee approaches a customer away from the designated counter, it should be treated as an immediate red flag, regardless of how official that individual may appear.
Furthermore, documentation is the depositor’s most potent evidence. Every transaction, whether for a term deposit or an NSC, must be accompanied by an official, computer-generated receipt that can be cross-referenced with online portal data. If a branch is unable to provide a system-generated acknowledgment, the transaction should not proceed. Keeping physical records is insufficient in the digital age; depositors should actively participate in SMS alert services and ensure their mobile numbers are linked to all accounts. The 2021 circular from the Department of Posts, referenced in the court ruling, provides a framework for addressing such grievances, but knowing these procedures exists is half the battle; ensuring that one’s accounts are reflected in the central database is the preventive measure that matters most.
The Broader Implications for Indian Financial Governance
The ruling in this case signals a shift toward a more consumer-centric interpretation of financial regulations in India. By mandating that the Department of Posts compensate the victims despite the department’s internal bureaucratic defense, the judiciary has prioritized the protection of the retail investor over administrative convenience. This has wide-reaching implications for all state-managed savings schemes, including those operated by nationalized banks and public sector undertakings.
Institutions will now be forced to tighten their internal controls, monitor staff movements more rigorously, and perhaps implement stricter physical security measures in branch premises to prevent unauthorized personnel from interacting with customers. For the broader Indian economy, this is a positive development. As the nation attempts to drive deeper financial inclusion, the integrity of these institutions is paramount. When a citizen deposits money into a government-backed scheme, the assurance of safety is the product they are purchasing. If that assurance is compromised, the entire model of public savings faces a crisis of confidence. Moving forward, the lesson for state institutions is clear: proactive security and transparent communication with the public are not just operational goals, but essential components of legal and ethical governance.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News