Digital Financial Integration and the Risk of Unauthorized Access
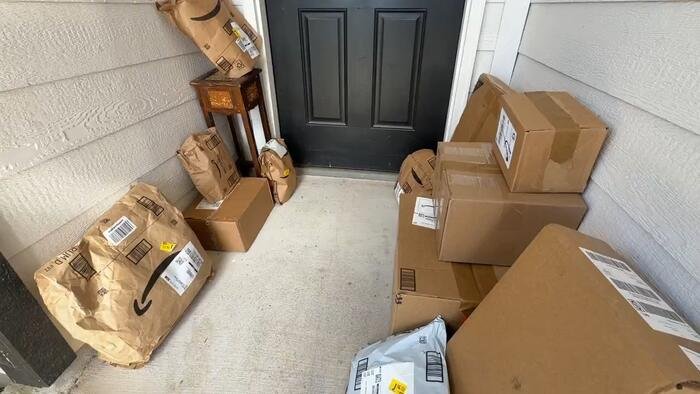
The recent incident in Converse, Texas, involving a 10-year-old child who bypassed digital security measures to incur nearly $2,000 in debt highlights a growing technological challenge: the ease with which minors can navigate complex financial ecosystems. By linking an Amazon account to an Affirm credit service, the child exploited the seamless nature of modern digital transactions. This occurrence sheds light on the unintended consequences of “frictionless” checkout processes that are designed to prioritize user conversion over robust identity validation.
When software platforms prioritize speed, they often utilize stored credentials that link various services behind the scenes. In this specific case, the child was able to navigate the account setup process by interpreting repetitive on-screen prompts as simple gameplay mechanics. This effectively transformed a sophisticated financial transaction into an interface that a minor could operate without realizing the permanence of the resulting debt. As payment platforms continue to integrate directly into retail interfaces, the boundary between an application for credit and a simple purchase button has blurred, presenting new vulnerabilities for families using shared or weakly secured devices.
The Vulnerability of Automated Identity Verification
Financial technology companies, such as Affirm, employ identity verification systems designed to prevent underage users from accessing lines of credit. These systems typically mandate that applicants provide their legal name, physical address, date of birth, and, in many instances, partial Social Security numbers. This data is cross-referenced against credit bureau databases to confirm the user’s identity and age.
However, these automated systems often rely on the information already present in the device’s ecosystem or digital footprint. If a parent has previously authorized a device or browser to save personal financial credentials, the protective barriers intended to filter out minors can be bypassed. When a child has access to an email address linked to a parent’s credit bureau profile, the automated verification software may perceive the activity as legitimate. This demonstrates that while algorithmic security is sophisticated, it is not infallible when the “user” possesses authorized access to the credentials being verified.
Parental Control Limitations in the Modern Smart Home
The case in Texas serves as a critical study in the failure of standard parental controls to intercept financial activity. Despite the family setting up monitoring for the child’s email, the notifications failed to trigger before the purchases were processed and shipped. Modern digital architecture often prioritizes user experience, meaning that confirmation emails or account alerts may be delayed or filtered into folders that children or even parents overlook.
Parents often rely on software-based parental controls, such as screen time limits or content filters, but these features are frequently insufficient when it comes to financial apps. Most security software focuses on preventing access to inappropriate content rather than monitoring the transactional status of connected finance tools. As children become increasingly adept at navigating digital interfaces, traditional parental controls must evolve to include granular restrictions on financial API calls—the background code that allows apps like Amazon to communicate with payment processors like Affirm.
Third-Party Retail Complexity and Refund Mechanics
One of the significant complications in this incident involves the nature of third-party marketplace sellers. Amazon operates both as a direct retailer and as a host for independent merchants. When a purchase is made through a third-party seller, the return policy is often dictated by that merchant rather than the platform itself. This introduces a layer of logistical difficulty: if the items have already been processed and shipped, the cost of restocking or return shipping may fall on the consumer.
From a technical standpoint, the refund process requires the coordination of three distinct parties: the retail platform, the third-party merchant, and the financial lending institution. When a loan is identified as fraudulent or unauthorized, the financial institution must reverse the transaction at the ledger level. While Affirm has committed to cancelling the loan and ensuring no negative impact on the family’s credit report, the physical return of goods remains a bottleneck. This illustrates that while digital financial systems can be reversed with a keystroke, the physical supply chain—shipping, handling, and restocking—cannot be instantly undone.
Securing Digital Wallets for the Future
For families looking to prevent similar issues, the primary recommendation is the implementation of multi-factor authentication (MFA) that is tied to a device the child does not possess. Relying on an email-based confirmation is insufficient if the child has access to the email account. By requiring a secondary physical token—such as a biometric scan on a parent’s phone—families can add a layer of friction that is difficult for a minor to bypass.
Additionally, consumers should regularly audit their connected accounts. Many users authorize “one-click” payments for convenience, forgetting that these authorizations remain active indefinitely across linked services. Disconnecting financial accounts from shopping profiles and requiring manual entry for each transaction serves as a manual “fail-safe.” As the digital economy continues to expand, the responsibility for securing assets is shifting from the institution to the user. Understanding how these platforms communicate with one another is the first step in maintaining control over one’s financial footprint in an increasingly interconnected world.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News