American Express has delivered a robust third-quarter performance, showcasing the resilience of its affluent customer base even as the financial giant implements significant structural changes to its workforce. The New York-based credit card giant reported a 28% jump in profit, reaching $3.71 billion, as it successfully navigated a strategic transition to a higher-fee structure for its signature Platinum Card product.
## Profitability Gains and the Premium Card Strategy
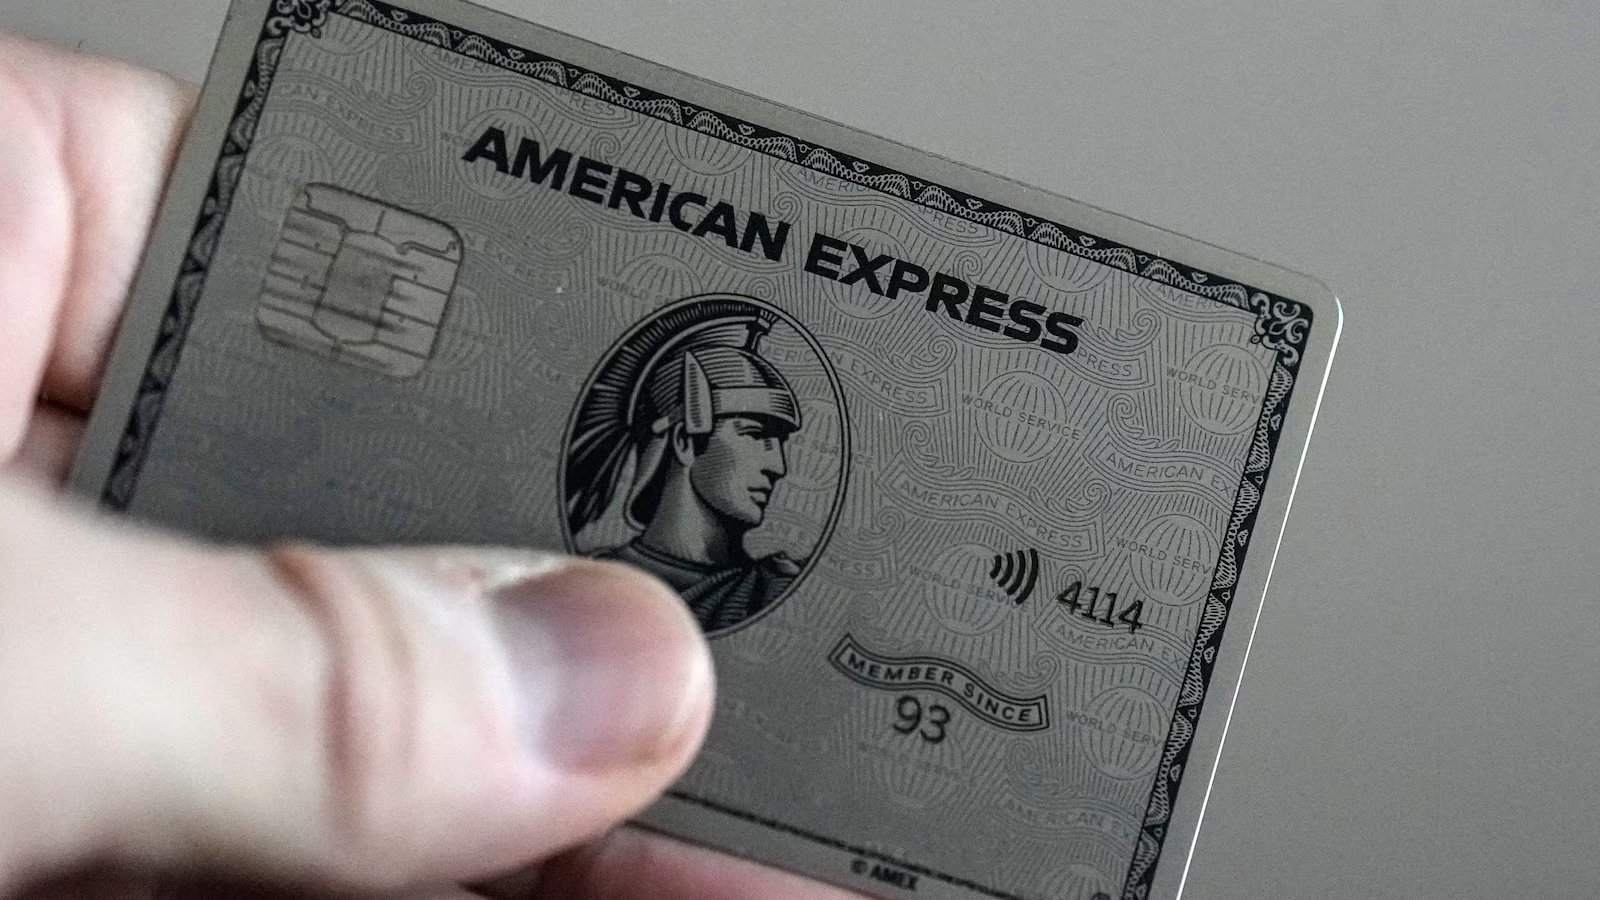
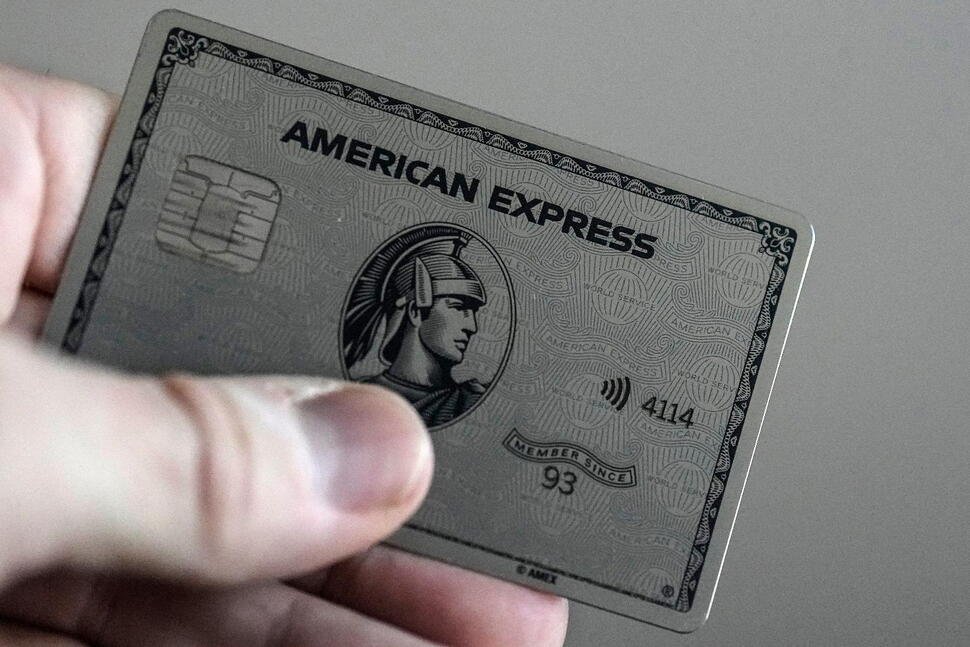
The company’s decision to increase the annual fee on its Platinum Card from $695 to $895—a move that initially drew skepticism from market analysts—has proven to be a financial success. Despite the $200 price hike, American Express reports that the vast majority of existing cardholders have opted to maintain their memberships. This migration to the new fee tier, combined with an influx of new sign-ups, boosted net card fees by more than $400 million compared to the previous year.
Beyond fees, American Express continues to benefit from high transaction volume. The average cardmember spent approximately $6,735 during the quarter, reflecting a 5% year-over-year increase. While Chief Financial Officer Christophe Le Caillec acknowledged that inflationary pressures—particularly in airfare and travel—have inflated spending figures, the company also noted a genuine increase in the frequency of transactions per user.
## Strategic Layoffs and Operational Efficiency
In a notable shift for the organization, American Express confirmed the reduction of its workforce by 5%, impacting approximately 4,000 employees. CEO Steve Squeri emphasized that these cuts were not a response to flagging consumer demand or a softening of the economy. Instead, the move is designed to streamline operations and enhance efficiency.
The company has faced mounting pressure to manage rising operating costs, which are driven by intense competition in the premium rewards space. Players like JPMorgan Chase and Capital One have consistently upped the ante with aggressive perk packages, forcing American Express to balance high-value rewards with sustainable margins. By optimizing its internal structure, management aims to shield its bottom line from the rising costs of competing for the most lucrative customers.
## Future Outlook and Market Performance
Wall Street responded favorably to the latest results, as American Express beat earnings expectations with a quarterly profit of $4.68 per share, excluding a one-time divestiture gain from the sale of its stake in Global Business Travel Group. Bolstered by this performance, the company raised the lower end of its full-year earnings forecast, now projecting an adjusted profit between $17.60 and $17.90 per share.
As the company looks toward the end of the year, its reliance on a high-spend customer demographic appears to be a defensive moat. While other lenders may be more vulnerable to broader economic volatility, American Express’s portfolio of wealthy spenders remains committed to the platform’s travel and entertainment-focused value proposition.
The successful navigation of this transition—balancing a massive migration to a more expensive product with simultaneous corporate restructuring—signals a pivot toward a leaner, more premium-focused business model. For investors, the takeaway is clear: as long as the travel and luxury sectors remain buoyant, the American Express strategy of rewarding loyalty with top-tier benefits—even at a steeper cost—appears to be paying off in spades. The company now enters the final quarter of 2026 with reinforced guidance and a clearer path to margin expansion despite the ongoing overhead costs associated with maintaining its market-leading rewards ecosystem.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News