The Evolution of Market Infrastructure Institutions and the Question of Self-Listing
The landscape of Indian financial markets has undergone a profound transformation over the last decade. From the digitization of trading processes to the demutualization of stock exchanges, the sector has moved toward greater transparency, corporate governance, and operational efficiency. A critical milestone in this journey has been the listing of Market Infrastructure Institutions (MIIs), specifically the National Stock Exchange (NSE) and the Bombay Stock Exchange (BSE).
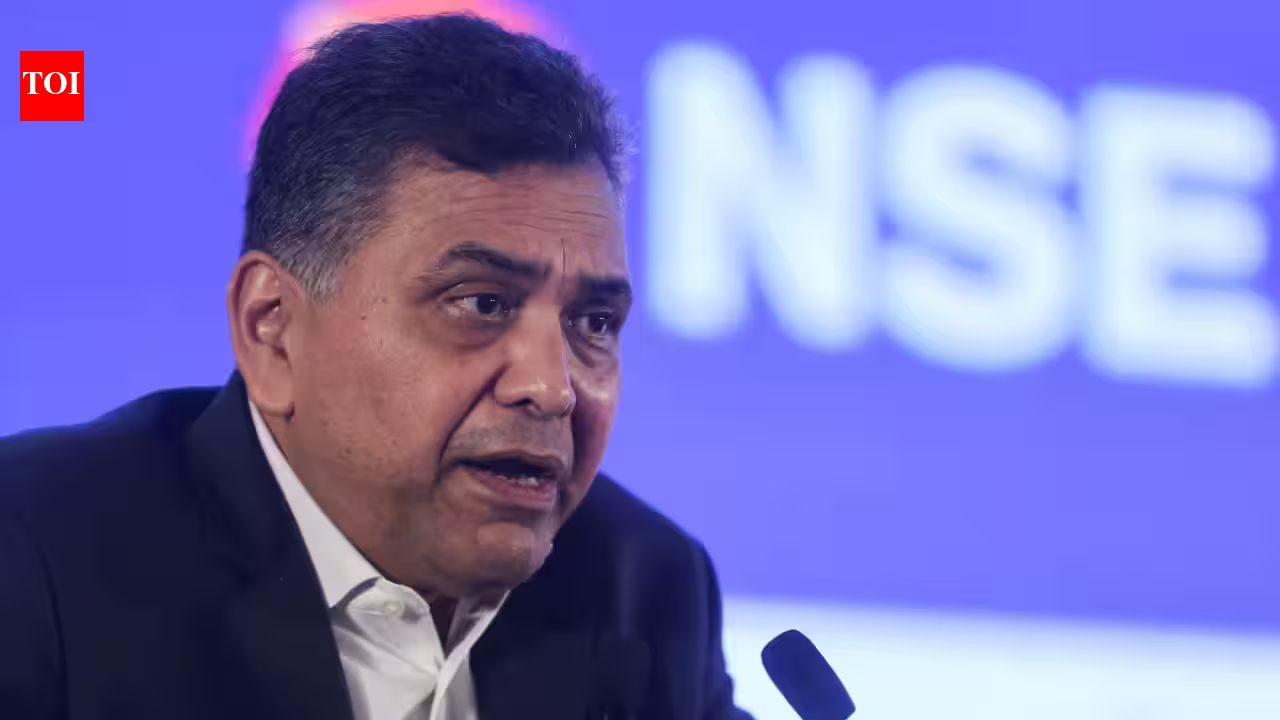
Recently, the conversation has shifted toward the feasibility of “self-listing,” a mechanism that would allow an exchange to trade its own shares on its own platform. NSE Chairperson Srinivas Injeti’s recent remarks underscore that while this is not currently permissible under existing Securities and Exchange Board of India (Sebi) regulations, the regulatory framework is dynamic. The history of MIIs in India suggests that policy shifts often follow the maturing of the financial ecosystem. Before 2012, the listing of exchanges was a distant concept; by 2015, it became a standardized operational reality. This trajectory suggests that as the market grows, the regulator may re-evaluate the structural limitations currently in place.
Regulatory Challenges and Conflicts of Interest
The primary argument against self-listing—and the reason it remains restricted—centers on the inherent conflict of interest. An exchange serves as a frontline regulator. It is tasked with monitoring listed companies, enforcing compliance with the Listing Obligations and Disclosure Requirements (LODR), and maintaining market integrity through surveillance. If an exchange were to list its own shares, it would effectively be responsible for regulating itself. This duality creates a potential scenario where the exchange could be incentivized to overlook lapses in its own disclosure or surveillance metrics to protect its market valuation or reputation.
Regulators globally, including in India, have historically been cautious about this model. The concerns involve whether an exchange can maintain impartiality when managing its own trading activity, financial reporting, and compliance. To mitigate this, even if self-listing were to be permitted in the future, it would likely require a rigorous firewall between the commercial functions of the exchange and its regulatory oversight departments. Critics argue that even with strict separation, the perception of an “insider” advantage is difficult to fully eliminate.
The Mechanics of Oversight and Surveillance
In his recent briefing, Srinivas Injeti highlighted that the core regulatory obligation of monitoring listed entities rests with the exchange. Under the current structure, the NSE is listed on the BSE, and the BSE is listed on the NSE. This cross-listing provides a clean regulatory separation. If the NSE were to list on the NSE, it would face a distinct regulatory challenge regarding surveillance.
To address this, policymakers would need to construct a framework where the regulatory burden is either shifted to a third-party oversight body or managed by a specialized independent unit that functions autonomously from the parent entity’s management. In the Indian context, Sebi holds the ultimate authority for market oversight. If self-listing were ever to be approved, the regulator might mandate that the surveillance of the exchange’s stock be handled by an independent agency or a dedicated department within the exchange that operates without interference from the exchange’s board or executive management. This would require a sophisticated governance mechanism, perhaps going beyond existing norms to ensure that transparency is not compromised by the entity’s commercial objectives.
Market Maturity and Global Comparisons
The debate over self-listing is not unique to India. Several international exchanges have successfully navigated the complexities of self-listing. For instance, the Intercontinental Exchange (ICE) and the London Stock Exchange (LSE) operate in markets where self-listing is either a reality or a managed process. These exchanges operate under strict regulatory umbrellas that prioritize market integrity above all else.
For the Indian market, the potential move toward self-listing reflects the growing maturity of the domestic capital markets. The NSE and BSE have evolved into high-volume, tech-driven institutions that are integral to the Indian economy. As India seeks to position itself as a global financial hub, the desire for greater operational flexibility for these exchanges is a natural progression. However, the Indian regulator has always maintained a conservative approach, preferring stability over rapid liberalization. The evolution of policy will likely be incremental, driven by the need to ensure that the exchange’s public shareholders are protected while the exchange continues to fulfill its critical role as the gatekeeper of financial market standards.
Economic Implications for Institutional Investors
Allowing self-listing could significantly enhance the liquidity and discoverability of exchange shares. Currently, with NSE shares traded on the BSE and vice versa, liquidity is constrained by the cross-listing model. If an exchange were allowed to trade on its own platform, it could utilize its own high-frequency trading infrastructure, broad investor reach, and robust order-matching engines to provide better pricing and liquidity for its shareholders.
For institutional investors, this would streamline capital allocation. Exchanges are often seen as high-moat businesses with stable, recurring revenue streams, making them attractive to pension funds, sovereign wealth funds, and retail investors alike. By removing the friction of cross-listing, the market could potentially see a more accurate valuation of the MIIs. However, this economic benefit must be weighed against the potential systemic risks. The regulator’s “comfort,” as Injeti noted, remains the decisive factor. This comfort is predicated on the exchange’s ability to demonstrate that its technical and governance systems are robust enough to handle the pressures of self-regulation and self-trading without inviting systemic failure or market manipulation.
The Road Ahead: Building Regulatory Consensus
The transition toward self-listing is a policy question that will be decided over time through sustained dialogue between the exchanges and Sebi. It is likely that any move in this direction will begin with a pilot program or limited conditions rather than a total deregulation. The regulators will likely require enhanced disclosure norms, independent audit committees with specific oversight powers for the exchange’s own listing, and perhaps even a mandate for real-time reporting to the regulator regarding the exchange’s stock price fluctuations.
For the Indian corporate sector, the ongoing discussion is a sign of confidence in the systems that have been built. The fact that the leadership of the NSE is openly discussing the feasibility of such a complex move indicates that the industry is ready to take the next step in its institutional development. Whether this materializes in the short term or remains a long-term goal depends entirely on how the exchanges manage their regulatory responsibilities in the coming years. If the industry can continue to improve its track record of surveillance and market stability, the regulator may eventually view self-listing not as a risk, but as a testament to the institutional strength of the Indian financial system. For now, the status quo remains, serving as a reminder that in the world of high finance, the pace of change is dictated not just by market appetite, but by the necessity of structural safety.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News