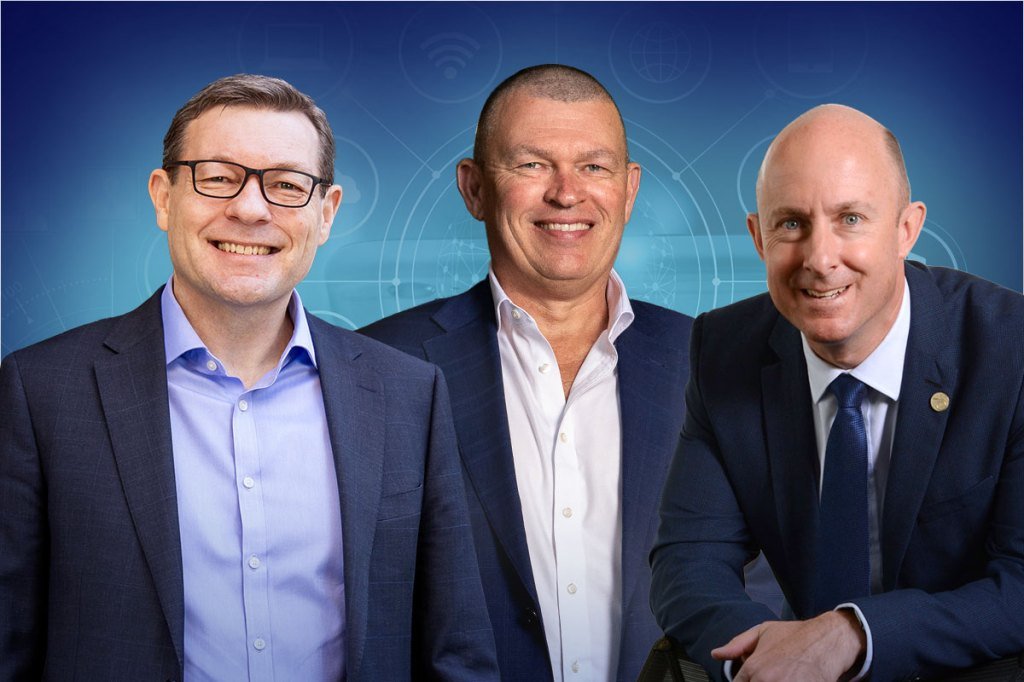
As Australia’s “Big Four” banks report record-breaking profits, a quiet revolution is gaining momentum in the financial sector. Three of South Australia’s leading financial institutions have successfully challenged the industry giants, securing spots on the South Australian Business Index by leveraging a customer-owned, mutual banking model that prioritizes member benefits over shareholder dividends.
People First Bank, Credit Union SA, and Police Credit Union are proving that being “member-owned” is a competitive advantage in a high-interest-rate economy. By reinvesting profits back into service, technology, and community support, these institutions are attracting thousands of Australians who are growing weary of traditional banking incentives.
## Digital Transformation as a Catalyst for Growth
Modern customers no longer judge their banks solely against other financial institutions; they measure them against the most advanced digital experiences they encounter daily. To compete with the tech-heavy infrastructure of the Big Four, mutual banks are undergoing massive digital overhauls.
People First Bank, which climbed 13 spots to number five on the South Australian Business Index this year, is currently spearheading a $250 million investment into its technology stack. CEO Steve Laidlaw notes that this capital deployment is aimed at making banking “simpler, faster, and safer.” By streamlining the user experience, the institution is effectively bridging the gap between traditional relationship-based banking and the convenience expected of modern fintech players.
Similarly, Credit Union SA has leaned into digital tools to complement its local presence. While the institution maintains an app and internet banking platform for routine transactions, it uses technology to facilitate complex, personal support. This hybrid model reflects a broader shift in the banking sector where AI-driven analytics and secure mobile platforms are being used to handle the heavy lifting, allowing human staff to focus on high-value advisory services.
## Strengthening the Financial Ecosystem
The success of these mutuals is not just about keeping pace with the digital world; it is about filling gaps where larger banks have often retreated. Credit Union SA, for instance, has leveraged its agility to address housing supply issues in South Australia. By creating a dedicated Residential Development Finance team, the credit union has supported the construction of 367 new homes, proving that smaller, locally focused institutions can move faster than national competitors to solve regional economic challenges.
Police Credit Union, which debuted on the Business Index at number 69 this year, emphasizes the importance of targeted service. By deploying relationship managers to hospitals and police stations to meet the unique needs of shift workers, the credit union is demonstrating a level of localized engagement that is difficult for centralized, national institutions to replicate.
## The Mutual Advantage in a Volatile Market
The fundamental difference between these mutuals and their Big Four counterparts lies in their stakeholder structure. In the traditional banking model, the primary goal is to return value to shareholders. In a mutual model, the customer is the owner.
“We don’t have to return dividends to shareholders,” says Nick May, the recently appointed CEO of Police Credit Union. “Our profits go back into the business and to members through products, services, and community investment.”
This focus has paid dividends in terms of public trust. People First Bank reported $22.8 billion in lending last financial year, while Credit Union SA saw net profit after tax of over $5 million despite the difficult economic climate. As these institutions continue to scale, their ability to marry the scale of national banks with the personal touch of community organizations is redefining the expectations of the average Australian consumer.
As they continue to rise up the business rankings, these three mutuals are sending a clear message: in the race to provide better financial services, the best way to gain market share is to treat the customer not as a source of revenue, but as the company’s reason for being.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News