Geopolitical Instability and the Global Crude Oil Pricing Mechanism
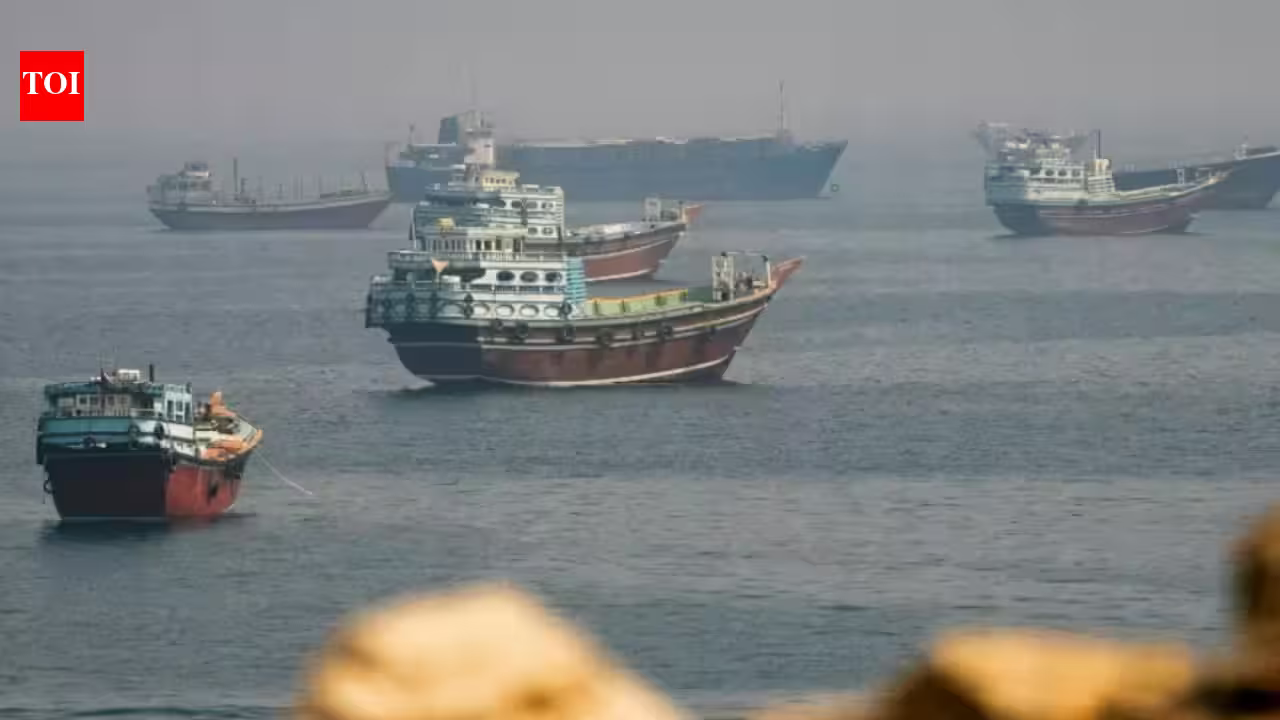
The global energy market remains in a state of precarious equilibrium as crude oil prices maintain a trajectory above the critical $100 per barrel threshold for Brent crude. This pricing pressure is fundamentally driven by geopolitical friction in the Middle East, a region that serves as the primary artery for global petroleum logistics. The escalation of maritime security concerns, specifically regarding the Strait of Hormuz, has reintroduced a significant risk premium into oil trading. Historically, this waterway has acted as a transit point for approximately 20% of global oil and fuel supplies, making it a central pillar of energy security.
Current market data indicates that shipping through these waters has become increasingly perilous. Recent reports of tanker attacks, including direct strikes on vessels north of Qatar, have transformed maritime insurance and logistics from routine operational costs into significant barriers to supply chain stability. Even as producers in the Gulf increase their export volumes to capitalize on high global demand, the physical act of moving this cargo faces heightened systemic risks. When these geopolitical hazards are coupled with the persistent threat of supply chain disruption, market participants instinctively pivot toward defensive pricing strategies, keeping Brent and WTI crude valuations firmly anchored in high-volatility territory.
The Impact of Inventory Contraction in the United States
Beyond the immediate headlines generated by Middle Eastern tensions, the market is facing a structural deficit in supply as evidenced by data from the United States Energy Information Administration (EIA). Recent reports indicate a substantial decline in American crude stocks, which plummeted by 3.2 million barrels to reach 424.1 million barrels in early October. This drawdown significantly exceeded the consensus expectations of market analysts, suggesting that demand remains resilient despite the prevailing price levels.
The depletion is not isolated to crude oil; distillate stocks, including diesel and jet fuel, have also witnessed downward pressure. Falling to 105.14 million barrels, these inventories are currently performing below the five-year seasonal average. This trend is particularly concerning for global industrial output, as distillates are the lifeblood of manufacturing, logistics, and aviation sectors. The inability of inventory levels to recover despite efforts by international bodies, such as the International Energy Agency’s release of emergency stocks, highlights a fundamental mismatch between current global consumption patterns and production capacity. When inventories fail to replenish during periods of high prices, it creates a feedback loop that sustains the upward pressure on energy costs across the board.
Implications for the Indian Economy and Energy Import Dependency
For India, the world’s third-largest consumer of oil, these developments present a multifaceted economic challenge. Given that India imports approximately 85% of its crude oil requirements, the country is uniquely susceptible to shocks in international pricing. The current geopolitical situation creates a triple-threat scenario for the Indian economy: inflationary pressure, widening trade deficits, and the erosion of fiscal policy space.
As Brent crude hovers above $100 per barrel, the landed cost of oil in Indian ports rises significantly. This increase inevitably cascades into the domestic economy, impacting the price of transportation, agricultural inputs, and manufacturing overheads. The Indian government and the Reserve Bank of India (RBI) monitor these fluctuations with extreme caution, as high energy prices are one of the primary drivers of domestic inflation. When the global price of crude moves upward, the cost of subsidies—whether direct or through regulated oil marketing companies—rises, placing pressure on the national budget. Furthermore, the outflow of foreign exchange required to pay for these imports puts downward pressure on the Rupee, complicating the broader monetary policy framework.
Supply Chain Resilience and the Cost of Maritime Logistics
The logistics of energy transportation have undergone a profound transformation over the past eight months. The escalation of hostilities near key transit points has forced shipping companies to reassess routes, crew safety, and cargo insurance. These operational shifts represent more than just a logistical inconvenience; they function as a tax on global trade. Higher insurance premiums for tankers navigating the Strait of Hormuz directly contribute to the final price consumers pay at the pump.
For a nation like India, which relies heavily on maritime transit for its energy security, the disruption in these corridors mandates a long-term strategic pivot. The diversification of import sources and the strengthening of strategic petroleum reserves are no longer merely policy suggestions but essential defensive requirements. As shipping risks rise, the cost of capital associated with transporting energy increases, making the diversification of energy sources—moving toward renewables and indigenous natural gas production—an urgent necessity for long-term economic stability. The current volatility serves as a stark reminder that energy independence is intrinsically linked to the security of international maritime corridors.
Forecasting Future Market Dynamics
Looking ahead, the trajectory of oil prices will depend on the intersection of three variables: the intensity of the Middle Eastern conflict, the efficacy of coordinated inventory management by the International Energy Agency, and the macroeconomic performance of large oil-importing economies like India and China. While the market has retreated from the extreme peaks of $126 per barrel seen earlier in the crisis, the floor has clearly shifted upward.
Analysts should observe the “distillate spread”—the price gap between crude and refined products like diesel. If this spread continues to widen, it will signal that the refinery sector is struggling to meet demand, which could cause further price spikes regardless of crude supply levels. Moreover, the market is likely to remain highly reactive to any escalation in maritime security incidents. The geopolitical risk premium is currently baked into the price of every barrel, and until there is a diplomatic de-escalation that ensures the safety of global shipping lanes, price stability will remain elusive. For business leaders and policymakers, the operating environment for the coming quarters must be defined by the expectation of sustained high energy costs, requiring a focus on operational efficiency and energy-resilient infrastructure to mitigate the inevitable fluctuations in the global energy market.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News