The Evolution of India’s Tax Treaty Framework
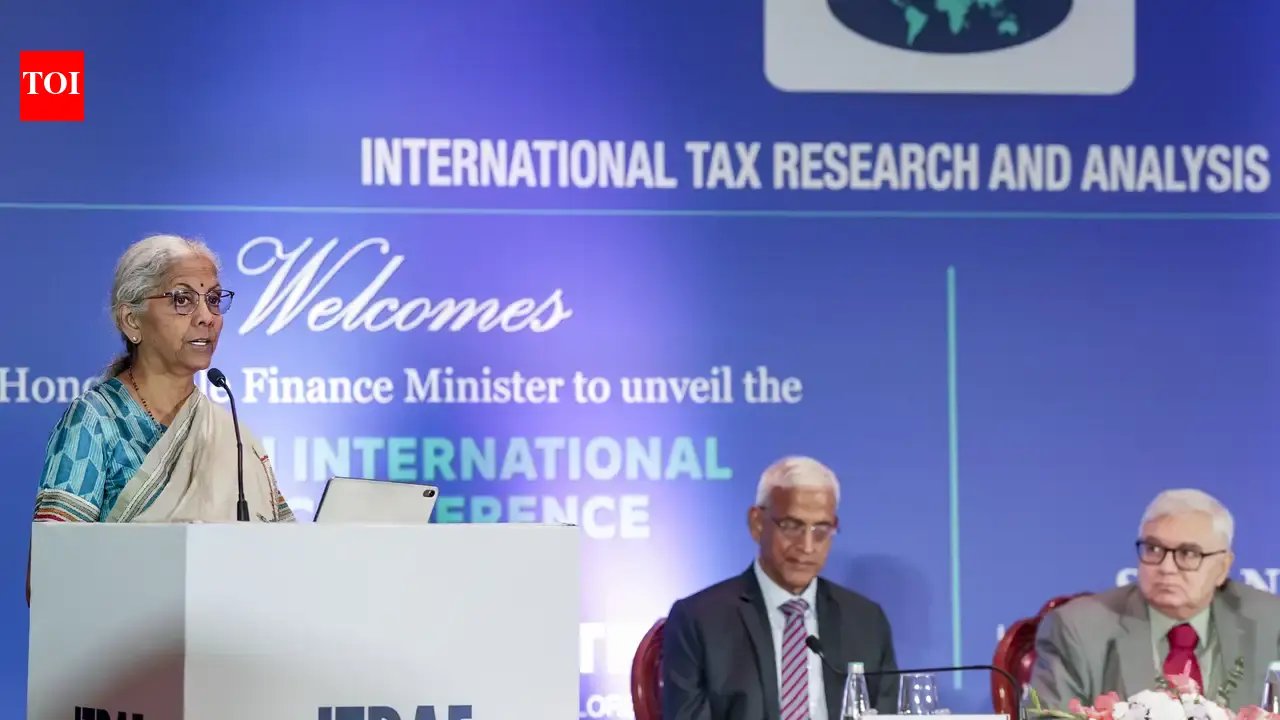
India’s international taxation landscape has undergone a significant transformation over the past decade. Finance Minister Nirmala Sitharaman recently underscored the successful renegotiation of key Double Taxation Avoidance Agreements (DTAAs) with jurisdictions such as Mauritius, Singapore, and Cyprus. These strategic shifts represent a decisive move toward a source-based taxation model, reclaiming India’s sovereign right to tax capital gains derived from investments within its borders.
Historically, the tax treaties with these nations acted as primary conduits for foreign portfolio investment (FPI) and foreign direct investment (FDI). While these structures provided a gateway for global capital to enter the Indian market, they also created opportunities for sophisticated tax planning that often resulted in the erosion of the Indian tax base. By transitioning from a residence-based system—where tax is paid only in the country where the investor resides—to a source-based system, India is aligning itself with contemporary global standards aimed at ensuring that profit is taxed where the economic activity occurs.
Strategic Rationale Behind Treaty Renegotiations
The core objective of these renegotiations is the mitigation of treaty shopping, a practice where entities establish shell companies in jurisdictions with favorable tax treaties solely to access lower tax rates or exemptions. For years, the India-Mauritius treaty served as a prominent example, as it previously exempted capital gains arising from the sale of shares in Indian companies from taxation in India.
The 2016 protocol marked a watershed moment in this fiscal evolution. It effectively introduced a grandfathering clause, ensuring that investments made before April 1, 2017, remained protected under the old regime, while subsequent investments became subject to taxation at the source. Similar protocols were mirrored in treaties with Singapore and Cyprus. These amendments were not merely technical adjustments; they were essential updates to prevent the misuse of treaty provisions. By establishing a clear threshold, the Indian government has demonstrated its intent to close regulatory loopholes that historically constrained revenue mobilization while maintaining a predictable environment for legitimate long-term capital.
Impact on Foreign Investment Dynamics
One of the central concerns following the implementation of these tax reforms was whether such measures would deter foreign capital inflows. Market data and investor behavior since the 2016 implementation suggest a more nuanced outcome. While the initial regulatory adjustments created a period of uncertainty, the long-term impact on investment quality has been largely positive. Investors today prioritize the robustness of the Indian macro-economy, the potential for corporate earnings growth, and the transparency of the regulatory framework over mere tax arbitrage.
The transition to source-based taxation has fostered a more equitable competitive landscape. Domestic investors and foreign entities are now playing by a more consistent set of rules regarding capital gains. This shift has also reduced the reliance on “round-tripping,” where domestic capital is routed through foreign jurisdictions to masquerade as foreign investment. By reducing the reliance on tax incentives to attract capital, India is signaling its maturity as an investment destination, shifting the focus toward genuine value creation and business fundamentals rather than fiscal engineering.
Navigating Global Taxation Standards
The renegotiations are also a testament to India’s commitment to the Base Erosion and Profit Shifting (BEPS) framework led by the Organisation for Economic Co-operation and Development (OECD). By incorporating limitations on benefits (LOB) clauses into its treaties, India ensures that tax benefits are only accessible to entities that possess significant economic substance. These clauses prevent the use of paper-based companies, which lack commercial rationale, from claiming treaty exemptions.
In the Indian business context, these measures provide a necessary layer of protection against the migration of tax bases to low-tax jurisdictions. For multinational enterprises operating in India, this implies a higher burden of compliance. Organizations must now substantiate their operational presence and decision-making processes within the jurisdictions where they claim tax residency. While this increases the administrative complexity for international firms, it offers a more stable, long-term framework that is less susceptible to sudden shifts in international public sentiment or regulatory scrutiny.
The Role of Judicial Oversight in Fiscal Policy
The role of the judiciary, particularly the Supreme Court of India, has been instrumental in the interpretation of these treaty shifts. Recent observations from the Supreme Court highlight the judiciary’s recognition of the government’s efforts to plug revenue leaks. By validating the shift from residence-based to source-based taxation, the court has provided legal certainty to these international agreements. This judicial backing is crucial for maintaining investor confidence, as it signals that the tax regime is governed by a consistent interpretation of international law that balances sovereign rights with the obligations inherent in bilateral treaties.
For corporations and tax advisors, the jurisprudence surrounding these treaties has become a vital component of strategic planning. It is no longer sufficient to look at treaty benefits in isolation; one must also account for the evolution of interpretative standards. The Supreme Court’s focus on the spirit and intent of the 2016 Mauritius protocol reinforces the reality that tax policy is becoming increasingly integrated with global compliance expectations.
Future Outlook for India’s Tax Policy
Looking ahead, the focus of India’s fiscal policy will likely remain on transparency and administrative efficiency. As the global tax environment continues to grapple with the digital economy and the taxation of intangible assets, India’s experience in renegotiating its traditional investment treaties provides a blueprint for future policy design. The emphasis is transitioning from defensive tax collection to a more proactive model that supports a dynamic, growing economy.
India’s integration into the global financial system is now characterized by a blend of openness and prudence. By ensuring that taxation happens where wealth is generated, the government is not only protecting its revenue streams but also ensuring that the growth of the Indian corporate sector translates into meaningful fiscal support for the country’s infrastructure and development goals. As the tax landscape continues to harmonize with global standards, the long-term benefits of this rigorous approach will likely outweigh the costs of compliance, ultimately cementing India’s status as a stable and reliable destination for international institutional capital.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News