Strategic Scaling: The Future of India’s Rooftop Solar Landscape
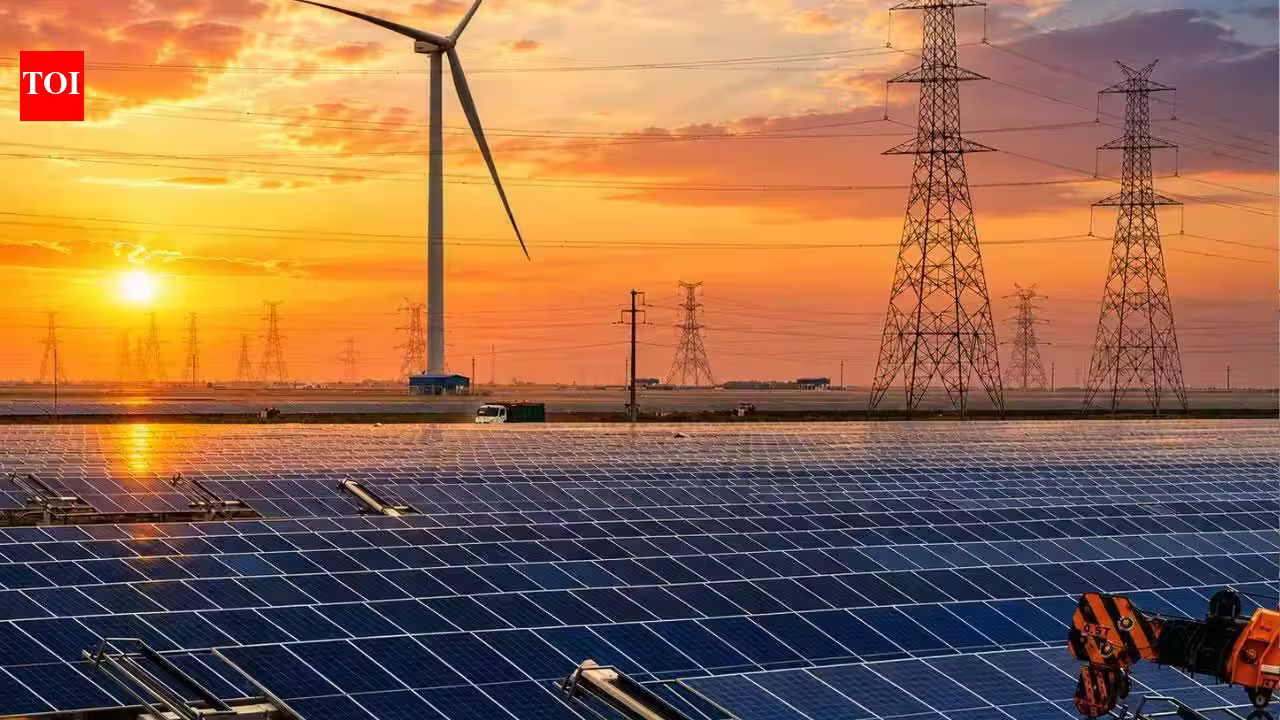
The Indian energy sector is currently witnessing a structural transformation defined by the transition toward decentralized power generation. The Indian Solar Manufacturers Association (ISMA) has recently released a comprehensive outlook estimating that the country’s rooftop solar market holds the potential to expand from its current capacity of approximately 17 GW to 132 GW by 2030. This projection represents a massive leap in decentralized energy infrastructure, suggesting an annual demand trajectory of 9 to 15 GW over the next several years. For policymakers, investors, and industrial stakeholders, this shift signifies more than just an increase in generation capacity; it marks the maturation of a domestic manufacturing ecosystem designed to meet the rigors of a rapidly expanding residential market.
The assessment conducted by ISMA relies on a multifaceted analysis of national residential electricity consumption patterns, housing demographics, and the prevailing tariff structures of distribution companies (DISCOMs). By aligning these variables, the industry can pinpoint regions where the economic feasibility of solar adoption is highest, while simultaneously identifying the policy levers required to incentivize growth in more challenging markets. As residential power demand continues to outpace traditional grid supply, rooftop solar is evolving from a niche financial incentive into a critical component of national energy security and household cost management.
The Role of Policy Frameworks in Market Acceleration
A significant driver behind the current momentum is the PM Surya Ghar Muft Bijli Yojana, a flagship central government initiative launched in February 2024. This program, which seeks to provide rooftop solar systems to one crore households by March 2027, has fundamentally altered the adoption curve. The government has already disbursed over Rs 31,515 crore in central financial assistance, a figure that underscores the scale of federal commitment. To date, nearly 56.9 lakh families have benefited from these installations, bringing the total capacity to approximately 16.8 GW.
The success of this scheme serves as a template for how targeted fiscal support can overcome the upfront capital barriers that have historically hindered solar penetration in the middle-income residential sector. By subsidizing the installation cost, the government has stimulated demand in regions where traditional project economics would otherwise be unfavorable. This “affordability effect” has effectively democratized access to solar energy, moving the market away from its historical concentration in states with high commercial tariffs toward a more widespread, nationwide adoption model. The ability of the scheme to stimulate consumer demand has, in turn, created a predictable, long-term order book for domestic manufacturers of solar cells, modules, inverters, and balance-of-system components.
Building a Robust Domestic Manufacturing Ecosystem
The projected scale of 132 GW creates an unprecedented opportunity for the domestic solar manufacturing sector. As demand shifts from large-scale utility solar projects to decentralized rooftop applications, the supply chain must adapt to support smaller, distributed, and highly reliable technical specifications. ISMA’s report highlights that this growth is expected to trigger increased investments in domestic production lines. For Indian manufacturers, this is an opportunity to reduce reliance on imported components, thereby enhancing the resilience of the national energy infrastructure.
Maintaining this growth requires a concerted focus on the domestic supply chain. The proliferation of rooftop systems necessitates a vast network of service providers, installers, and component manufacturers who are equipped to handle diverse residential configurations. Furthermore, the push for “Made in India” solar products aligns with national strategic goals aimed at reducing the current account deficit and enhancing industrial self-reliance. As capacity expands, the focus is shifting toward economies of scale, vertical integration of manufacturing facilities, and the adoption of advanced cell technologies to ensure that rooftop installations deliver peak efficiency throughout their multi-decade lifespans.
Ensuring Market Continuity Beyond 2027
While the current policy environment is highly supportive, the industry faces the challenge of maintaining momentum beyond the expiration of the PM Surya Ghar Muft Bijli Yojana in March 2027. Market stakeholders emphasize that regulatory visibility is the primary determinant of long-term capital expenditure. Investors and manufacturers require assurance regarding future subsidy structures, grid integration norms, and net-metering policies to justify multi-year investments in production capacity and distribution networks.
ISMA’s suggestion regarding the development of a “PM Surya Ghar 2.0” framework, with clarity provided by December 2026, reflects the need for a seamless transition. A predictable policy horizon prevents the “boom-and-bust” cycles that often plague government-led initiatives. For manufacturers, early communication of the next phase of support allows for synchronized capacity expansion and inventory planning. Furthermore, as the market matures, the transition from heavy subsidy dependence to market-driven adoption will require the development of innovative financing models, such as solar-specific credit lines, easier access to banking loans, and simplified administrative processes for grid connectivity.
Economic Impacts and Future Outlook
The economic impact of achieving the 132 GW milestone extends far beyond the energy sector. It translates into significant job creation across the manufacturing, installation, and maintenance value chains. By empowering households to become “prosumers”—producers and consumers of their own electricity—the government is effectively reducing the fiscal burden on state-owned DISCOMs, which often struggle with the cross-subsidization of residential consumers. Reducing the technical and commercial losses of the grid through decentralized generation offers a structural improvement to the financial health of the power distribution sector.
Looking ahead, the convergence of technological advancements, such as high-efficiency bifacial modules and integrated smart inverters, with favorable policy regimes creates a unique environment for sustained growth. However, the industry must remain vigilant regarding global supply chain volatility and the price of raw materials like polysilicon. The success of India’s rooftop solar vision will ultimately depend on the ability of local manufacturers to balance competitive pricing with quality assurance. As the market moves toward 2030, the rooftop solar sector is set to become one of the most critical pillars of India’s broader climate commitments and its economic development strategy, reinforcing the nation’s position as a global leader in the clean energy transition. By institutionalizing support and fostering a stable manufacturing environment, India is well-positioned to transform its rooftops into a decentralized, reliable, and sustainable power plant that serves millions of citizens.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News