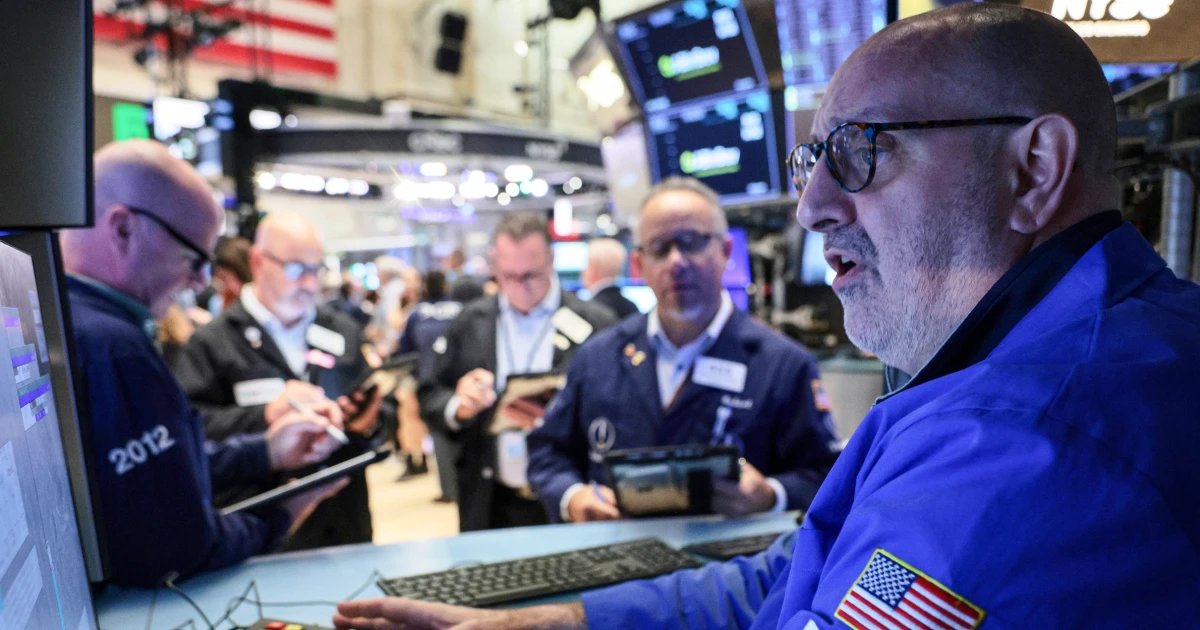
Tech markets suffered a brutal setback on Friday, with investors wiping more than $1 trillion in market capitalization from the sector as macroeconomic anxieties reached a fever pitch. A resurgence in energy costs, coupled with a growing skepticism toward the massive capital expenditures surrounding artificial intelligence, led to a broad-based sell-off across major indices.
The Nasdaq 100, the primary barometer for the country’s leading tech and AI-focused firms, tumbled 2.5%, leaving the index roughly 7% below the record highs it established just one week prior. The carnage was felt across the board, with the S&P 500 falling 1% and the Russell 2000 retreating 1.6%. Perhaps most concerning was the performance of the semiconductor sector; the Philadelphia semiconductor index logged a 3.8% decline, marking its eighth consecutive day of losses—the longest downward streak for the industry since the 2008 financial crisis.
## The Energy Price Shock
The catalyst for Friday’s turbulence was a sharp climb in global energy costs. Brent crude breached the $110-per-barrel mark, its highest valuation since May, while U.S. West Texas Intermediate (WTI) climbed 3.5% to settle at $101.41.
Fuel prices have been on a volatile path for months, fueled initially by regional instability in the Middle East following the Strait of Hormuz closure earlier this year. However, the situation has been exacerbated by the escalating Russia-Ukraine conflict. Persistent strikes on Russian energy infrastructure have significantly hampered the nation’s refining capacity, particularly regarding diesel production. With domestic refineries in the U.S. and Europe already operating at maximum capacity, there is little room to bridge the supply gap, keeping inflationary pressure high as the November 3 midterm elections approach.
## AI Growth Model Faces Scrutiny
While energy prices drive the inflation narrative, the tech industry is simultaneously grappling with a crisis of confidence regarding its massive pivot toward AI. For months, the market has rewarded companies that poured billions into high-speed data centers and proprietary AI models. However, that enthusiasm is waning as investors demand evidence of sustainable returns on these massive capital outlays.
The data center sector bore the brunt of this pivot in sentiment on Friday. CoreWeave and Nebuius emerged as the worst performers in the Nasdaq 100, reflecting a broader hesitation among institutional investors. CoreWeave, in particular, has seen its share value erode by over 25% in the last month alone.
Market analysts, including Ed Yardeni, have begun adjusting expectations downward. Citing “rising investor caution” regarding the AI trade, Yardeni recently slashed his year-end target for the S&P 500 from 8,400 to 7,900. The core issue remains a disconnect: major tech firms are taking on significant debt to fuel AI expansion at the exact moment that high interest rates are making borrowing more expensive and less sustainable.
## Political Instability and Market Outlook
The path forward remains murky as the intersection of geopolitics and fiscal policy creates a “perfect storm” for investors. President Donald Trump has faced mounting pressure to lower diesel prices, with his administration touting a potential deal with Russia as a solution. Yet, the proposal faces stiff resistance in Congress and has failed to produce any tangible cooling of prices on the global market.
Looking toward 2027, the outlook is characterized by uncertainty. Mason Mendez, a global real assets analyst at Wells Fargo, noted that the necessity of replenishing depleted global energy inventories could keep commodity prices elevated for years. With the Federal Reserve signaling that inflation—stoked by these high energy costs—could necessitate further interest rate hikes, the “easy money” era that powered the rapid AI gold rush appears to be coming to a sharp, difficult end.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News