Decoding the Reserve Bank of India’s Strategic Forex Intervention
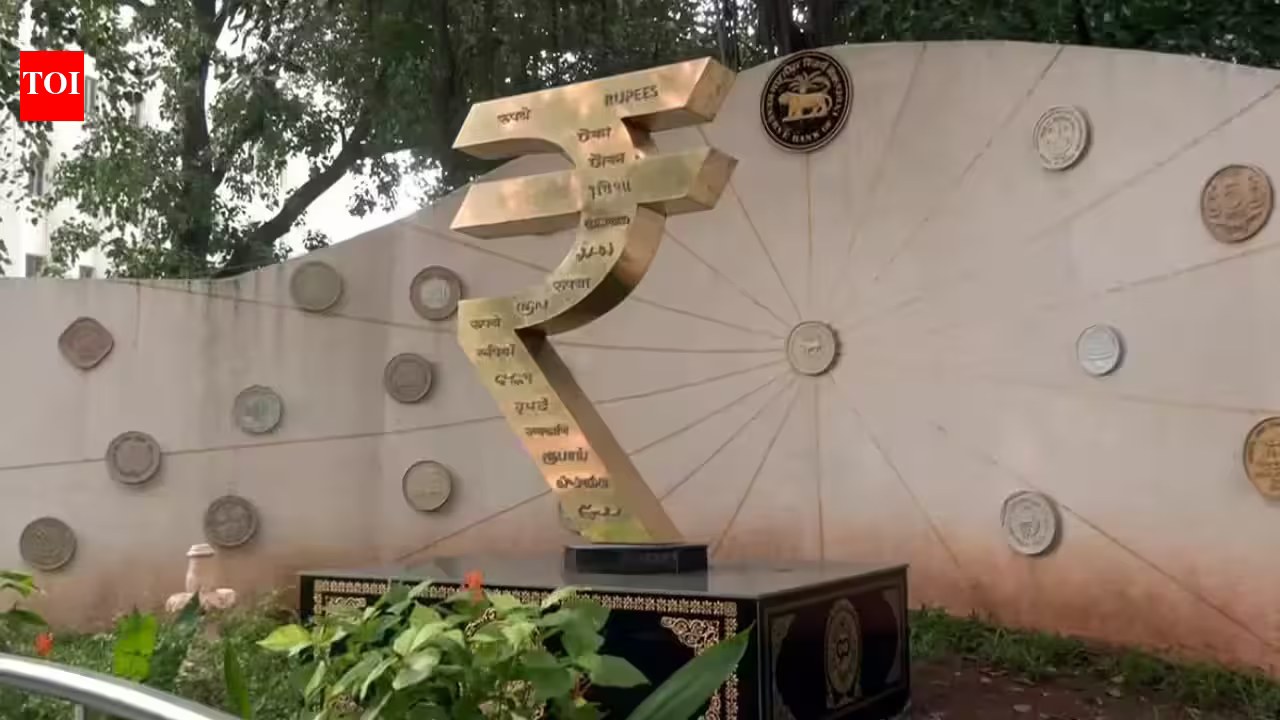
The Reserve Bank of India (RBI) recently implemented a suite of regulatory measures aimed at stabilizing the Indian rupee, which has faced sustained pressure from global macroeconomic headwinds. By tightening the framework governing foreign exchange derivative transactions, the central bank is proactively addressing speculative dollar demand and enhancing market discipline. These circulars, issued in early October, signify a shift toward a more rigorous oversight of currency derivatives, specifically targeting contracts linked to the rupee.
The primary objective of these regulatory changes is to curb volatility in the domestic currency market. By restricting the ability of market participants to rebook cancelled contracts and lowering the threshold for establishing underlying exposure, the RBI is effectively narrowing the scope for speculative trading. These measures are designed to ensure that the foreign exchange market remains a tool for genuine risk management rather than a vehicle for unbridled currency betting. As the Indian economy navigates a complex global landscape, these interventions serve as a stabilizer, providing the central bank with greater control over the forces influencing the rupee’s trajectory.
Structural Changes to Derivative Market Regulations
The core of the RBI’s latest policy shift lies in the technical adjustments to how banks and corporate entities interact with forex derivatives. A critical change introduced by the regulator is the prohibition on rebooking cancelled rupee-linked derivative contracts. While rollovers remain permissible at maturity, the inability to rebook provides a deterrent against those attempting to trade on short-term fluctuations without a legitimate hedge requirement.
Furthermore, the central bank has significantly lowered the threshold for conducting derivative transactions without proof of underlying exposure, moving from 100 million dollars to 5 million dollars. This move forces a larger segment of the market to provide evidence of genuine trade or investment-related exposure before entering into a derivative contract. Perhaps the most impactful change is the introduction of the Foreign Exchange Risk Reserve (FERR). Authorized dealers must now maintain a cash reserve with the RBI equivalent to 20 percent of the notional value of specific rupee-linked derivative contracts exceeding 2 million dollars. This mandatory reserve requirement acts as an implicit tax on hedging, thereby increasing the cost of speculative transactions while ensuring that dealers maintain higher liquidity buffers for their derivative portfolios.
The Economic Impact of Increased Hedging Costs
By introducing the FERR and tightening contract rules, the RBI has effectively increased the cost of hedging for corporate entities and importers. Industry estimates suggest that these measures could lead to a rise in hedging costs ranging between 1 percent and 1.6 percent. While this may appear as a burden on importers, the structural intent is to discourage over-hedging and reduce the artificial demand for dollars in the spot market.
When the cost of hedging increases, market participants are compelled to be more precise with their risk management strategies. This transition is expected to alleviate some of the pressure on the rupee, as the reduction in speculative dollar demand directly impacts the spot market exchange rate. Analysts at leading financial institutions have noted that these measures could steer the USD/INR pair toward more favorable levels, at least in the short term. However, the efficacy of these measures remains tied to broader economic factors. Elevated crude oil prices, which constitute a significant portion of India’s import bill, continue to dictate the demand for foreign currency. Consequently, while the RBI’s regulatory framework provides a cushion against volatility, the medium-term outlook for the rupee will still be heavily influenced by India’s balance-of-payments dynamics and the global performance of the dollar against a basket of currencies.
Liquidity Management and the Monetary Policy Outlook
Beyond currency stability, the RBI’s forex measures serve an auxiliary purpose: the withdrawal of surplus liquidity from the domestic banking system. Excess liquidity has been a recurring challenge for the central bank, often complicating its inflation-targeting efforts. By requiring authorized dealers to hold a portion of their derivative contract values in cash with the RBI, the regulator is effectively absorbing liquidity that would otherwise circulate within the banking system.
Financial analysts project that these measures, combined with other liquidity-draining operations such as open market bond sales, will contribute to a significant contraction in core liquidity. Estimates suggest that the durable liquidity surplus could shrink substantially as these rules persist. This tightening of liquidity aligns with the RBI’s broader monetary policy stance. By managing liquidity through both traditional policy tools—such as the repo rate—and these specific forex-related interventions, the central bank gains more flexibility. If these measures successfully dampen speculative volatility, the RBI may be able to adopt a more calibrated approach to future interest rate adjustments, balancing the need for inflation control with the requirement for supporting domestic growth.
Market Discipline and the Future of the Rupee
The RBI’s recent actions underscore a commitment to maintaining an orderly and transparent foreign exchange market. In the context of the Indian economy, where currency fluctuations can have a profound impact on imported inflation and capital flows, the role of the central bank as a vigilant regulator is paramount. By prioritizing market discipline, the RBI is creating a system where participants are held accountable for their risk-taking behaviors.
Looking ahead, the success of these measures will depend on the interplay between domestic regulatory constraints and external global variables. While the rise in hedging costs is an immediate consequence, the long-term benefit is a more resilient currency market that is less susceptible to abrupt capital outflows and speculative attacks. For corporate treasuries and institutional investors, the operating environment has become more stringent, necessitating a shift toward more disciplined and evidence-based hedging practices.
As India continues to integrate further into the global economy, the ability of the RBI to strike a balance between allowing market forces to determine the rupee’s value and preventing excessive volatility will be the defining factor of its monetary management. The current suite of measures represents a calculated effort to navigate these challenges, ensuring that while the rupee remains subject to the realities of the global financial order, it does so within a framework that protects the integrity of the Indian domestic market.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News