The Mechanics of Currency Stability in Emerging Markets
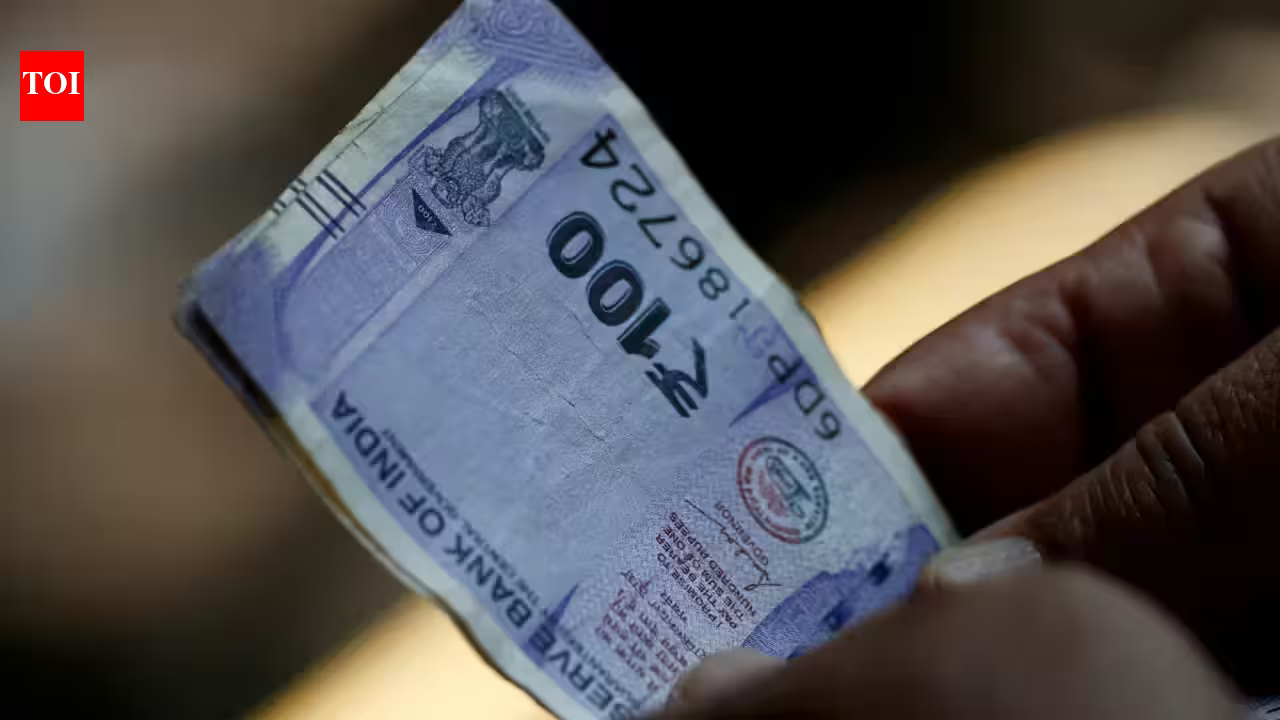
The recent performance of the Indian rupee, characterized by a streak of gains against the US dollar, provides a lens through which to observe the delicate interplay between central bank policy and global macroeconomic shifts. When the rupee gains value, it is rarely the result of a single factor; rather, it is the outcome of calculated interventions by the Reserve Bank of India (RBI) combined with external global market shifts. For businesses operating in India, whether they are exporters, importers, or multinational corporations with significant local capital expenditure, currency volatility remains a primary risk variable.
Currency stability is not merely a macroeconomic abstraction; it is the bedrock of predictable international trade. When the RBI intervenes to curb speculative bets, it is essentially providing a buffer that prevents extreme price discovery from disrupting trade flows. In an emerging market context, speculative exposure can lead to rapid capital outflows, which in turn drain foreign exchange reserves and inflate the cost of imported goods. By signaling a commitment to curbing excessive speculation, the central bank helps maintain a stable interest-rate environment, which is crucial for domestic credit growth and business expansion.
The Role of RBI Interventions in Market Sentiment
The recent appreciation of the rupee, supported by targeted RBI measures, illustrates the central bank’s strategy of smoothing out volatility rather than dictating a fixed exchange rate. Modern central banking in India has moved toward a more nuanced approach. The objective is not to fight market forces but to prevent disorderly conditions that arise from speculative excess. When traders perceive that the central bank is actively monitoring the liquidity of the forex market and tightening the rules for speculative activity, the ability of hedge funds and institutional players to push the currency in one direction is significantly diminished.
For the Indian corporate sector, this period of relative strength provides a temporary relief from the cost of imported raw materials. However, analysts remain cautious about the long-term sustainability of such gains if they are decoupled from fundamental economic productivity. The RBI’s intervention serves as a necessary anchor, but business leaders must look beyond daily movements and consider the underlying fiscal balance. When the central bank absorbs dollar supply or manages demand to stabilize the rupee, it also preserves the country’s reputation as a stable destination for foreign direct investment (FDI), which remains the most reliable driver of long-term currency strength.
Global Macroeconomic Drivers and US Treasury Yields
While domestic policy provides the framework for stability, the Indian rupee remains deeply tethered to the global financial system. The correlation between the US Treasury yields and the value of the rupee is a critical indicator that financial directors must watch. When US yields decline, emerging markets often see a return of capital, as global investors seek higher yields in growth-oriented economies. This influx of capital naturally supports the rupee. Conversely, when US yields spike, capital tends to move back toward the safety of the dollar, placing downward pressure on currencies like the rupee.
Recent trends suggest that as global inflation expectations stabilize and the US Federal Reserve signals a change in its rate path, the pressure on the dollar eases. This creates a more favorable environment for the Indian rupee. However, Indian businesses should not mistake this trend for a permanent decoupling. The dollar remains the global reserve currency, and any sudden geopolitical shock or shift in US domestic monetary policy can quickly reverse the gains observed in the interbank market. Therefore, the strategy for Indian firms should remain focused on natural hedging—matching foreign currency inflows with outflows—rather than relying on temporary currency appreciation to boost margins.
Impact on Domestic Markets and Trade Balances
The relationship between a stronger rupee and domestic stock market performance is complex. While a stable currency is generally positive for long-term sentiment, the recent market data indicates that weak domestic equities can sometimes cap the gains of the currency. When domestic markets underperform, foreign institutional investors (FIIs) may trim their holdings, creating a structural outflow of dollars that negates the positive impact of a weakening US greenback.
For the Indian exporter, particularly in sectors such as software services, pharmaceuticals, and engineering goods, a strengthening rupee presents a dual-edged sword. On one hand, it lowers the cost of importing machinery and raw materials, potentially improving production efficiency. On the other, it reduces the rupee value of foreign-denominated export contracts, which can compress profit margins if those firms lack pricing power. In this environment, the burden falls on management to improve operational efficiency. Relying on favorable exchange rates is an unreliable business strategy; instead, focusing on moving up the value chain—where goods and services are less sensitive to price changes—is the most effective way to insulate a business from currency fluctuations.
Strategic Hedging in a Volatile Currency Landscape
The recent performance of the rupee serves as a reminder to corporate finance departments about the necessity of sophisticated risk management. In an environment where the RBI is actively intervening to temper speculation, the intraday volatility can be significant. Companies that fail to account for these fluctuations in their quarterly projections often find their earnings affected by “forex losses” that have nothing to do with their core business performance.
Corporate treasuries in India have increasingly adopted a multi-layered approach to currency risk. This includes using forward contracts to lock in exchange rates for future import or export settlements, ensuring that the company’s cost of goods sold remains predictable. Furthermore, companies with cross-border operations are increasingly looking at “netting” their exposures, where foreign currency receivables and payables are set off against each other to minimize the need for external conversion. In a market where the regulator—the RBI—is a primary player, businesses that align their treasury operations with the prevailing policy direction are far more likely to maintain consistent financial performance.
The Outlook for the Indian Currency Market
Looking ahead, the stability of the rupee will likely depend on the balance between domestic growth and external global liquidity. If India continues to attract significant FDI and sustains its growth trajectory, the rupee is likely to remain resilient against global headwinds. However, as long as the global economy remains sensitive to US interest rates, the rupee will periodically face tests.
The primary takeaway for stakeholders is that the RBI’s influence is the dominant factor in preventing the “worst-case” scenarios of currency depreciation. This provides a safety net that many other emerging economies lack. Nevertheless, business strategy must remain rooted in fundamental economic health. Whether the rupee trades at 94 or 96 against the dollar, the companies that thrive are those that maintain a disciplined approach to capital allocation, minimize unnecessary forex exposure, and focus on generating intrinsic value rather than chasing currency gains. As the market continues to evolve, the capacity to digest and respond to these regulatory signals will define the competitive advantage of Indian enterprises on the global stage.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News