The Dynamics of the Indian Rupee in a Volatile Global Landscape
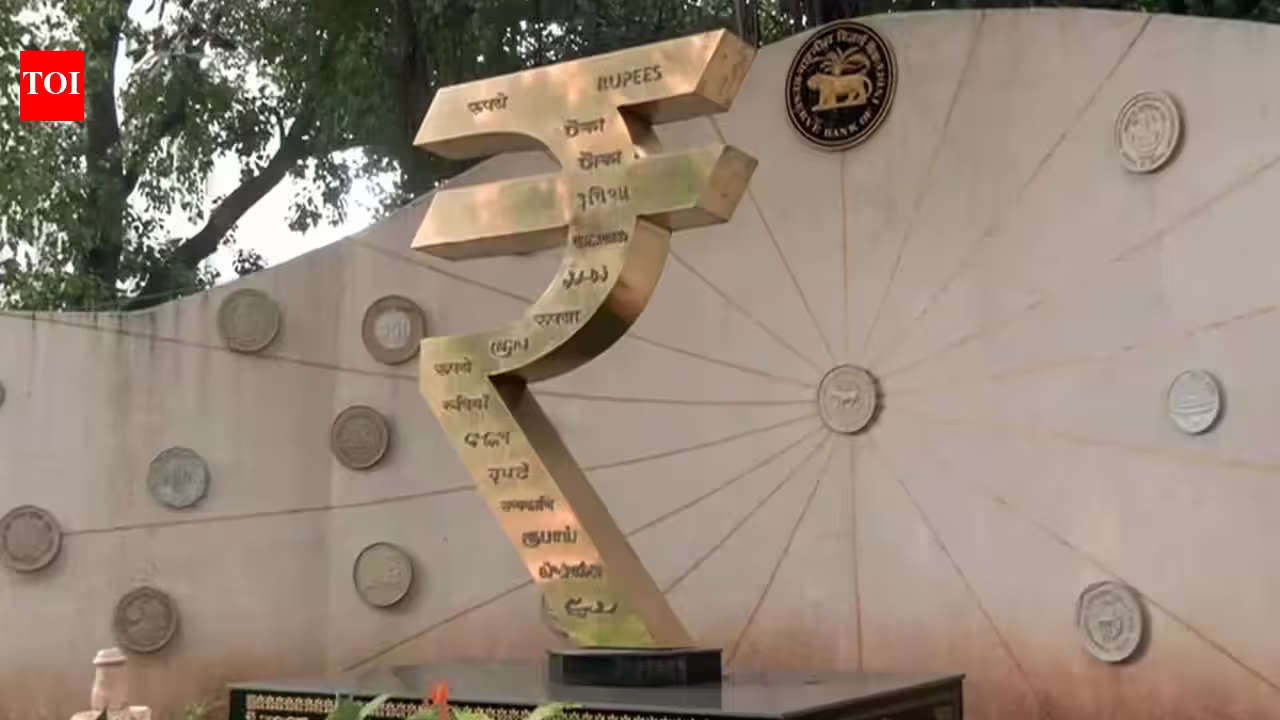
The Indian rupee recently demonstrated a notable recovery, gaining 33 paise against the US dollar to close at 94.93. This shift, driven by a weakening dollar index and resilient domestic equity markets, highlights the complex interplay between internal economic health and external global pressures. While a single trading session’s performance offers a moment of relief for importers and policymakers, the broader narrative of the rupee remains tethered to deep-seated structural and geopolitical variables. As the domestic currency navigates these currents, it serves as a barometer for India’s economic endurance in an era of heightened global uncertainty.
The recent gain is largely attributed to the softening of the US dollar index, which tracks the greenback against a basket of major currencies. When the dollar index retreats, emerging market currencies typically find room to breathe. Simultaneously, the positive momentum in Dalal Street—with the Sensex and Nifty indices registering gains—indicates sustained investor confidence in India’s growth story. However, this optimism is tempered by the looming presence of elevated crude oil prices and ongoing geopolitical tensions. In the Indian context, where the energy import bill is a primary driver of the current account deficit, the price of Brent crude is perhaps the most significant determinant of the rupee’s long-term stability.
Understanding the Mechanics of Currency Depreciation and Support
The value of the Indian rupee is never determined by a single factor but is instead the result of a delicate equilibrium. Historically, the rupee faces downward pressure when global risk appetite wanes, leading foreign institutional investors (FIIs) to withdraw capital from emerging markets. Recent data showing FIIs as net sellers underscores this reality. When capital flows out of the equity market, the demand for local currency drops, necessitating a more proactive approach to maintain stability.
This is where the role of the Reserve Bank of India (RBI) becomes critical. The central bank frequently intervenes in the foreign exchange market to prevent excessive volatility. While such interventions are essential to provide market liquidity and curb speculative attacks, they often spark debate among international institutions. The International Monetary Fund (IMF) has recently advocated for greater exchange rate flexibility, suggesting that the rupee should serve as the primary shock absorber for the economy. The logic is that by allowing the currency to fluctuate naturally, the economy can better adjust to external shocks, such as shifts in global energy prices or changes in US monetary policy. Yet, for an emerging economy like India, the fear of “imported inflation”—where a weaker rupee makes essentials like fuel and electronics more expensive—often forces the hand of regulators to prioritize stability over absolute flexibility.
The Persistent Challenge of Energy Imports and Geopolitics
Energy security is the central pillar upon which India’s currency stability rests. As one of the world’s largest importers of crude oil, India’s foreign exchange reserves are constantly under pressure to meet the requirements of refineries. Even minor fluctuations in the price of a barrel of Brent crude translate into billions of dollars in outflows. When global supply chains are disrupted by Middle Eastern conflicts or supply-side constraints, the rupee inevitably faces pressure.
Furthermore, geopolitical tensions are currently at the forefront of market anxiety. Recent warnings regarding potential strikes in the Middle East have injected a level of risk premium into the financial markets. Investors look for “safe-haven” assets, which historically strengthens the US dollar and puts the rupee at a disadvantage. Consequently, analysts anticipate that the currency will continue to trade with a negative bias or within a defined, narrow range. This technical range-bound movement is designed to mitigate the risks of abrupt volatility, allowing domestic businesses to plan their international trade with at least some degree of predictability.
Balancing Monetary Policy and Institutional Expectations
The broader economic environment in which the rupee operates is heavily influenced by the interest rate environment in the United States. When the US Federal Reserve maintains higher rates, US Treasury yields become more attractive, drawing capital away from Indian assets. This scenario presents a dual challenge: the central bank must manage the rupee’s value while also ensuring that domestic interest rates remain conducive to local economic growth.
The RBI’s balancing act involves a mix of monetary policy tools, including repo rate adjustments and foreign exchange reserves management. While foreign reserves are currently at healthy levels, providing a buffer against speculative shocks, they are not infinite. The challenge lies in utilizing these reserves effectively without signaling to the market that the central bank is aiming to “peg” the currency at an artificial level. Market participants closely watch the RBI’s actions, as these interventions signal the tolerance level for currency depreciation before the bank steps in to provide support. For domestic corporations, understanding these institutional signals is vital for hedging against foreign exchange risk.
Strategic Outlook for Investors and Businesses
Looking ahead, the trajectory of the Indian rupee will be defined by the confluence of domestic performance and external demand. If India continues to exhibit strong GDP growth and stable inflation figures, the inherent attractiveness of the Indian market may counter the pressure exerted by global factors. However, companies heavily reliant on imports must prepare for continued volatility. The expectation that the rupee will trade between the 94.80 and 95.35 range against the dollar in the near term suggests that while the currency has recovered, it is far from entering a phase of sustained appreciation.
For businesses, the current market climate necessitates a robust risk management framework. Relying on organic growth is no longer sufficient when currency fluctuations can erode margins overnight. Companies are increasingly turning toward sophisticated hedging instruments to lock in costs and protect their bottom lines from the vagaries of the foreign exchange market. Furthermore, as the debate between fixed and flexible exchange rates continues at the policy level, businesses must remain agile, diversifying their supply chains and reducing dependence on energy-intensive operations where possible.
In conclusion, the rupee’s recent performance is a testament to the resilience of the Indian market despite a difficult global backdrop. While the intervention of the central bank and the softening of the dollar provide temporary support, the long-term health of the currency remains tied to the nation’s ability to manage its trade deficit and navigate the treacherous waters of global geopolitics. As India cements its position as a major global economic force, the rupee will naturally face increased scrutiny and pressure, making transparency and adaptive monetary strategy more important than ever.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News