The Resilience of Small Savings in an Equity-Driven Market
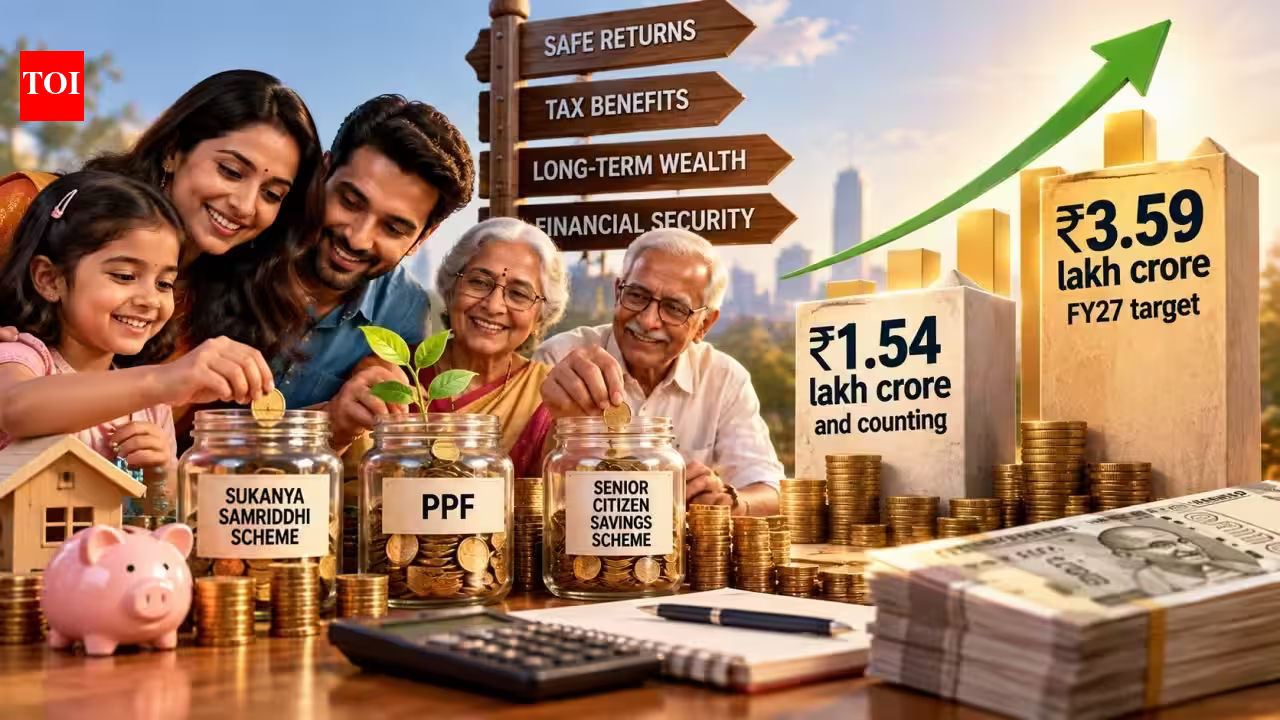
The Indian financial landscape is currently witnessing a fascinating dual trend. On one hand, retail participation in the equity markets through direct stocks and systematic investment plans (SIPs) has reached unprecedented levels. On the other, the traditional bedrock of household savings—government-backed Small Savings Schemes (SSS)—continues to exhibit remarkable growth. Data for the first four months of the current fiscal year reveals that collections have surged, with inflows reaching Rs 1.54 lakh crore by July. This trajectory suggests that the government will comfortably surpass its initial collection target of Rs 3.59 lakh crore for the 2026-27 financial year.
While equities provide the potential for wealth creation, they are inherently linked to market volatility. In contrast, small savings schemes represent the “safe haven” of the Indian middle class. Instruments like the Public Provident Fund (PPF), Sukanya Samriddhi Yojana (SSY), and the Senior Citizens Savings Scheme (SCSS) offer a unique combination of capital protection, guaranteed returns, and, in many cases, favorable tax treatment. This reliability makes them a non-negotiable component of a balanced financial strategy for millions of households, regardless of how attractive the stock market may appear.
Drivers Behind the Surge in Government Savings
The primary engine behind the continued appeal of these schemes is the consistency of interest rates coupled with sovereign backing. With rates ranging from 6.9% to 8.2%, these instruments often outperform traditional bank fixed deposits, particularly when considering the tax-efficient nature of their returns. For the conservative Indian investor, the primary objective is the preservation of capital. During periods of economic uncertainty or market corrections, the predictable interest payouts of these government schemes provide a sense of financial stability that market-linked products simply cannot replicate.
Furthermore, the seasonal nature of these investments plays a significant role in annual collection figures. There is a marked uptick in inflows during the final quarter of the financial year as taxpayers look to maximize their deductions under Section 80C of the Income Tax Act. However, the current year’s data indicates a more structural shift in demand. The 56% increase in collections during the April-July period compared to the previous year suggests that small savings are being utilized as a foundational layer for long-term financial planning, rather than merely being a last-minute tax-saving exercise.
Strategic Importance for Sovereign Financing
From the perspective of macroeconomic management, the success of the National Small Savings Fund (NSSF) serves a dual purpose. Beyond providing a secure channel for public savings, these funds provide the central government with a reliable source of non-market financing. By mobilizing capital through these schemes, the government can effectively reduce its reliance on volatile debt markets to fund its fiscal deficit.
Recent adjustments to the government’s gross market borrowing estimates underscore the utility of these internal resources. By shifting some of its financing requirements toward the NSSF, the Centre gains greater control over its debt portfolio, insulating itself from the fluctuating interest rate environment of the open market. The ability to rely on domestic, retail-funded debt is a testament to the high degree of trust that the Indian public places in government-backed instruments. As the government continues to refine its fiscal strategy, the NSSF will likely remain a pillar of its funding model, providing a bridge between the surplus capital of the citizenry and the infrastructural needs of the state.
Evaluating the Primary Small Savings Instruments
To understand why these schemes maintain such a firm grip on the Indian investor, it is essential to examine their specific value propositions. The Public Provident Fund remains a preferred long-term vehicle, characterized by its fifteen-year tenure and the triple-tax-exempt status of its contributions, interest, and maturity proceeds. It is often regarded as the benchmark for disciplined, tax-advantaged retirement planning.
Similarly, specialized schemes target distinct demographics with tailored benefits. The Senior Citizens Savings Scheme provides retirees with a robust, high-interest-bearing vehicle that offers quarterly income, effectively addressing the need for regular cash flow in the post-employment phase. The Sukanya Samriddhi Yojana has seen widespread adoption as a mechanism for financing the long-term educational and marriage-related needs of a girl child. By offering interest rates that are consistently among the most competitive in the market, the government has successfully created a suite of products that align with the life stages and specific financial goals of the average Indian household.
The Future Landscape of Household Investments
As we look toward the remainder of the decade, the narrative that market-linked investments will completely displace traditional savings is proving to be premature. Instead, the market is moving toward a hybrid approach. Sophisticated Indian investors are increasingly utilizing a “core and satellite” strategy: keeping a significant portion of their corpus in stable, government-backed small savings schemes for long-term security, while utilizing equity funds to capture growth.
The trend in small savings collections for FY27 suggests that the government’s target will be breached by a significant margin, mirroring the overperformance seen in the previous fiscal year. This indicates that the appetite for safe, sovereign-backed returns is far from exhausted. Even as the digital transformation of Indian finance makes it easier to trade stocks and invest in mutual funds with a single click, the inherent human preference for guaranteed wealth preservation ensures that the NSSF will remain a critical entity for years to come.
Ultimately, the sustained growth of small savings schemes serves as a barometer for the underlying health of the Indian economy. It reflects a population that is increasingly financially literate, capable of distinguishing between the speculative nature of volatile markets and the long-term utility of guaranteed government investments. As long as these schemes continue to offer competitive, inflation-adjusted returns, they will remain the bedrock upon which Indian families build their financial legacies, ensuring that the government’s fiscal targets are not just met, but consistently exceeded.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News