The Mechanics of Unexplained Cash Deposits in Indian Tax Law
The Indian tax framework under the Income Tax Act, 1961, is designed to ensure transparency regarding the flow of capital within the economy. Section 69A of the Act serves as a vital tool for the Income Tax Department to scrutinize assets—including cash, bullion, or jewelry—that appear in a taxpayer’s ownership but lack a clearly documented source of acquisition. When a substantial cash deposit is detected in a bank account, particularly one that does not align with the individual’s reported income or known professional status, the Assessing Officer (AO) is empowered to treat such sums as unexplained money.
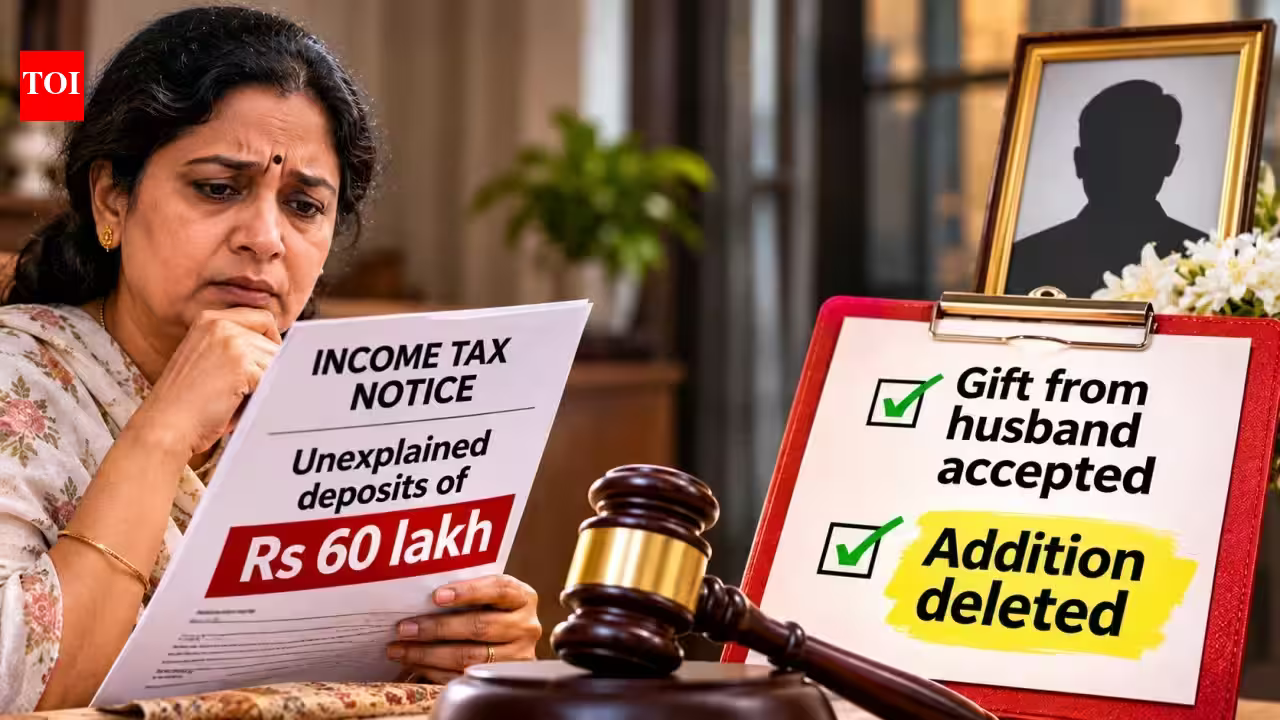
In the case of the widow recently adjudicated by the Income Tax Appellate Tribunal (ITAT) in Pune, the primary conflict arose from a significant cash deposit of over Rs 60 lakh. For the tax authorities, the absence of an income tax return (ITR) filing coupled with an unexplained large credit naturally triggered a suspicion of concealed income. The subsequent notices under Section 148A(b) represent the standard administrative response to financial inconsistencies detected via data analytics. This case highlights a critical tension: the requirement for individual documentation in an era where the government increasingly monitors banking activity to curb black money, versus the practical difficulties families face when primary breadwinners pass away, leaving behind complex financial legacies.
The Burden of Proof and the Role of Documentation
Under Indian tax law, the burden of proving the source of funds lies heavily on the taxpayer. When the Income Tax Department questions a credit, the assessee must provide a clear “trail” that identifies the donor, the relationship, and the capacity of the donor to make such a gift. In this specific legal battle, the taxpayer was a housewife without an independent income stream, which placed her at a disadvantage during the initial scrutiny. Without a pre-existing record of the financial transaction, the AO was technically correct to apply the provisions of Section 69A, as the funds existed in her account without a corresponding source description.
However, the case reveals that the tax authorities and the appellate bodies often look at the “substance over form” when the taxpayer makes a genuine effort to reconstruct the narrative. The widow’s submission of her late husband’s Permanent Account Number (PAN) details, death certificate, and written confirmations from her daughters were essential pieces of evidence. These documents shifted the perspective from “unexplained income” to a “family inheritance or gift.” The tribunal’s decision illustrates that even when a primary party is deceased, secondary evidence—such as family affidavits and consistent declarations—can satisfy the legal requirements to justify the source of capital, provided the department cannot prove these documents to be fabricated.
Judicial Interpretation and Protecting Family Assets
The ITAT Pune ruling provides a significant precedent for how Indian tax courts handle disputes involving deceased taxpayers. The tribunal took a pragmatic view by recognizing that the death of the primary donor creates an insurmountable obstacle for the survivor to obtain direct, contemporary testimony. By ruling in favour of the widow, the tribunal essentially signaled that Section 69A is not an automatic mechanism for taxation. It requires a logical application of facts. The judiciary acknowledged that the widow had met her initial burden of proof by identifying the donor and the context of the gift.
Crucially, the tribunal’s decision highlights that an absence of a formal gift deed does not necessarily invalidate a financial transaction, provided the surrounding circumstances and relationships are transparent. For many Indian households, financial dealings between spouses—often involving cash—remain informal due to long-standing cultural norms. However, as the digital transformation of the Indian economy accelerates, these informal traditions are increasingly coming into conflict with a digital-first tax system. The tribunal’s decision acts as a buffer, preventing the harsh application of tax penalties on funds that are clearly familial in nature rather than commercial or illicit.
Strategic Financial Management for Tax Compliance
The ordeal faced by the taxpayer serves as a stark reminder for Indian households to professionalize their financial record-keeping. The transition from informal cash-based gifts to formal banking channels is the most effective safeguard against future tax litigation. Expert legal counsel emphasizes that while the tribunal was lenient in this instance, relying on the benevolence of the court is not a sound financial strategy. Future transactions, particularly those involving high-value transfers, should exclusively utilize digital channels such as NEFT, IMPS, or RTGS. These methods generate permanent, immutable electronic records that bypass the need for lengthy explanation during an audit.
Beyond electronic transfers, the maintenance of a “financial dossier” is essential for every family. This includes not only legal certificates like death and succession certificates but also updated tax filings and investment records of the primary earning members. Registering as a legal heir on the official income tax portal is now a mandatory step for any survivor, as it provides seamless access to the deceased’s financial history, which is critical for defending the family’s asset base against future tax notices.
Proactive Governance in Personal Finance
In the current Indian economic climate, where the tax department relies on Artificial Intelligence and data matching to flag anomalies, the era of “informal silence” regarding finances has ended. Taxpayers must adopt a proactive approach to governance. This includes documenting gifts with simple, signed letters that outline the nature, date, and intent of the transfer, even within a marriage. While the ITAT Pune ruling was a victory for the taxpayer, the legal fees and time lost during the process represent a significant “hidden tax” in themselves.
The lesson is clear: legal compliance is not merely about filing tax returns; it is about maintaining a comprehensive trail of every significant movement of money. Families should ensure that their financial transition planning includes the consolidation of records, clear declarations of intent, and the conversion of physical cash holdings into formal financial assets. By doing so, families can avoid the scrutiny of the Income Tax Department and ensure that the legacy of a deceased relative serves its intended purpose for the beneficiaries, rather than becoming a point of contention within the bureaucratic process. The Pune tribunal’s decision is a validation of justice for a grieving family, but for the broader public, it should be viewed as a signal to prioritize financial documentation as a cornerstone of modern household management.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News