Understanding Tax Jurisprudence and the Right to Refund
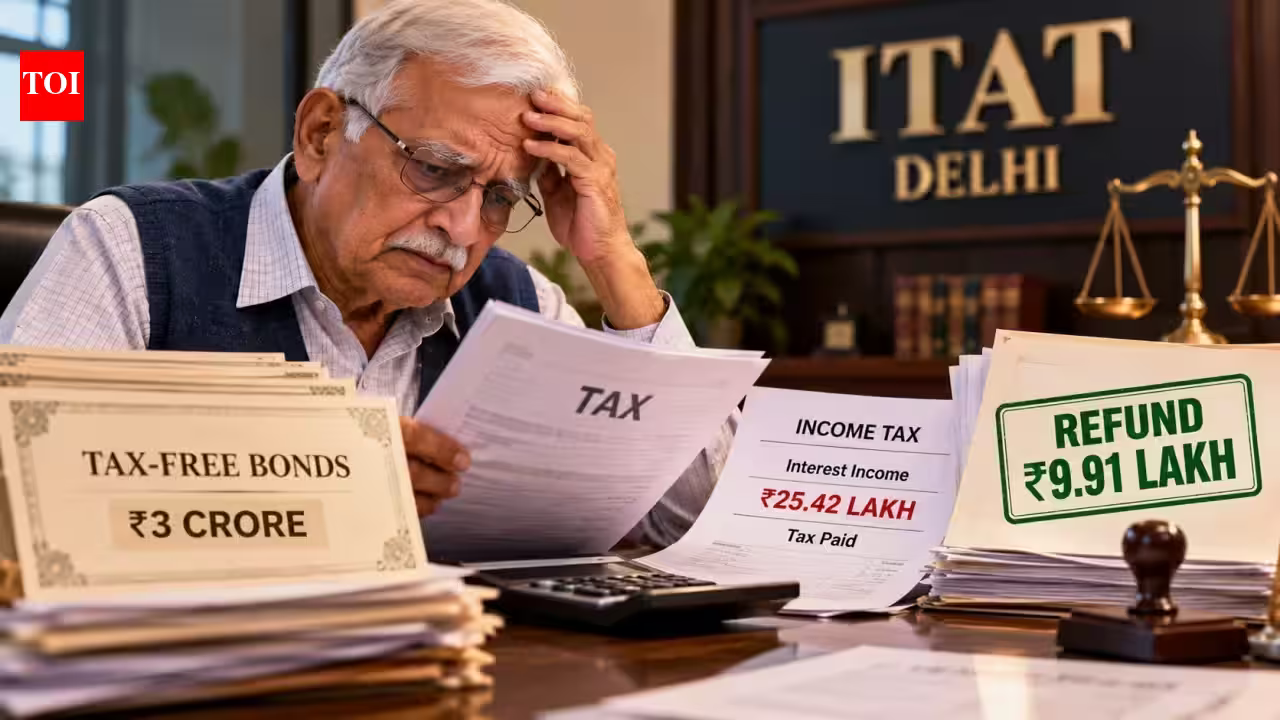
The recent ruling by the Income Tax Appellate Tribunal (ITAT) Delhi concerning a senior citizen’s erroneous tax payment serves as a vital reminder of the intersection between administrative proceduralism and the fundamental principles of justice in the Indian tax landscape. In this instance, a taxpayer inadvertently classified interest income from tax-free government bonds as taxable income, leading to an overpayment of nearly Rs 10 lakh. When the taxpayer sought a refund, the tax authorities initially denied the request, citing procedural limitations regarding the filing of revised returns.
The subsequent intervention by the ITAT reaffirms a critical concept: tax authorities have a mandate to collect only the revenue that is legally due to the state. The tribunal’s decision underscores that administrative barriers should not become a means to retain funds collected in error, especially when the tax-exempt status of the underlying income is clear under the Income Tax Act. This case highlights the importance of distinguishing between a “fresh claim” and the “rectification of an apparent error,” a distinction that often separates a successful refund plea from a rejected one.
The Mechanics of Tax-Free Bonds in India
To understand the significance of this case, one must look at the nature of the instruments involved. Tax-free bonds are debt securities issued by specified public sector undertakings (PSUs) in India, such as the National Highways Authority of India (NHAI), Rural Electrification Corporation (REC), and the India Infrastructure Finance Company Limited (IIFCL). These instruments are primarily designed to fund long-term infrastructure projects, offering investors a stable and predictable return.
Under Section 10(15)(iv)(h) of the Income-tax Act, 1961, the interest earned from these bonds is fully exempt from income tax, regardless of the amount or the tax bracket of the investor. For senior citizens who rely on fixed-income instruments to manage their retirement, these bonds are highly attractive as they provide an effective yield that is significantly higher than standard bank fixed deposits once the tax-adjusted returns are calculated. The core issue in the Delhi case was not the eligibility of the bonds, but the human error in reporting the income during the annual tax filing process. By treating the interest as “Income from Other Sources,” the taxpayer inadvertently waived his statutory exemption, a mistake that highlights the necessity of meticulous record-keeping and data verification in an increasingly digitized tax filing regime.
Navigating the Goetze (India) Precedent
The primary hurdle faced by the taxpayer was the reliance of the Assessing Officer (AO) on the Supreme Court judgment in the case of Goetze (India) Ltd. v. CIT. In that landmark ruling, the court held that an Assessing Officer does not have the authority to entertain a new claim for a deduction if it was not included in the original return or a revised return. The tax department frequently employs this precedent to reject requests for refunds that arise after the statutory deadline for filing a revised return has passed.
However, the ITAT Delhi distinguished the taxpayer’s situation from the Goetze precedent by classifying the error as a “mistake apparent from the record” rather than a “fresh claim.” While the Goetze ruling restricts the AO’s power to accept new deductions—such as claiming an expense that was previously missed—it does not strip the appellate authorities of their power to correct factual errors that result in illegal tax collection. This distinction is paramount for taxpayers. It suggests that while the window for voluntary, discretionary claims is narrow, the window for correcting fundamental clerical errors remains open, provided the taxpayer can demonstrate that the income was never taxable to begin with.
Constitutional Protections Against Illegal Levies
A compelling aspect of the ITAT’s verdict was its reliance on Article 265 of the Constitution of India. This article explicitly states that “no tax shall be levied or collected except by authority of law.” The tribunal’s invocation of this constitutional provision serves as a robust check against rigid bureaucratic processes. It reinforces the idea that the tax department, while tasked with revenue generation, is essentially a trustee of the taxpayer’s money.
When an Assessing Officer acknowledges that a particular sum of money was added to the taxable income in error, the continued retention of the resulting tax liability becomes a violation of the constitutional mandate. The ruling provides a sense of relief to taxpayers who fear that a simple oversight in an online portal—often driven by complex drop-down menus and ambiguous reporting categories—could lead to a permanent loss of capital. The decision serves as a judicial check on the “form over substance” approach that sometimes characterizes routine tax assessments, emphasizing that substance—the actual tax-exempt nature of the income—must prevail.
Lessons for Taxpayers and Financial Planning
For individual investors, particularly those in the senior citizen category, this case provides three critical takeaways for financial and tax management. First, it emphasizes the importance of thorough review during the filing process. Even with the introduction of the Annual Information Statement (AIS) and the Taxpayer Information Summary (TIS), which are designed to pre-fill tax returns, the responsibility of verifying the accuracy of income categorization remains with the taxpayer.
Second, it highlights the importance of the rectification process under Section 154 of the Income Tax Act. If a mistake is identified, the taxpayer should act promptly by filing a rectification request. While the ITAT provided a favorable outcome in this specific instance, relying on the appellate process is time-consuming and often requires professional legal or chartered accountant intervention.
Finally, the case underscores the value of professional guidance. A Chartered Accountant or tax advisor acts as the first line of defense in identifying discrepancies between the nature of an investment and its representation in an Income Tax Return (ITR). As tax authorities leverage artificial intelligence and data matching to scrutinize filings, the likelihood of being flagged for errors increases. Consequently, ensuring that the income classification in the ITR matches the tax-exempt status of the financial instrument is a fundamental part of responsible tax compliance.
Ultimately, the Delhi ITAT’s decision is a triumph of equity. It validates the principle that the tax system should function on transparency and fairness, and that taxpayers should not be penalized for accidental errors that do not alter the underlying tax liability. While this case ended in a refund, it serves as a cautionary tale: vigilance in filing is far superior to the arduous process of fighting for a correction after the fact.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News