The Mechanics of Tax Compliance and Data Accuracy
In the complex landscape of Indian taxation, the Income Tax Return (ITR) is more than just a formal declaration; it is a legal document that carries significant weight. Every entry, deduction, and exemption claimed reflects the taxpayer’s financial integrity. However, as the recent ruling by the Income Tax Appellate Tribunal (ITAT) Mumbai highlights, clerical errors in the filing process can lead to prolonged legal disputes and unnecessary financial stress.
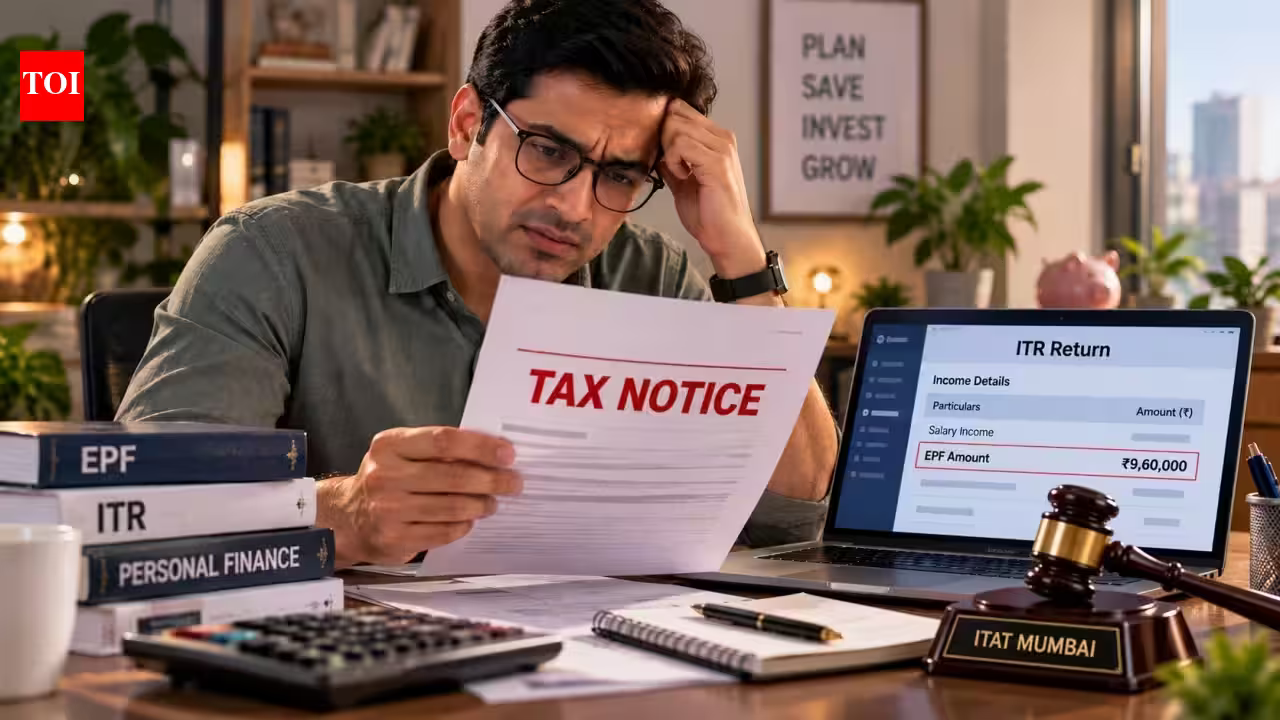
The case involved a taxpayer who erroneously declared Rs 9.6 lakh as exempt income under Section 10(11) of the Income Tax Act. Section 10(11) typically applies to payments received from statutory provident funds or notified government funds. Because the entry was misclassified and the taxpayer failed to provide immediate justification, the Assessing Officer (AO) added this amount to the taxpayer’s total taxable income, treating it as unexplained income. This situation underscores a critical reality in modern tax administration: the scrutiny applied by the Income Tax Department relies heavily on automated data reconciliation. When reported figures do not align with the taxpayer’s financial profile, the system triggers inquiries that necessitate a robust, evidence-backed defense.
The Burden of Proof in Tax Litigation
A core principle in tax law is that while the taxpayer has an obligation to provide accurate information, the Revenue authorities cannot sustain an addition to income based purely on a clerical anomaly without evidence of actual receipt. In this instance, the taxpayer’s struggle through the assessment and appellate stages stemmed from the presumption that the ITR entry was an admission of actual receipt.
The tribunal’s decision is significant because it clarified the limits of the Assessing Officer’s authority. The ITAT Mumbai observed that the Income Tax Department did not produce any evidence to show that the money had actually been credited to the taxpayer’s bank account or withdrawn from his EPF corpus. When the taxpayer presented a comprehensive set of documents—including Form 16, Form 26AS, bank statements, and a notarized affidavit—the onus of proof shifted back to the department. The ruling serves as a vital reminder for taxpayers: while an error in an ITR is a serious matter, it does not automatically equate to taxable income if the taxpayer can prove, through objective financial documentation, that the entry was factually impossible or non-existent in reality.
Understanding Section 10(11) and PF Regulations
The confusion in this case was compounded by a fundamental misunderstanding of the statutory provisions involved. The taxpayer, a private-sector professional, was covered under the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952. However, the exemption claimed under Section 10(11) pertains to payments from a Statutory Provident Fund governed by the Provident Funds Act, 1925, or specific notified government funds.
This discrepancy highlights the necessity for tax filers to understand the nature of their retirement accounts. In India, employees in the private sector are typically subject to different tax treatments regarding their Provident Fund contributions compared to their government counterparts. By attempting to claim an exemption under a section that was legally inapplicable to his employment status, the taxpayer inadvertently invited deeper scrutiny from the tax authorities. Professional tax filing is not merely about data entry; it is about the correct application of statutory law to the specific employment profile of the individual. As the ITAT noted, the AO’s initial premise for adding the tax was itself conceptually flawed, as it ignored the distinction between different classes of provident funds.
The Role of Documentation and Transparency
The taxpayer’s ultimate victory was achieved through the meticulous compilation of evidence. In an era where the Income Tax Department uses Artificial Intelligence and Data Analytics to cross-verify submissions, transparency and documentation are the taxpayer’s primary safeguards. By submitting Form 26AS—which tracks tax deducted at source and high-value transactions—alongside detailed bank reconciliations, the taxpayer provided an irrefutable trail of his financial activities.
The ITAT’s reliance on the taxpayer’s sworn affidavit further emphasizes the legal weight of a formal declaration. However, the ruling also cautions against relying on affidavits alone. The tribunal explicitly noted that the affidavit could not be disregarded unless the department produced evidence to the contrary, but it also pointed out that the department failed to offer any positive evidence of income receipt. This reinforces a key business insight: when navigating tax disputes, one must be prepared to reconstruct financial events with precision. If an entry is suspected to be an error, the response must not only explain the mistake but must also provide affirmative proof that the taxable event never occurred.
Strategic Takeaways for Indian Taxpayers
For professionals and business owners, this case offers several actionable insights regarding tax compliance and risk management. First, the importance of a pre-filing audit cannot be overstated. Even for salaried individuals with seemingly straightforward income streams, reviewing the final ITR draft before submission is essential to prevent data-entry errors. A simple typo or an incorrectly clicked exemption box can lead to years of litigation, which is costly in both time and legal fees.
Second, the taxpayer’s experience illustrates the risk of “automated suspicion.” When the department’s system flags an anomaly, the initial reaction from authorities is often to demand proof of the legitimacy of the entry. If the entry is indeed an error, the taxpayer must acknowledge it promptly and provide documentation to rectify the records before the assessment reaches an appellate stage. Waiting for a formal notice to explain a clerical error limits the taxpayer’s ability to maintain a cooperative posture with the department.
Finally, the ruling reaffirms that tax assessments must be based on reality rather than mere mechanical application of the law. While the Income Tax Department has the mandate to ensure that no income escapes taxation, it must also respect the factual financial reality of the taxpayer. The shift of the burden of proof to the department once credible, contradicting evidence is presented by the taxpayer is a standard that protects individuals from arbitrary tax burdens.
As digital systems become more entrenched in the Indian tax administration, the interface between software-driven assessment and human oversight will continue to evolve. Taxpayers must navigate this transition by prioritizing accuracy, maintaining robust documentation for all financial transactions, and seeking professional guidance to ensure that their statutory claims align perfectly with the legal provisions applicable to their specific employment status. By doing so, individuals can avoid the pitfalls of misplaced entries and ensure that their compliance record remains clean.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News