The Critical Role of Documentation in Business Asset Management
In the complex landscape of Indian taxation, the distinction between legitimate business income and unexplained wealth is often defined by the robustness of a taxpayer’s documentation. A recent landmark ruling by the Income Tax Appellate Tribunal (ITAT), Bengaluru, underscores that the mere presence of significant cash or assets in a private locker does not automatically invite punitive tax measures if the taxpayer can present a coherent, documented history of their financial activities.
For business owners operating in India, the case serves as a masterclass in the necessity of maintaining meticulous records. When the Income Tax Department conducts a search, the burden of proof initially rests on the taxpayer to explain the source of every asset. If a business owner fails to maintain a clear trail—linking cash reserves to recorded sales, commissions, or other business activities—they risk having their assets classified under Sections 69 and 69A of the Income Tax Act. These sections allow the tax authorities to treat such assets as “unexplained money” or “unexplained investment,” potentially subjecting them to the higher, special tax rates outlined in Section 115BBE, which can impose significant financial penalties alongside standard tax liabilities.
Navigating Income Tax Searches and Asset Classification
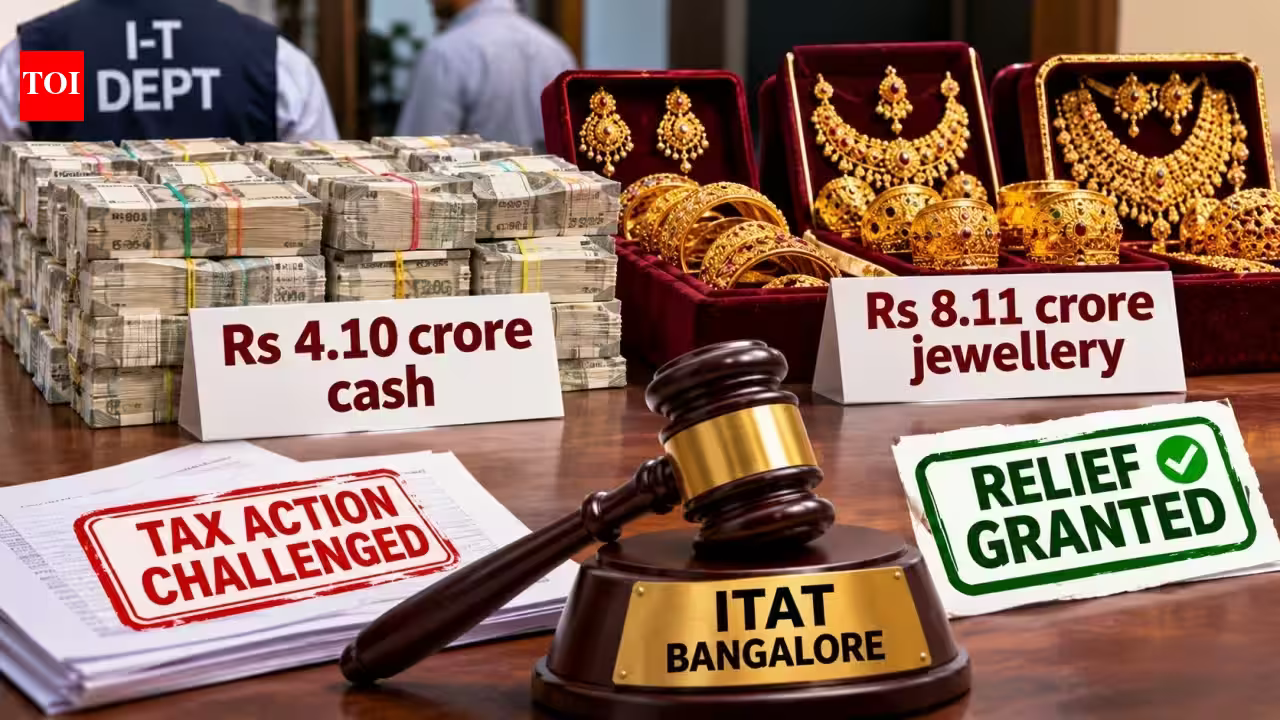
The Bengaluru case involved a search that resulted in the seizure of Rs 4.10 crore in cash and Rs 8.11 crore in jewellery. Initially, the Assessing Officer (AO) categorized these items as unexplained assets, arguing that the taxpayer could not provide sufficient justification for the source of these holdings. The department’s skepticism is a standard procedural approach during investigations where high-value assets are discovered outside of formal banking channels.
However, the taxpayer’s defense rested on his prior compliance. By proactively filing income tax returns that declared substantial business income and by maintaining consistent financial statements, he was able to demonstrate that the seized assets were, in fact, accounted for. The tribunal’s decision highlights a fundamental principle: transparency in reporting serves as the primary shield against allegations of tax evasion. When a business owner treats their tax filings as an accurate reflection of their ongoing capital accumulation, they provide the documentation necessary to rebut claims of “black money.”
The Legal Threshold for Proving Business Income
One of the most vital takeaways from the ITAT ruling is the importance of the nexus between business operations and personal asset accumulation. The tribunal noted that the taxpayer had provided audited financial statements and wealth tax returns that dated back several years. These documents established a consistent history of asset ownership and income generation, which the AO could not refute with additional evidence.
The tribunal specifically looked for five evidentiary pillars: the taxpayer’s initial statements recorded during the search, the alignment of audited financials with the declared income, the inclusion of the assets in the relevant assessment year’s filings, previous wealth tax disclosures, and post-search affidavits. By satisfying these requirements, the taxpayer successfully pivoted the classification of his assets from “unexplained” to “business income.” This shift is crucial because business income is taxed at regular rates, whereas unexplained assets incur punitive charges and higher tax brackets under the special provisions of the Act.
Challenges in High-Value Asset Management for Indian Businesses
For many entrepreneurs and high-net-worth individuals in India, the custom of holding family jewellery and cash reserves in private lockers is common. However, the regulatory environment has become increasingly stringent. Digitization of land records, the mandatory linking of Aadhaar and PAN, and the integration of GST data have made it significantly harder to obscure income.
The Bengaluru case illustrates that while the ITAT provides a mechanism for relief, the process is time-consuming and places significant pressure on the taxpayer. Relying on an appellate process is not a strategy; it is a reactive measure. Businesses should ensure that all personal and professional assets are clearly reconciled in their books of accounts. For instance, jewellery or high-value gifts—such as the watches mentioned in the case—must be documented as part of one’s personal portfolio or as business-related acquisitions to avoid ambiguity during an inquiry.
Compliance as a Strategic Business Asset
In the current Indian business context, compliance is no longer merely a legal requirement; it is a fundamental component of enterprise risk management. The Income Tax Department’s focus on unexplained assets under Section 69A is a targeted effort to enforce tax discipline. Business owners must realize that if the IT department discovers cash, it is assumed to be taxable income unless proven otherwise.
To mitigate these risks, businesses should adopt a proactive accounting culture:
1. Maintain contemporaneous records for all cash transactions, especially those involving commissions or professional fees.
2. Regularly update wealth tax disclosures or personal balance sheets to reflect the acquisition of jewellery and high-value items.
3. Ensure that all family members are aligned with the tax filings, as the assets of a family are often scrutinized together during search operations.
4. Keep signed affidavits and supporting documents for large cash withdrawals or capital inflows readily accessible.
Conclusion: Lessons for the Future
The ITAT Bengaluru judgment is a reminder that the law allows for legitimate business practices, provided those practices are substantiated by evidence. The tribunal’s rejection of the AO’s initial assessment proves that if a taxpayer has fulfilled their statutory obligations through accurate ITR filings and clear financial documentation, the law will protect their legitimate income from arbitrary characterization as unexplained wealth.
As the tax administration continues to leverage data analytics to flag irregularities, the era of “unexplained” asset accumulation is drawing to a close. For the Indian business community, the path forward is clear: integrate every asset into the formal economy. By doing so, entrepreneurs not only insulate themselves from the potential trauma and financial drain of tax raids but also enhance the overall credibility of their business ventures. Compliance is the ultimate protection against the ambiguity that leads to prolonged legal battles, ensuring that a businessman’s hard-earned capital remains rightfully his.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News