The Geopolitics of Energy and the Nord Stream Negotiations
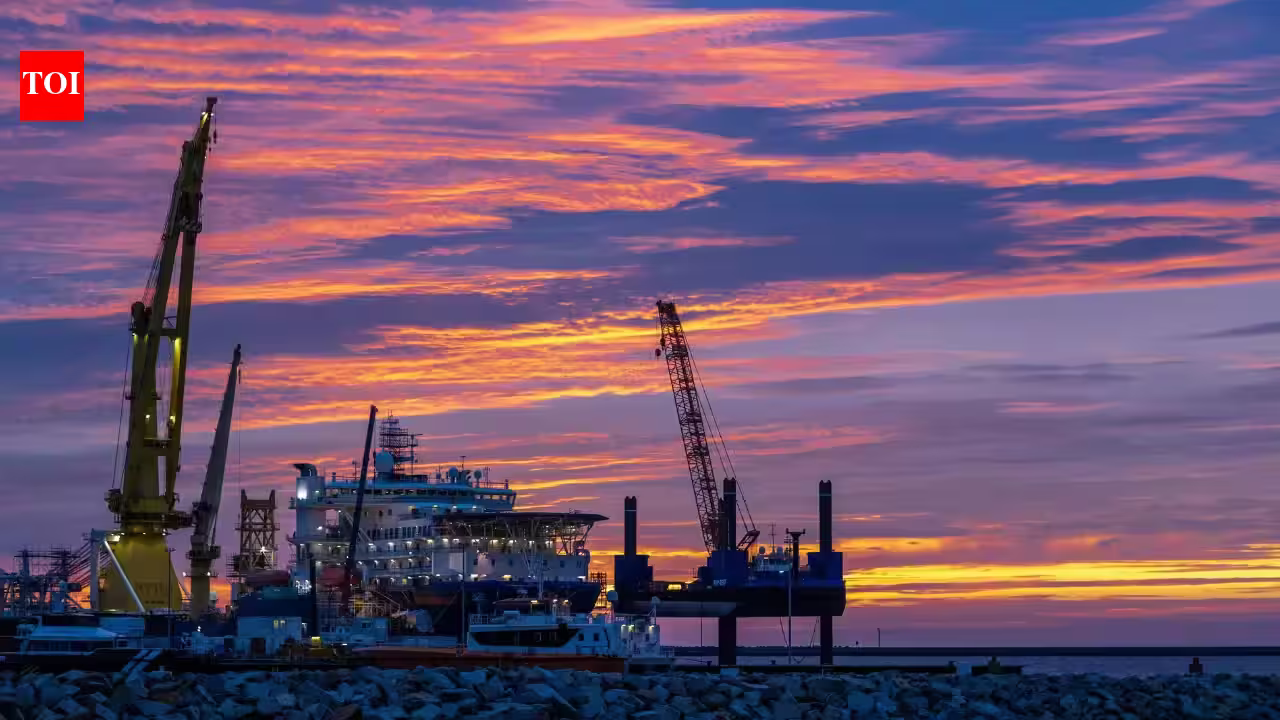
The prospect of reviving the Nord Stream pipeline network, which once served as the primary conduit for Russian natural gas into the heart of Europe, has surfaced as a high-stakes diplomatic and commercial endeavor. Recent reports indicate that discussions are underway involving high-level intermediaries, including former US officials and Russian advisers, to explore the potential for US investment in these dormant energy assets. This development highlights a complex nexus where energy security, international sanctions, and post-war economic reconstruction converge.
From an analytical perspective, the return of Russian gas to the European market is not merely a logistical challenge but a profound geopolitical pivot. Before the 2022 invasion of Ukraine, Germany relied on these pipelines for over half of its natural gas imports. The subsequent mothballing and physical damage to the infrastructure fundamentally altered the European energy landscape, forcing nations to pivot toward liquified natural gas (LNG) from the United States, Qatar, and other global suppliers. Attempting to reverse this shift involves navigating a labyrinth of legal, political, and security barriers that remain firmly in place due to ongoing regional tensions.
Institutional Obstacles and the Sanctions Framework
Any discussion surrounding the restart of Nord Stream must confront the reality of existing sanctions. Both the United States and the European Union maintain stringent restrictions on Russian energy infrastructure, rendering the current status of the pipelines legally inaccessible to international investors. For a deal to materialize, significant shifts in US and EU policy would be required, potentially involving the lifting or suspension of sanctions.
The involvement of US entities, such as the International Development Finance Corporation (DFC), suggests an effort to frame this as an initiative that would serve American economic interests. However, the official stance remains cautious. Any project involving US taxpayer capital or entities would require rigorous vetting to ensure it aligns with national security interests and adheres to international law. Furthermore, the volatility of the American political cycle, including the potential for shifting majorities in Congress, complicates the long-term viability of any agreement that depends on the discretionary waiving of sanctions. The current administration has signaled that any discussions regarding Russian energy assets must be weighed against their potential to benefit American companies and taxpayers, creating a narrow corridor for negotiation that is fraught with risk.
The European Energy Divide and Strategic Divergence
While some factions seek to explore commercial re-engagement, European consensus is conspicuously absent. Germany, the primary destination for the pipeline’s output, is currently divided. While certain political factions advocate for the economic benefits of cheaper, reliable energy, the ruling coalition and broader industrial consensus have remained firm in their opposition. Germany has spent the last two years aggressively diversifying its energy imports and investing in domestic infrastructure to reduce dependence on Moscow, viewing the cost of such independence as a necessary premium for security.
In Eastern Europe, particularly in Poland and the Baltic states, the opposition to reopening Russian energy conduits is absolute. These nations view energy ties to Russia as a strategic vulnerability that grants Moscow undue leverage. The prevailing sentiment across much of the EU is that energy policy is inextricably linked to defense policy. As European nations continue to scale up military spending to bolster their defenses against Russia, the notion of simultaneously financing Russian state-owned energy assets creates a strategic contradiction that many European governments find difficult to reconcile.
The Role of Asset Ownership and Global Energy Markets
The technical and corporate ownership structure of Nord Stream provides another layer of complexity. With Gazprom maintaining a 51 percent majority stake, the pipeline remains a instrument of Russian state policy. Minority stakeholders, including German, French, and Dutch entities, face a difficult position regarding their own holdings. There is a strong desire among European shareholders to prevent a total exit that would leave the infrastructure entirely under Russian control or lead to its permanent abandonment.
Beyond the pipeline itself, the broader discussion involving Russian energy assets—such as those held by Lukoil—suggests a potential restructuring of Russian energy footprint in Europe. By proposing a consortium involving US, Qatari, and UAE investors to manage these assets, the parties involved are essentially seeking to decouple Russian physical production from European distribution. For global investors, this is a matter of market efficiency and energy supply chain stability. For the Russian state, it is an attempt to mitigate the impact of sanctions on key revenue-generating assets.
Indian Market Insights and Global Energy Implications
For India, a major energy importer with a strategic interest in stable global commodity prices, these developments are significant. India’s energy strategy has historically focused on price stability and diversification. The country has notably increased its procurement of Russian oil since 2022, leveraging competitive pricing to manage its own domestic inflation. However, the potential for a formal US-backed energy deal involving Russia provides a new reference point for how emerging economies might navigate sanctions.
If the US were to facilitate a framework where Russian assets are managed by a neutral, international consortium, it could provide a roadmap for other nations to re-engage with Russian commodities without violating primary sanctions. For Indian businesses and government policymakers, this indicates that the “sanctions-proof” model is moving toward a more nuanced, managed reality. While India continues to advocate for a peaceful resolution to the conflict, it also observes the evolving economic reality: global energy markets are becoming increasingly fragmented, yet remain highly interconnected.
The long-term impact on the Indian economy would be twofold. First, a potential restart of Russian gas flows to Europe could temper global gas prices, reducing the burden on India’s LNG imports. Second, it highlights the importance of keeping energy supply chains insulated from sudden geopolitical shocks. As India continues to expand its own gas infrastructure and transition toward a greener energy mix, the stability of global supply chains—regardless of the origin of the fuel—remains a critical priority.
Ultimately, the prospect of resurrecting Nord Stream remains a low-probability event in the immediate future, given the depth of the current conflict and the level of mistrust between Russia and the West. However, the very existence of these conversations illustrates that even in a climate of intense hostility, economic interests exert a gravitational pull. The challenge for policymakers, both in the West and in emerging markets like India, is to distinguish between short-term commercial opportunities and the long-term requirements of regional and global security. Any resolution to this complex scenario will require not just a business deal, but a fundamental realignment of political trust.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News