Mexico’s digital economy reached a significant inflection point in 2025, as cashless transactions surged to record levels. According to the latest annual financial market infrastructure report from the central bank, Banxico, the country processed 12.12 billion electronic card operations, moving a staggering MX$6.90 trillion (US$402.45 billion). This evolution reflects a profound structural transition in how consumers interact with the formal economy, moving away from cash toward integrated digital financial services.
The Rise of Non-Bank Aggregators and POS Infrastructure
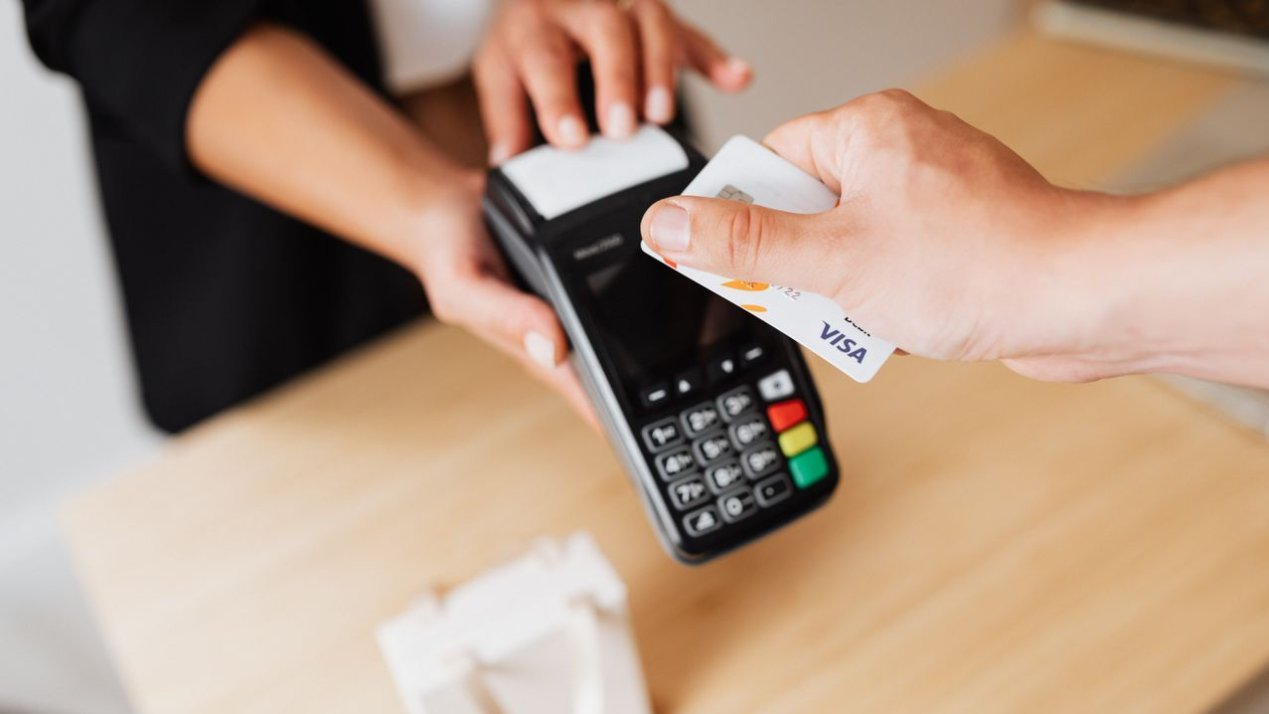
The physical retail landscape is currently undergoing a massive overhaul, characterized by the decentralization of payment terminals. While traditional banks once dominated the merchant services market, non-bank financial intermediaries (IFNBs) and payment aggregators now control 79% of the country’s 6 million installed Point-of-Sale (POS) terminals.
This shift is not merely about physical hardware; it is a tech-driven expansion that is rapidly lowering the barrier to entry for small and medium-sized merchants. As traditional banking infrastructure growth stagnated at a modest 0.2% annually, non-bank aggregators saw an 8.7% surge in terminal deployment. This suggests that the fintech sector is winning the race to digitize the “long tail” of Mexican commerce, effectively bringing smaller retailers into the formal electronic payment ecosystem through streamlined onboarding and more flexible hardware solutions.
Contactless and Digital Channel Dominance
The technology driving this growth has moved beyond simple card-swiping. Contactless payments have seen an explosive 213% increase in volume, reaching 1.818 billion transactions in 2025. This rapid adoption signifies a change in consumer sentiment; convenience and speed are now the primary drivers of transaction frequency.
The digital ecosystem is also expanding through “card-not-present” (CNP) channels. With over 8 billion approved transactions occurring outside of physical terminals, the reliance on digital integration for e-commerce and app-based payments has reached a stage of maturity. This digital-first approach is being reinforced by major industry players like Prosa, who note that over 31% of all card activity now originates from digital channels. As this ecosystem integrates with advanced AI-driven security protocols to manage the shifting risk profiles of credit-reliant consumers, the reliance on traditional physical currency continues to dwindle, particularly for routine household expenditures.
Banking, Credit, and the Future of Financial Inclusion
The expansion of the payment infrastructure is closely mirrored by a rise in credit reliance. With 37.1 million credit card contracts currently active—led by major institutions like BBVA and Banamex—the appetite for revolving credit to fund daily living expenses has hit record highs. By June 2026, commercial bank credit card balances climbed to MX$709.27 billion, an 8.2% real increase that highlights how deeply embedded digital credit has become in the modern Mexican household.
For the average adult, the intensity of card usage has nearly doubled in some categories over the last five years. As the country moves toward a cashless future, the financial system is leaning on technology to bridge the gap between casual shoppers and the formal banking sector. The rapid deployment of contactless terminals and the rise of digital-native payment processors are not just upgrading hardware—they are fundamentally restructuring the Mexican economy, making high-frequency electronic transactions the standard for everything from large retail purchases to minor everyday expenses. As these systems continue to scale, the focus will likely shift toward maintaining security and managing the risks inherent in an increasingly credit-dependent, digital-first population.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News