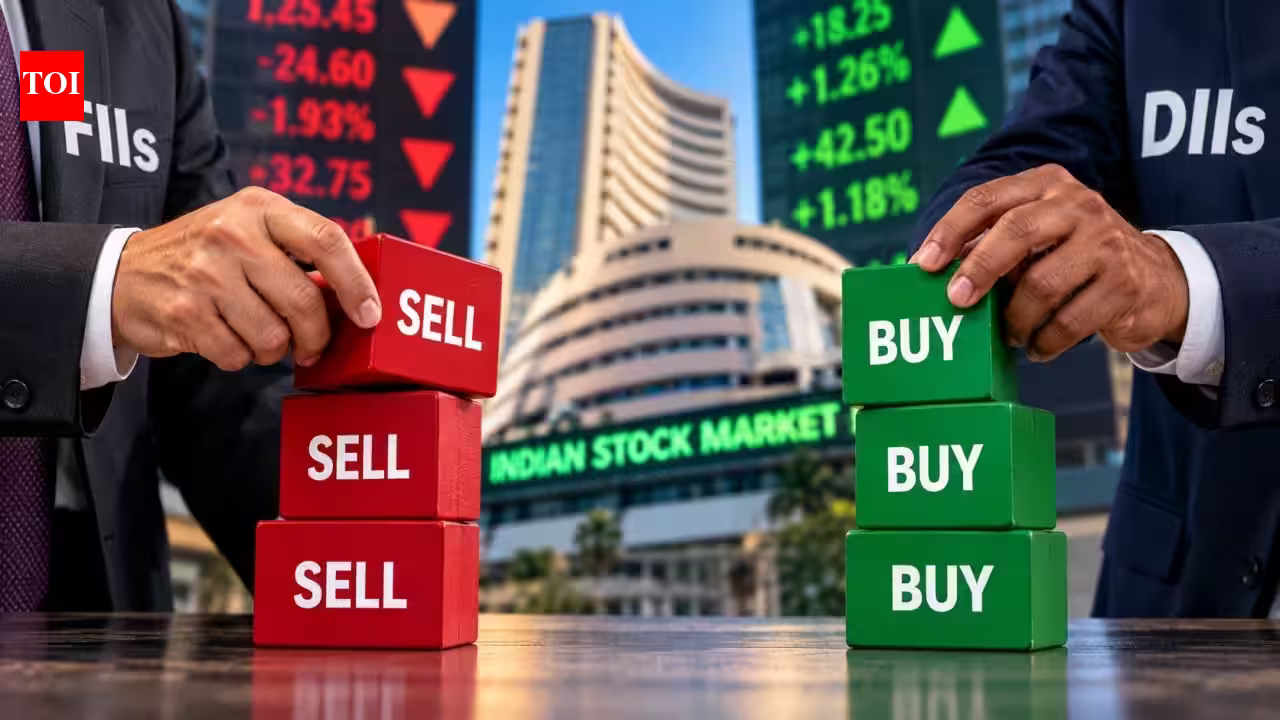
The Indian equity market is currently navigating a period of significant transition, characterized by a distinct divergence between Foreign Portfolio Investors (FPIs) and Domestic Institutional Investors (DIIs). As of mid-2026, the market is experiencing a tug-of-war that underscores the changing dynamics of global capital allocation versus internal economic confidence. While foreign capital continues to exhibit volatility, domestic liquidity remains a stalwart pillar, keeping the benchmark indices—the Sensex and the Nifty—from succumbing to deep, systemic corrections.
The Mechanics of FPI Selling and DII Resilience
The primary driver behind the recent foreign exit from Indian equities is the shift in global macroeconomic conditions. FPIs operate on a global playing field, constantly assessing opportunity costs. When US bond yields rise—particularly with the 10-year yield hovering near 5%—the relative attractiveness of riskier emerging market assets like Indian stocks diminishes. For global investors, these yields represent a “risk-free” return that provides a formidable competitor to the equity risk premium offered by the Indian market.
Furthermore, the strength of the US Dollar and the resulting pressure on the Indian Rupee add layers of complexity. A depreciating rupee increases the hedging costs for foreign allocators, effectively eroding their returns upon repatriation. This currency risk, combined with elevated oil prices and geopolitical tensions in West Asia, has prompted a cautious withdrawal. However, this selling is not monolithic. It is important to distinguish between tactical shifts in asset allocation and a fundamental loss of confidence. Data suggests that FPIs continue to participate in the primary market, indicating that while they may be trimming secondary market exposure, they remain interested in specific growth-oriented corporate opportunities.
Conversely, DIIs are providing a counter-cyclical safety net. This is largely driven by a profound transformation in the Indian domestic investor profile. The rise of Systematic Investment Plans (SIPs) has institutionalized retail savings, creating a steady stream of capital that enters the market regardless of daily fluctuations. With SIP inflows consistently exceeding Rs 30,000 crore per month through the current fiscal year, the domestic market now possesses a structural buffer that it lacked in previous decades.
Valuation Concerns in a Global Context
A central point of contention in the current market environment is the valuation of Indian equities. Many international analysts view the Indian market as expensive relative to other emerging markets. Post-correction, these valuations are still considered elevated by global standards, which FPIs use to justify their rebalancing efforts.
Neeraj Gaurh, Director & Fund Manager at Anand Rathi AMC, highlights that while domestic investors are anchoring their decisions on a normalization of nominal GDP growth, resilient manufacturing, and robust credit expansion, foreign investors are more sensitive to global liquidity and relative valuation gaps. For FPIs, India is one of many allocations; if the valuation gap between India and, for instance, North Asian markets like Japan or Korea widens, capital tends to rotate toward the cheaper or higher-growth alternatives.
This suggests that for the Indian market to attract sustained, high-conviction foreign capital again, it must demonstrate consistent earnings growth that justifies its premium. Domestic investors appear to have already priced in this growth, focusing on the long-term compounding potential of the Indian economy rather than short-term price-to-earnings multiple expansions.
The Role of Domestic Liquidity as a Market Stabilizer
The shift in the domestic investor base is arguably the most significant development in India’s financial landscape over the last five years. The maturity of the retail investor, moving from speculative trading toward disciplined, long-term SIP-based investing, has fundamentally altered the market’s support structure.
This new category of long-term investors remains largely unperturbed by geopolitical noise or temporary sell-offs. Their behavior suggests that for a significant portion of the Indian population, equity participation has become an essential component of wealth creation, decoupled from the knee-jerk reactions often seen in the institutional space. As VK Vijayakumar of Geojit Investments points out, if the market corrects due to aggressive FPI outflows, DIIs and retail investors now have the dry powder to step in and capture the value. This creates a floor for the market, preventing the kind of liquidity-driven crashes that characterized past eras of foreign capital dependence.
Outlook: Navigating the Path Ahead
As we look toward the next 6 to 12 months, the trajectory of the market will remain tethered to a few critical variables. Geopolitical stability is perhaps the most immediate catalyst. A de-escalation of the US-Iran conflict would likely lead to a sharp cooling of crude oil prices, which would benefit India’s current account, reduce inflationary pressures, and, by extension, provide the Reserve Bank of India with more room to maneuver.
Corporate earnings will also play a decisive role. As long as Indian firms can maintain double-digit earnings growth, the current valuation levels will appear justified over the medium term. However, there are risks. A prolonged period of high inflation, or a significant slowdown in specific sectors like IT or Oil Marketing Companies (OMCs), could force a re-evaluation of the current optimism.
Investors are advised to maintain a focus on quality. In a volatile environment, companies with robust balance sheets, strong free cash flows, and sustainable competitive advantages are better positioned to weather macroeconomic headwinds. The strategy of using a staggered approach through SIPs remains the most effective way for retail investors to navigate these peaks and troughs.
Synthesis of Contrasting Investment Perspectives
The current market environment is a classic study in the difference between tactical allocation and structural growth. FPIs are effectively managing their risk by shifting exposure to environments with higher relative stability or better yield profiles. DIIs, meanwhile, are betting on the domestic growth story, which is backed by the country’s demographic dividend, infrastructure spending, and digital transformation.
Who is right? The answer depends entirely on the horizon. For the short-term institutional allocator, the global macroeconomic environment dictates a defensive stance. For the domestic investor with a 3- to 5-year outlook, the underlying strength of India’s economy suggests that current price fluctuations are mere noise in a larger growth narrative.
Ultimately, the Indian market is evolving into a more mature ecosystem. The reduced sensitivity to foreign selling is a testament to the growth of domestic financial awareness and the effectiveness of systematic savings. While volatility is likely to remain high as long as global uncertainties persist, the sustained support from domestic investors provides a robust foundation for future stability. Investors would do well to balance their portfolios, maintain a long-term focus, and avoid being swayed by the temporary outflow of foreign capital, recognizing that the domestic engine of the Indian stock market has never been more resilient.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News