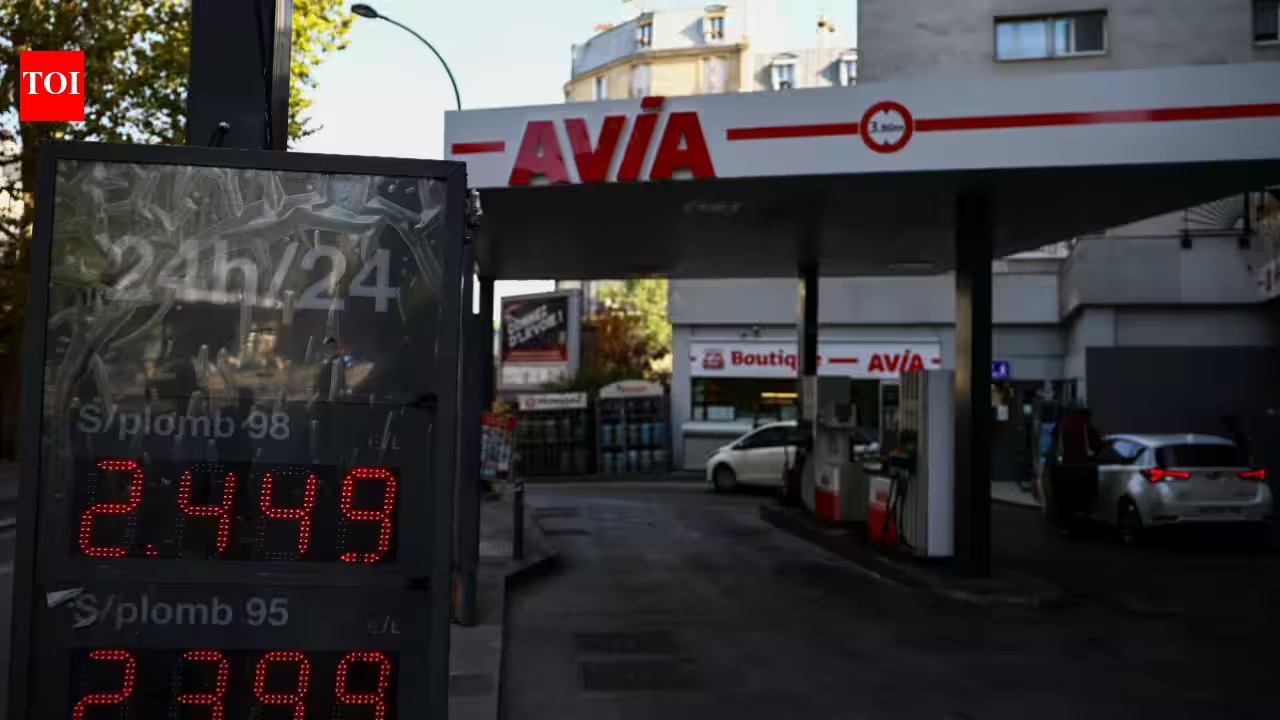
The Global Diesel Squeeze: Drivers of Unprecedented Volatility
The global energy landscape is currently navigating a period of profound instability, characterized by record-high diesel prices that threaten industrial productivity and economic stability across major markets. As geopolitical tensions in the Middle East and the ongoing conflict in Ukraine continue to compromise critical supply chains, the global diesel market has entered a phase of sustained fragility. This crisis is not merely a reflection of crude oil fluctuations but is fundamentally rooted in the degradation of refining capacity and the systemic breakdown of traditional trade routes.
The surge in diesel prices—a commodity essential for heavy transport, global logistics, agriculture, and manufacturing—has created a paradox for policymakers. While global refinery utilization rates have been pushed to near-maximum levels in an attempt to compensate for missing output, the reality remains that structural bottlenecks prevent an adequate supply response. With inventories in key hubs like Amsterdam-Rotterdam-Antwerp and the United States remaining significantly below their five-year seasonal averages, the margin for error in the global supply chain has effectively vanished. This state of imbalance indicates that the market is currently price-inelastic in the short term, as industrial sectors lack the ability to quickly pivot away from diesel-dependent operations.
Geopolitical Disruption and the Infrastructure Crisis
The core of the current diesel crisis lies in the intersection of military conflict and energy infrastructure vulnerability. Russia, historically a primary supplier of global diesel, has faced severe operational constraints due to targeted strikes on its refineries. These drone-led incursions have not only curtailed Russian output but have also forced a significant realignment of global trade flows. Countries that formerly relied on Russian imports have been compelled to compete for limited volumes elsewhere, creating a ripple effect that destabilizes regional pricing.
Simultaneously, the situation in the Middle East has disrupted the flow of refined products through vital maritime corridors. Shipping data highlights a dramatic reduction in diesel exports from Middle Eastern producers, who were previously critical to meeting European demand. When combined with the complications in the Red Sea—a primary artery for Saudi Arabian exports—it becomes evident that the logistics of moving fuel are as compromised as the production itself. For the global economy, this means that even if upstream crude oil production were to remain stable, the midstream conversion of that crude into high-demand diesel is failing to meet the requirements of a post-pandemic industrial world.
Implications for the Indian Economy
For a developing economy like India, the global diesel squeeze represents a significant fiscal and inflationary risk. As a major importer of crude oil and a growing consumer of refined products, India is highly sensitive to the cost of international energy. The domestic retail price of diesel is intrinsically linked to the global benchmark, and persistent high prices pose a direct threat to the nation’s logistics costs. Given that diesel powers the vast majority of India’s heavy trucking, rail freight, and agricultural machinery, any prolonged spike in international prices invariably translates into higher transportation costs for essential goods, fueling domestic inflation.
Furthermore, India’s refining sector, while robust, operates within the context of a highly integrated global market. When international diesel supplies tighten, domestic refiners face pressure to prioritize exports to capture higher margins in the global spot market, which can inadvertently lead to domestic supply pressures. The government is tasked with the delicate balance of maintaining affordable energy access for the transport and farming sectors while managing the fiscal impact of subsidies or tax cuts. If international prices remain at these record levels, India may be forced to further accelerate its transition toward alternative energy sources and increase efforts to diversify crude import origins to hedge against the volatility emanating from the Middle East and Europe.
Supply-Demand Imbalances and Inventory Deficits
Market analysts point to the widening gap between supply and demand as the primary driver of current price surges. Despite high refinery utilization, particularly in the United States, inventory levels have failed to recover to necessary thresholds. The fact that US diesel stocks remain nearly 15 percent below the five-year average despite record-high refinery throughput is a testament to the persistent, structural deficit in the market.
This scenario is exacerbated by cyclical demand from industrial sectors. Construction, agriculture, and manufacturing all demonstrate high levels of “stickiness” regarding fuel consumption; they cannot easily reduce their diesel intake in response to price spikes without compromising their own output. This leads to a scenario where prices are forced upward by necessity rather than discretionary spending. As long as these inventories remain depleted, the potential for further price volatility is extreme. A single disruption—whether it be an unexpected refinery outage or a maritime blockage—could lead to further drastic, short-term price adjustments, as there are currently no significant secondary or tertiary buffers to mitigate supply shocks.
The Search for Policy Options and Market Adjustments
Addressing the current price crisis presents limited viable pathways for governments and energy firms. In the short term, there are few levers to increase the supply of diesel without the reactivation of mothballed or idle refining capacity, a process that is both capital-intensive and time-consuming. Even where latent capacity exists on paper, it often lacks the technical capability to process available crude grades or has been sidelined due to a lack of maintenance during the recent era of underinvestment in fossil fuel infrastructure.
The most pragmatic, albeit difficult, solutions involve market-driven demand destruction or significant geopolitical de-escalation. If supply constraints continue to keep prices near record levels, the economy will inevitably be forced to adjust through reduced activity in energy-intensive sectors, which carries the risk of economic contraction. Alternatively, a resumption of normal trade flows through key shipping channels, such as the Strait of Hormuz, would provide the most immediate relief. However, as the International Energy Agency has noted, until commercial inventories are replenished, the market will remain hyper-sensitive to any geopolitical noise. The overarching lesson for global energy policy is the danger of relying on thin inventory buffers; in an era of persistent conflict, the absence of surplus production capacity and storage is a fundamental vulnerability that ensures volatility will persist for the foreseeable future.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News