The Macroeconomic Pressures Behind Market Volatility
The Indian equity market is currently navigating a period of significant turbulence, characterized by a sharp correction that has alarmed institutional and retail participants alike. The convergence of multiple adverse macroeconomic variables—specifically the escalation of global crude oil prices and the sustained rise in US Treasury bond yields—has created a challenging environment for emerging markets. Brent crude, trading above $105 per barrel, acts as a primary inflationary catalyst for India, given its status as a net importer of energy. Higher oil prices exert direct pressure on the country’s current account deficit and complicate the central bank’s efforts to manage domestic inflation.
Simultaneously, the surge in US Treasury bond yields to two-decade highs has fundamentally altered the risk-reward profile of global investments. When risk-free rates in the United States climb, assets in emerging markets like India become relatively less attractive to global capital managers. This yield differential prompts a capital migration from equity markets back into dollar-denominated fixed income, resulting in depreciation pressure on the Indian rupee. As the rupee approaches the 96.8 level against the dollar, the cost of imports rises, further squeezing corporate margins and fueling concerns regarding sustained profitability for large-cap entities.
Understanding the FPI Liquidation Cycle
The recent decline in the Sensex and Nifty has been accelerated by an aggressive exit strategy adopted by Foreign Portfolio Investors (FPIs). In a single session, net outflows reached approximately Rs 13,000 crore, signaling a broad-based withdrawal rather than sector-specific rebalancing. This liquidation cycle is a reflection of global risk-off sentiment. As global liquidity conditions tighten, institutional managers prioritize the preservation of capital, often liquidating holdings in high-growth markets like India to cover margin requirements or to reallocate into safer jurisdictional assets.
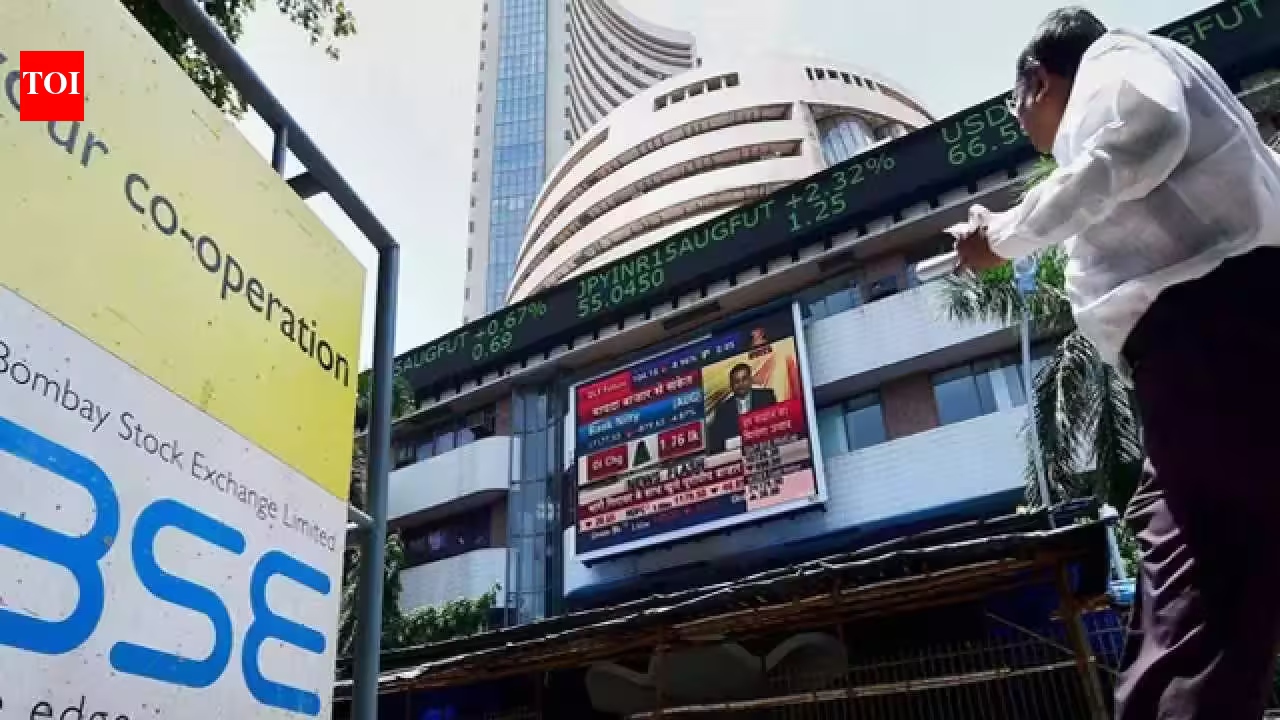
The sheer scale of this sell-off has fundamentally disrupted market technicals. With blue-chip constituents like Reliance Industries, HDFC Bank, and Bharti Airtel experiencing downward pressure, the primary support levels for the benchmark indices have been breached. These companies hold significant weight in the index composition; therefore, their decline exerts an outsized impact on the broader market performance. The resulting erosion of Rs 10 lakh crore in market capitalization in a single trading session underscores the severity of the liquidity vacuum currently facing the BSE and NSE.
Contextualizing India’s Underperformance in a Global Landscape
A critical analytical focus is the disparity between the Indian market’s year-to-date performance and that of its global peers. While the Sensex has recorded a decline of roughly 16% this year, other markets have demonstrated surprising resilience. For instance, Japan’s Nikkei has surged by 33%, and the tech-heavy Nasdaq Composite has maintained a positive trajectory of 17.6%, driven largely by the capital intensity of artificial intelligence investments. The divergence suggests that the current downturn is not merely a global phenomenon but is aggravated by domestic macroeconomic headwinds and valuation corrections following a prolonged period of market euphoria.
In comparison to regional indices such as Hong Kong’s Hang Seng or the Shanghai Composite, the Indian market has suffered a more pronounced reversal. This indicates that investors are applying a higher risk premium to Indian stocks due to the currency depreciation and the aforementioned fiscal implications of high energy costs. The inability of the Indian market to decouple from these global negative catalysts reflects the depth of its integration into international capital flows. When foreign sentiment shifts, the localized support provided by domestic institutional investors—while substantial—has proven insufficient to arrest the momentum of a major global sell-off.
Historical Precedents and the Danger of Persistent Downtrends
The current market environment is historically significant due to the duration of the downturn. The Sensex has grappled with an eight-week losing streak, a trend that is unprecedented in the last 25 years. This technical pattern signals a loss of investor confidence that transcends cyclical fluctuations. The transition from an index level of 78,499 in early August to the current sub-72,000 levels represents a meaningful correction of nearly 9%.
The prospect of a nine-week losing streak carries psychological weight for market participants. Should the index fail to reclaim support levels established in October, it could trigger further algorithmic selling and capitulation by retail investors who entered the market during the previous bull run. The loss of Rs 32.3 lakh crore in aggregate wealth since early August highlights the systemic nature of this correction. Even the inclusion of high-value IPOs, such as the National Stock Exchange listing, has failed to offset the downward trajectory, demonstrating that the sell-off is not concentrated in speculative small-caps but is impacting the structural foundation of the Indian equity indices.
Future Outlook and Structural Adjustments
Looking ahead, the recovery path for the Indian market depends on a cooling of inflationary pressures and a stabilization of the geopolitical factors influencing oil prices. The correlation between the US Federal Reserve’s policy trajectory and Indian market performance remains a primary determinant of short-term direction. If Treasury yields begin to normalize, the pressure on the rupee may subside, providing the Reserve Bank of India with more flexibility to manage monetary conditions without resorting to aggressive interest rate interventions that could further stifle growth.
For corporate India, the challenge lies in managing input costs while maintaining demand in an environment where consumer confidence may be dampened by broader economic uncertainty. Companies with strong balance sheets and the ability to pass on costs will likely outperform as the market begins to bottom out. However, the current phase requires investors to adopt a more cautious stance, emphasizing quality and cash flow generation over valuation-heavy growth narratives. Until FPI activity reverts to a net-buying position, the indices are likely to remain susceptible to volatility. The current correction, while painful, serves as a necessary adjustment to bring asset prices back into alignment with the changing realities of the global cost of capital.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News