The Strategic Rationale Behind Delaying UPI Transaction Charges
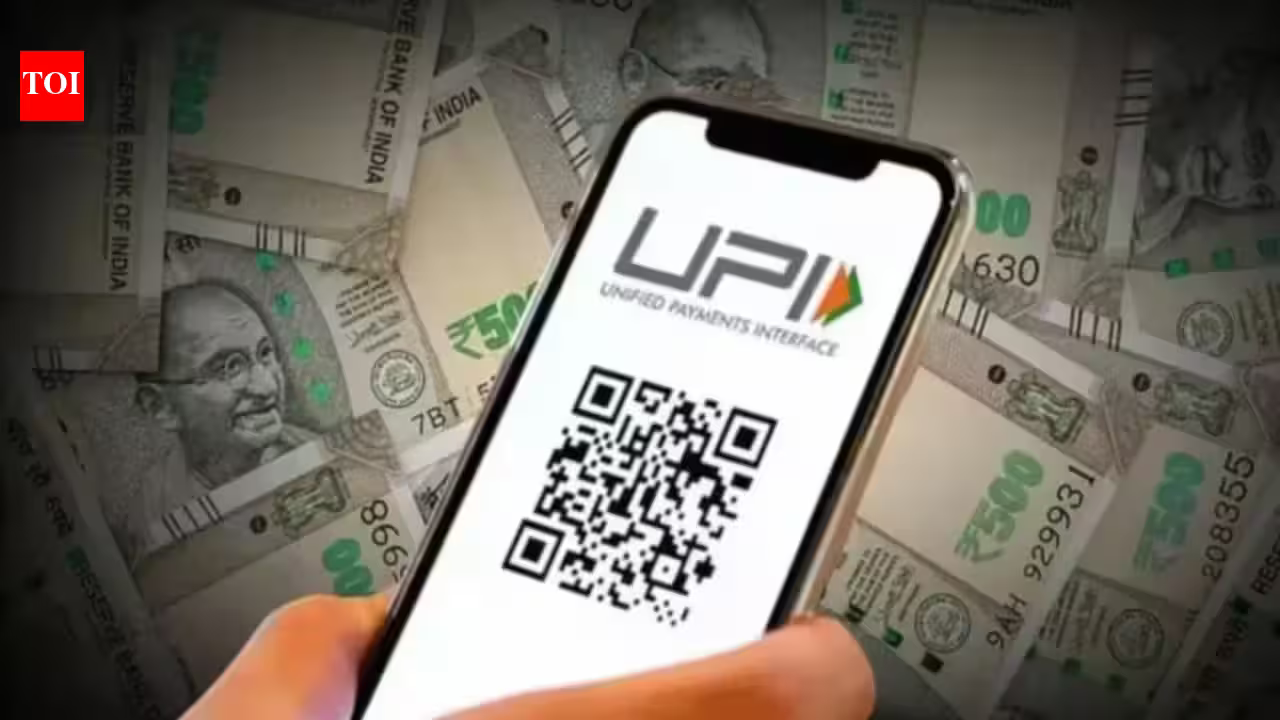
The Indian digital payments landscape has reached an unprecedented scale, largely fueled by the Unified Payments Interface (UPI). For years, the ecosystem has operated on a zero-Merchant Discount Rate (MDR) model, which incentivized mass adoption among both consumers and small-scale merchants. Recently, the National Payments Corporation of India (NPCI) announced a framework to introduce a 0.4% MDR on specific person-to-merchant (P2M) transactions exceeding Rs 2,000. However, in a move reflective of broader economic sensitivity, the implementation of this charge has been deferred until after the Diwali festive season.
This deferment is not merely a bureaucratic delay; it is a calculated measure to protect consumer sentiment and retail momentum during India’s most significant consumption period. By pushing the implementation date, the government and regulatory bodies are acknowledging that introducing transaction costs during a peak period of economic activity could inadvertently dampen trade. Retailers, already managing thin margins, would likely be hesitant to absorb these costs, potentially passing them on to consumers or discouraging digital payments at a time when retail volume is at its annual zenith.
Understanding the Mechanics of the Proposed MDR Framework
To comprehend the significance of this policy shift, one must analyze the proposed structure of the MDR. The framework seeks to implement a 0.4% charge on P2M transactions over Rs 2,000, with a ceiling of Rs 300 for transactions of Rs 75,000 or more. Critically, the policy protects smaller merchants and lower-value transactions, with approximately 96% of P2M transactions expected to remain free of cost. This tiered approach is designed to ensure that the burden of the cost is concentrated on larger, high-value transactions where merchants have higher margins and greater capacity to absorb or pass on the fee.
The intent behind this framework is to foster a sustainable business model for the payment ecosystem. Currently, banks, payment aggregators, and fintech platforms bear the cost of infrastructure maintenance, security, and transaction processing without a direct, transaction-based revenue stream from the majority of UPI payments. As digital payments transition from a growth-at-all-costs phase to a maturity phase, the industry requires a balanced model that compensates service providers for their operational investments while maintaining the accessibility that made UPI a global benchmark for instant payment systems.
Economic Implications for Indian Retail and Digital Adoption
The decision to pause the introduction of MDR highlights the government’s focus on maintaining the momentum of digital adoption. In India, the integration of digital payments into daily commerce has been a transformative force for the formalization of the economy. By keeping the barrier to entry extremely low, UPI has successfully brought millions of unorganized sector merchants into the digital fold. Any sudden shift in the cost structure, especially one perceived as a tax on digital transactions, risks pushing these smaller players back toward cash transactions.
Retail trade bodies and merchant associations have been vocal in their opposition to an immediate rollout, particularly during the festive quarter. In India, the period surrounding Diwali constitutes a major portion of annual sales for businesses ranging from e-commerce platforms to neighborhood kirana stores. Forcing merchants to recalibrate their pricing or accounting systems during this period creates administrative friction. The deferment effectively provides a necessary buffer, allowing businesses to navigate the festive season without adjusting to new financial variables that could disrupt their price competitiveness.
Future-Proofing the Payments Infrastructure
While the current delay is a tactical response to seasonal market conditions, it underscores an inevitable evolution in the digital payment sector. The move toward a sustainable MDR is essential for long-term innovation. Banks and fintech companies are under pressure to continue investing in advanced security, faster settlement times, and innovative features. Without a sustainable revenue stream, the ability of these entities to scale their infrastructure to meet the demands of a growing digital economy would be severely hampered.
Looking ahead, the successful implementation of this framework will depend on clear communication and phased adoption. By providing merchants and payment aggregators with adequate time to integrate the new charges into their point-of-sale software and accounting systems, the NPCI ensures that the eventual transition will be seamless. The focus will likely shift toward educating merchants on the value proposition of digital payments—such as reduced cash handling risks and improved audit trails—which justifies the small transaction fee in the long run.
Balancing Sustainability with Market Growth
The Indian market is unique in its scale and the speed of its digital transformation. Maintaining the current momentum requires a delicate equilibrium between promoting high-frequency usage and ensuring that the underlying service providers remain viable. The current deferment period provides a window for stakeholders to conduct deeper impact assessments. It is an opportunity for the ecosystem to refine its strategy regarding which categories of merchants might be exempted and how the fee structure can be optimized to prevent any slowdown in the shift toward digital cash flows.
Furthermore, the involvement of the finance ministry indicates that digital payments are now considered a critical pillar of national infrastructure. Any changes to the fee structure are scrutinized not just for their business impact but for their macro-economic effects on inflation and consumption patterns. By aligning the implementation timeline with the broader economic calendar, regulators are demonstrating a sophisticated approach to policy management, one that prioritizes consistent growth over short-term revenue gains.
Conclusion: The Path Toward a Mature Digital Ecosystem
The deferment of the 0.4% MDR on UPI transactions is a prudent decision that reflects a mature approach to regulating one of the world’s most successful digital payment networks. It safeguards the festive retail environment, allows merchants time to adapt to new operational realities, and provides the necessary breathing room for the payments industry to prepare for a shift in the revenue model. As India continues to lead global digital payment growth, the transition toward a sustainable, fee-based model remains a logical progression. While the cost of processing payments will eventually be shared across the value chain, the current strategy ensures that this shift does not come at the expense of the widespread digital penetration that defines the modern Indian marketplace. By opting for a phased introduction rather than an immediate, disruptive change, authorities are ensuring that the long-term viability of the UPI ecosystem is secured without compromising the retail vibrancy that fuels the Indian economy.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News