The landscape of digital financial transactions in India has evolved rapidly, with Initial Public Offerings (IPOs) becoming a common gateway for retail investors to participate in wealth creation. However, the reliance on intermediary institutions—such as banks acting as Self-Certified Syndicate Banks (SCSBs)—introduces the risk of operational errors. A recent ruling by the Gujarat State Consumer Disputes Redressal Commission underscores the accountability of these institutions, setting a significant precedent for how banking lapses are addressed in the Indian consumer court system.
The Anatomy of the Banking Error
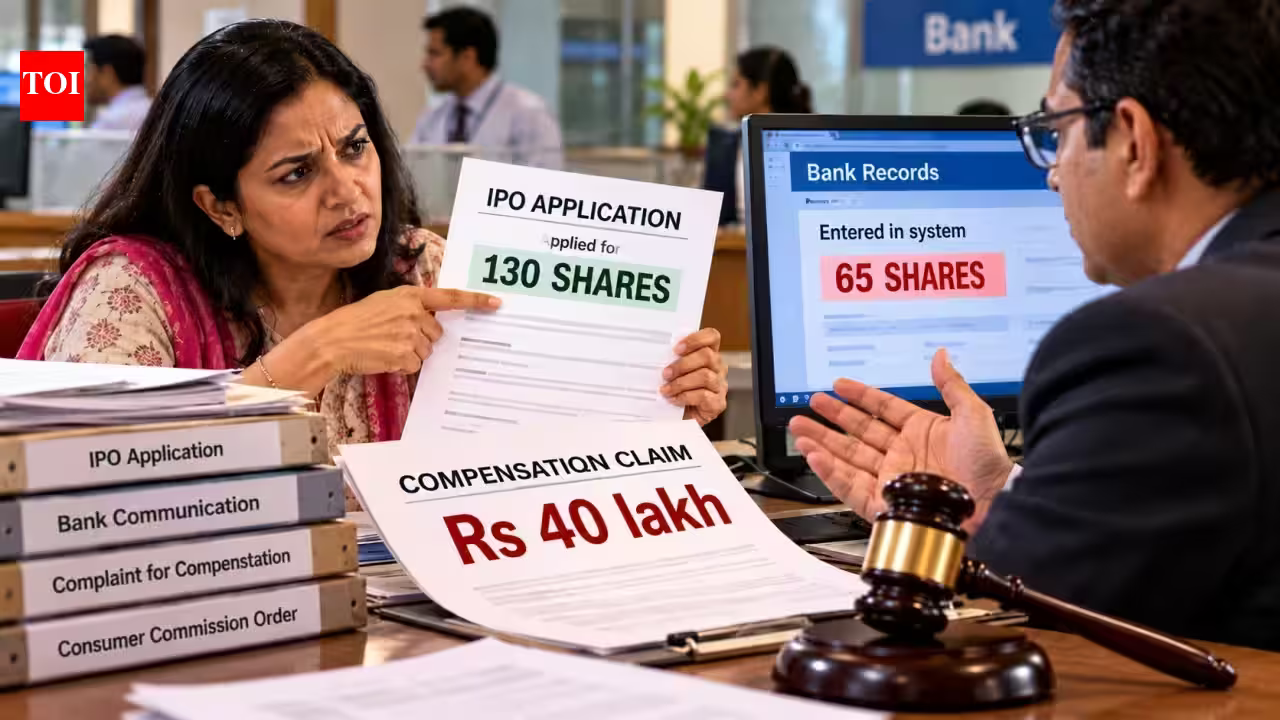
The case originated when an Ahmedabad-based investor applied for 130 shares in an IPO. Due to a clerical oversight by the bank, the application was logged for only 65 shares. The investor contended that this data-entry error directly curtailed her potential investment, alleging a financial loss of approximately Rs 42,142. When the bank failed to address the grievance adequately, the investor escalated the matter to the consumer forum, seeking a substantial compensation of Rs 40 lakh for the loss and the mental hardship endured.
From a banking operations standpoint, the issue highlights a critical vulnerability in the Application Supported by Blocked Amount (ASBA) process. While digitisation has streamlined IPO applications, human intervention in manual data entry or system validation can still lead to discrepancies. The bank’s defense relied on a technical argument: they asserted that since the investment was for profit, the transaction was purely commercial, and the investor, therefore, did not fall under the legal definition of a “consumer” protected by the Consumer Protection Act.
Redefining the Consumer in Financial Services
The initial dismissal of the complaint by the District Consumer Commission on the grounds of “commercial activity” was a setback for the investor. However, the state-level commission’s intervention provided a more nuanced interpretation of Indian law. The commission clarified that merely participating in an IPO does not automatically categorize every banking service failure as a commercial dispute.
The ruling emphasized that banks are service providers held to a high standard of care and accuracy. By ruling that the complainant was indeed a consumer, the commission dismantled the argument that banks are immune to consumer litigation in investment-related transactions. This is a vital development for the Indian market, as it ensures that retail investors are not left without recourse when administrative blunders occur within the banking interface. The commission noted that even if a customer does not pay a direct fee for a specific bank service, the underlying structure—where banks are compensated through institutional channels—establishes a service-provider relationship.
Limitations of Compensation and Speculative Claims
While the commission found the bank guilty of deficient service, it simultaneously rejected the investor’s demand for Rs 40 lakh, labeling it as highly excessive. This aspect of the verdict serves as a cautionary tale for litigants regarding the distinction between actual damages and speculative loss.
The investor argued that her loss was equivalent to the value of the shares she would have received had the application been accurate. The commission, however, pointed out that IPO allotments are subject to complex regulatory procedures, subscription ratios, and oversubscription dynamics. There was no guaranteed path to receiving the full allotment of 130 shares. Consequently, the claim of financial loss was viewed as speculative rather than empirical. This serves as an essential analytical insight: in legal proceedings involving market volatility or unpredictable outcomes, proving “cause and effect” is difficult. The court essentially held that while the bank made a mistake, one cannot assume a guaranteed financial gain in the volatile stock market environment.
Banking Accountability and Operational Standards
The directive for the bank to pay Rs 37,000—comprising compensation for deficiency of service, mental agony, and legal costs—reaffirms that institutional negligence has tangible costs. In the Indian banking context, this case highlights the necessity for robust automated systems. As IPO participation continues to surge in India, banks are processing millions of applications. The “clerical error” defense is increasingly being viewed as a failure of internal control systems rather than an acceptable human lapse.
Financial institutions must now view the accuracy of data entry not just as an operational task, but as a compliance requirement that carries legal risk. The case serves as a reminder to banks to invest in straight-through processing (STP) and validation checks that minimize manual interference. For investors, the takeaway is equally clear: while consumers are protected by law, financial claims for damages must be backed by concrete evidence of loss rather than projections of what “might have been” in a successful stock allotment.
Broader Implications for the Indian Retail Investor
The resolution of this case provides a framework for how retail investors should approach grievances with financial intermediaries. It legitimizes the use of consumer forums as a venue for disputes involving bank-led investment errors, provided the case focuses on the service failure rather than market outcomes.
For the average Indian retail investor, this suggests that the path to justice involves three components: meticulous documentation, a focus on the deficiency of the bank’s service, and realistic expectations regarding compensation. The legal system in India is increasingly cognizant of the power imbalance between individual investors and large banking entities. While the consumer forums are willing to penalize banks for negligence, they are equally rigorous in dismissing claims that lack financial proof or rely on market speculation.
In conclusion, the decision reflects a balanced approach to market justice. By holding the bank accountable for poor service while rejecting an unsubstantiated financial claim, the Commission has upheld the principle of fairness. For the banking sector, it is a call to improve operational transparency and accuracy. For the investor, it reinforces that while they are protected under the law, their responsibility lies in providing clear, evidence-based complaints when seeking redressal for grievances in the complex world of capital markets. This balance remains the cornerstone of a healthy and protected investment ecosystem in India, ensuring that service providers prioritize the customer experience above all else.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News